So $SPCX is forecasting $500B to $1T in AI ARR at YE 2027, on $500B of capex (10 GW increase)?! This is a 1-2x revenue/investment ratio as the entire industry is now at 0.3x. Their 3Q AI capex was only $16B. They had better get going…
(3) And annualized AI revenues were below $20M per MW in the 3Q ($19.5M), a far cry from the $40-50M figures that were thrown around during the quarter. And much closer to where the rest of the industry is. $SPCX
(2) And at a current AI ARR of $30B (3Q x 4), they are not even remotely close to a 1-2x revenue/investment ratio right now, despite the Google and Anthropic deals. $SPCX
@SmallCapSnipa How many capital-intensive business models dependent on technology/availability from others ($NVDA, model companies, etc) have maintained 25-50% ROIC’s over the long-term? Or even the intermediate-term?
@OxfordAnalytics@RandolphDuke7 And yet…the $CRWV 4Q 2026 revenue estimate is up a whopping 3% since the middle of the 2Q. Despite rapidly rising GPU rental rates. Maybe ask yourself why that is.
@OxfordAnalytics@RandolphDuke7 Did it ever occur to you that gauging “demand for compute” by using spot GPU rental rates might be problematic because of how little announced capacity has actually come online?
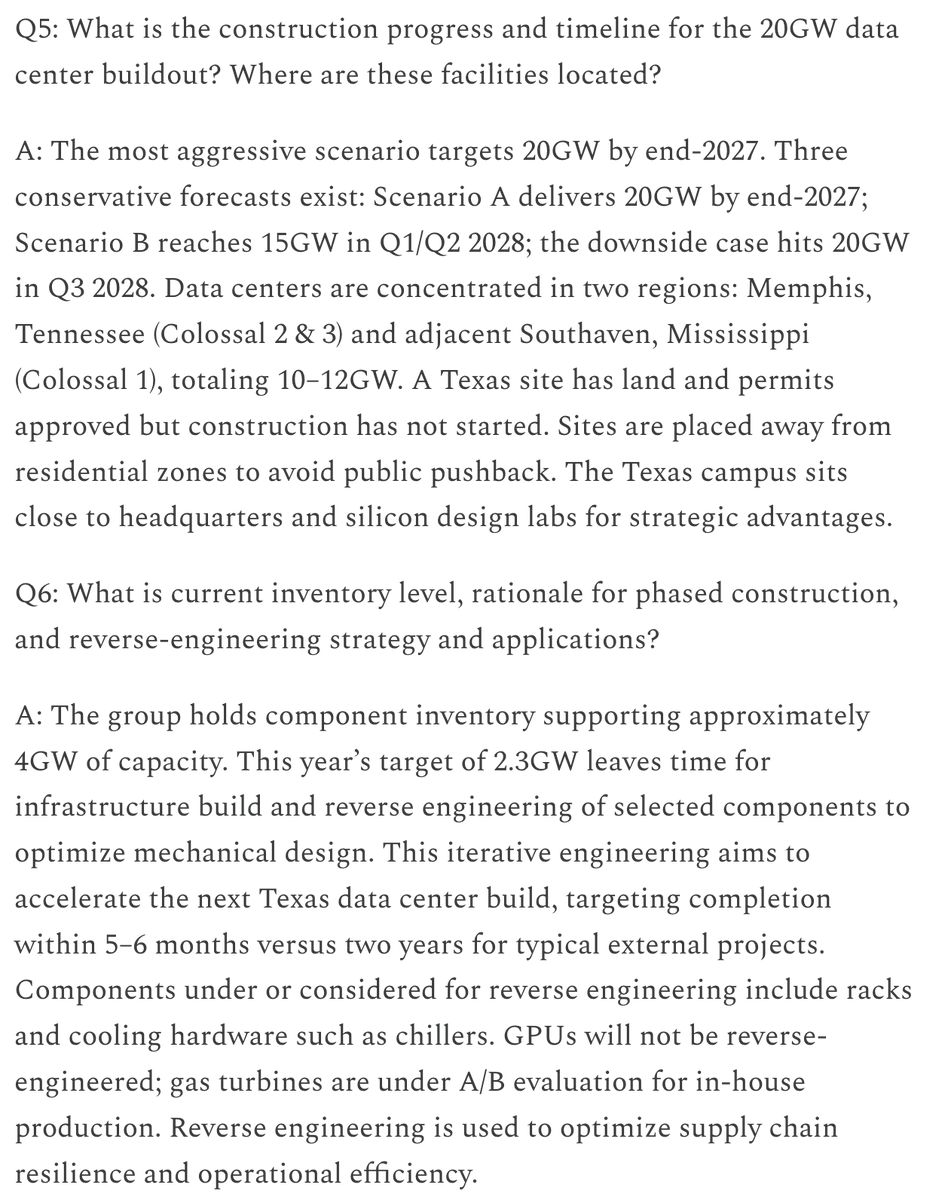
SPCX is aggressively pushing reverse engineering to get around bottlenecks...
Racks, chillers, etc...
So they're going to vertically integrate everything they possibly can.
How do they get around patents and IP with this? Don't they get sued?