@ptuomov Yup. CRE guy here. I wouldn't buy REITs with an enemy's money right now. Completely nonsensical pricing given rates. Most need to trade about 15-20% lower than where they are now IMO.
On average cap rates historically compressed -150 bps during prior Fed cut cycles. It's time to invest in high quality REITs like $O, $PSA, $FRT, $EQIX, & $ADC.
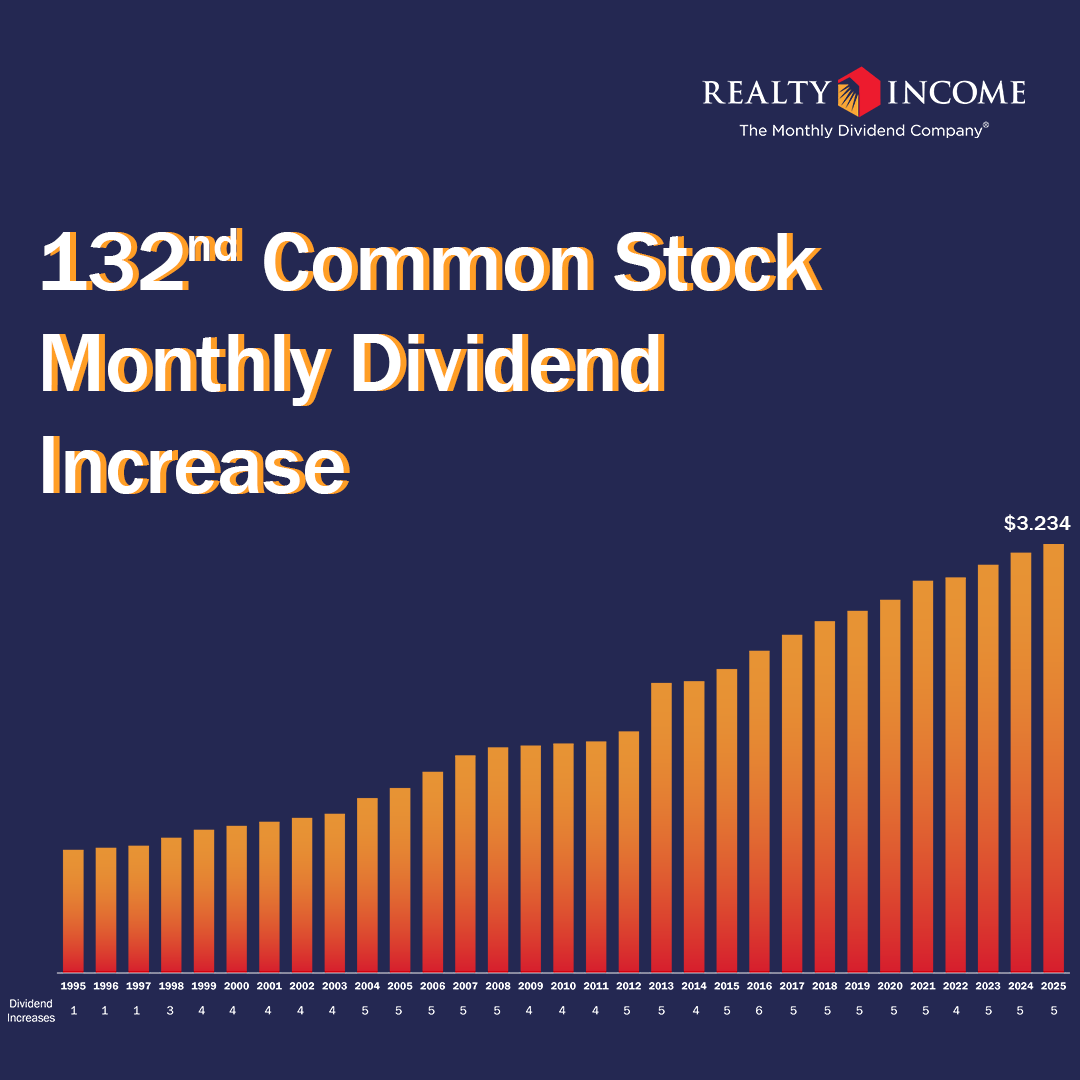
A small dividend increase just announced by $O. I'll take it. Several of these small increases every year, plus a big one every year or two - the compounding adds up.
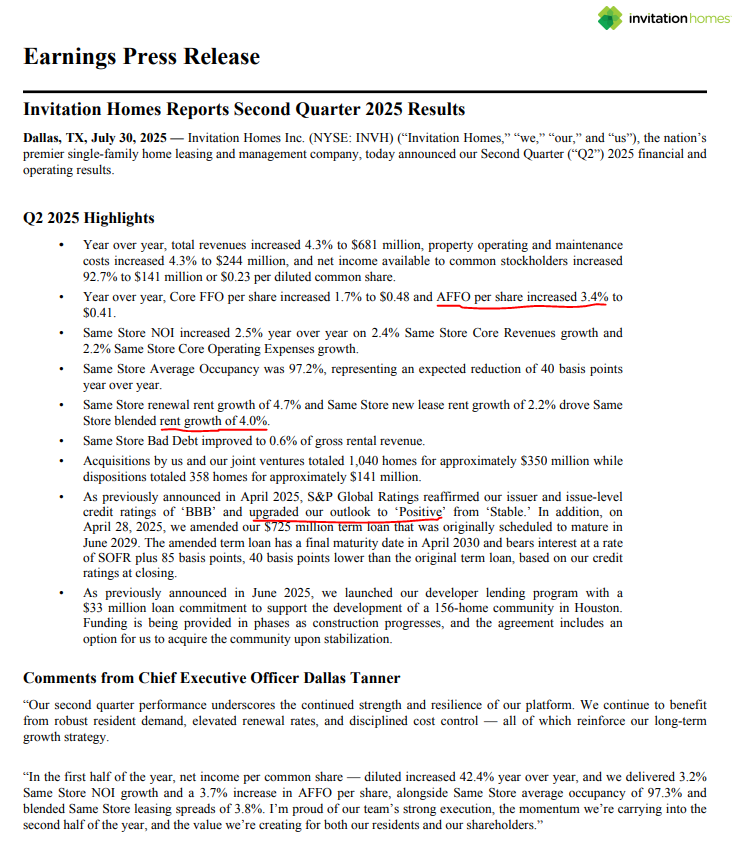
Invitation Homes $INVH, the largest single-family residential REIT performed well in Q2. They have an impressive 5Y Div CAGR of 15.48%, beating most other REITs. On my radar.
Essex Property Trust $ESS Q2 looking stable and solid. Their focus on high-demand West Coast multifamily housing markets makes them appeal as a safe bet in the beaten down apartment sector.
Not alot of difference in 5Y total return in the multifamily REIT segment, with $AVB. Macro environment has compressed valuations in a 10Y perspective. I expect a significant increase if/when rates drop.
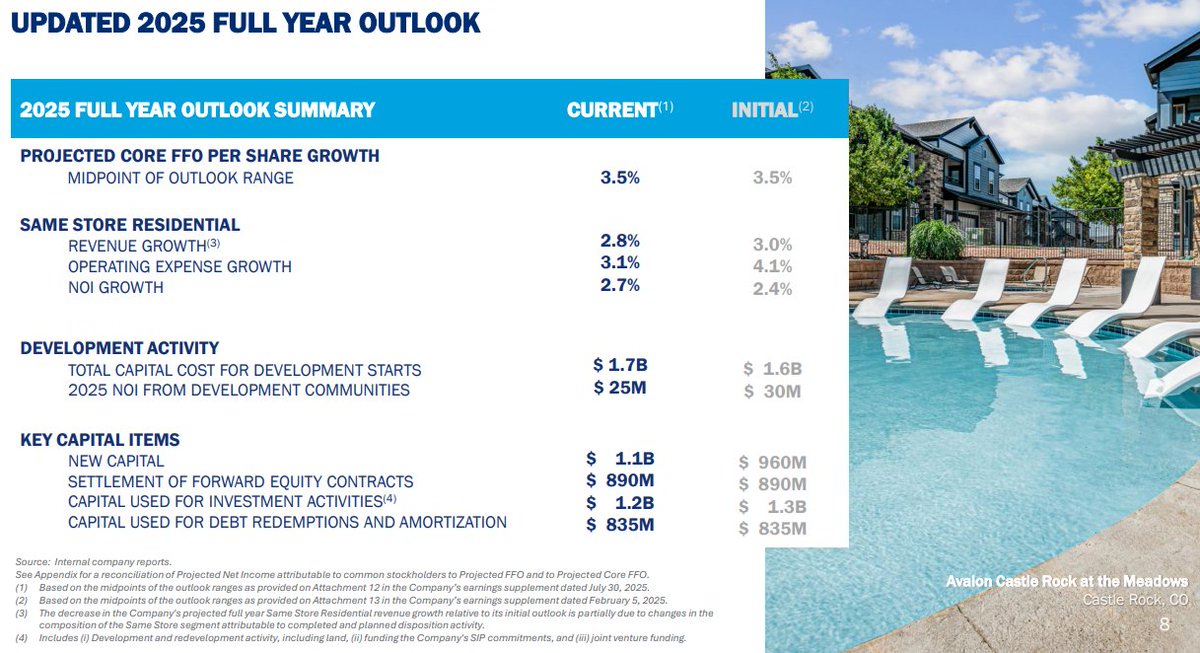
Stable projected FFO/sh growth from AvalonBay $AVB. Multifamily REITs valuations are very low looking back 10Y. Could be a great opportunity - or just the "new normal".
Alexandria $ARE overall portfolio occupancy has declined to 90.8%, a drop from 94.6% a year ago, while tenants are delaying leasing decisions. FFO/sh has also declined. Share price decline last year reflects this (-34.6%). Div payout ratio is still safe, though (57%).
American Homes 4 Rent $AMH, the single-family housing REIT, is showing impressive growth in Q2/25 - they also grew Core FFO per share 6.6% in 2024. Stock hasn't really moved since mid-2022. On my radar.