#PEEK: THE HIDDEN MATERIAL THAT COULD CHANGE THE FUTURE OF EV MOTORS
In its latest Q2 FY27 conference call, #KSHInternational discussed one interesting word: PEEK.
It may sound like just another chemical or plastic, but PEEK could become an important material as EV motor technology evolves.
So, what exactly is PEEK, and why should we pay attention?
WHAT IS PEEK?
PEEK (Polyether Ether Ketone) is a high-performance engineering plastic. Unlike ordinary plastics, it can withstand temperatures above 250°C, resist chemicals and hot oil, provide excellent electrical insulation and replace certain metal components.
It is used in aircraft components, oil and gas equipment, semiconductor manufacturing, medical implants, automotive components and increasingly advanced EV motor applications.
WHY IS THE EV INDUSTRY INTERESTED IN PEEK?
The way electric motors are being designed is changing.
EV manufacturers are moving towards 800V architectures, Silicon Carbide (SiC) inverters, flat copper hairpin windings and oil-cooled motors.
But these developments create a serious problem.
Higher voltage and faster switching create electrical spikes inside motors. These spikes can produce tiny sparks between neighbouring copper wires, gradually damaging their insulation. This phenomenon is called Partial Discharge.
If the insulation fails, the motor can eventually fail.
This is where PEEK becomes interesting.
HOW DOES PEEK SOLVE THIS PROBLEM?
Traditionally, copper wires are insulated using multiple thin coats of enamel. But every additional coating layer creates the possibility of tiny defects.
PEEK offers another approach.
Instead of applying multiple thin layers, manufacturers can extrude one thick, seamless PEEK sleeve around the copper wire.
This provides better resistance to electrical discharge, high temperatures and hot oil.
At 150 microns, PEEK insulation can achieve a Partial Discharge Inception Voltage (PDIV) of approximately 1,600–1,700 volts.
There is another important advantage.
PEEK-insulated hairpin wires can potentially improve copper slot fill by more than 10%. In simple terms, more copper can fit inside the same motor, potentially allowing higher power or a smaller motor.
WHERE IS THE REAL BUSINESS OPPORTUNITY?
Here is the interesting part.
The opportunity is not necessarily in manufacturing more PEEK plastic.
The real opportunity could be in manufacturing specialised PEEK-coated copper winding wires.
Why?
Because manufacturing these wires requires specialised extrusion technology, ultra-clean PEEK resin, precise coating thickness and strong bonding between copper and plastic.
More importantly, automobile manufacturers must test and approve these wires before using them in commercial vehicles.
These approvals create a significant entry barrier and can make customers difficult to replace.
WHERE DOES KSH INTERNATIONAL FIT IN?
In January 2026, #KSHInternational signed an exclusive India licensing agreement with Austria-based HPW Metallwerk to manufacture its patented PEEK-coated high-performance wires.
This gives KSH an entry into an advanced, higher-value segment of the winding-wire industry.
However, a technology licence is only the beginning. Actual commercial production, customer approvals, manufacturing yields and repeat orders will determine the opportunity.
THE BIGGER PICTURE
One important distinction: PEEK resin and PEEK-coated copper wire are two different markets.
Global PEEK capacity is expanding, particularly in China. Therefore, simply manufacturing PEEK resin may not guarantee pricing power.
The more interesting competitive advantages could sit downstream, where specialised manufacturing technology and OEM approvals matter.
EV motors are becoming more advanced. And as they do, the materials and components inside those motors are becoming increasingly important.
Sometimes, the next big opportunity in EVs is not the battery or the motor itself. It is the specialised material that allows the motor to perform better.
Companies with good fundamentals,theme and guidance
At least one of them should be in your PORTFOLIO 🔥🔥
Which one ??
1. TD Power
2. STL tech
3. Mtartech
4. Yash Highvoltage
5. RK Forge
6. Menon Bearings
7. Ather Energy
8. Sona BLW
#Multibagger
Diwali 2026 Stock Picks Are Doing Great!
Steamhouse India: +18% 🔥
Orient Cables: +16%
QPower: +15%
Tonbo Imaging: +11%
Strong performance from my Diwali picks so far! 💚
And this is just the beginning of the journey! 🚀
Disclaimer: Returns are calculated from my Diwali picks' reference prices. Not a buy/sell recommendation.
#Diwalipicks #Stockmarket #Stocks
TD Power - Extremely Strong Q2FY27 Concall! ⚡
Management has revised its FY27 REV guidance upwards to 2,900-3,000 Cr
For FY28, management has provided initial guidance of 3,400-3,500 Cr, explicitly indicating a very high likelihood of upward revision!
Coming to Margins, management believes 19% EBITDA margins are sustainable
Margins could remain around 19-20% in the near term, with some temporary pressure as the new facility incurs costs before meaningful REV contribution
However, once the new facility reaches 50-60% utilisation, management sees potential for EBITDA margins to exceed 20% again!
Management believes Company has the potential to become a $1 billion REV business
Made significant gains here, stock doubled even after the exit but has now corrected 25% from its ATH
Given the recent correction, we will be adding it back to our watchlist & looking for a better entry opportunity
Overall, an exceptionally encouraging concall! Solid Execution⚡
In this result season ,SMEs with strong H1 Numbers 💥
AFCOM
Flysbs
Kaka
Adisoft
Nanta
Msafe
Monolith
Yash High Voltage
Unified
Vpal
Tipco
SPEEDEX
Aimtron
Pooja Precision
The Data Center Buildout Is Not Dead
The Senate’s 73-25 vote to advance the Bipartisan American Affordability and Jobs Act undercuts the claim that rapid data center expansion is politically finished.
With White House support and President Trump publicly backing the measure as a way to unleash energy production and protect ratepayers, the bill both raises costs for operators and clears the largest practical obstacle to new capacity: the inability to build power and transmission on a workable timeline.
Under the legislation, large loads of roughly 20 megawatts or more must cover the full incremental cost of the generation, transmission, and distribution upgrades built to serve them. Ratepayers are shielded from cost shifting, and states gain additional tools to impose collateral or other requirements. Modeling suggests this could meaningfully increase the retail power price faced by data centers and add roughly 10 percent to the annualized cost of a gigawatt-scale facility. Those numbers are real, and some marginal projects will be repriced or delayed.
They are not fatal. The same bill shortens federal environmental reviews, limits the window for legal challenges, strengthens project certainty, and expands federal transmission siting authority after a defined state review period. The binding constraint on data center growth has not been the willingness of capital to fund servers; it has been the multi-year wait for reliable power. Faster permitting of generation and transmission addresses that bottleneck directly.
Higher power costs and clearer cost allocation will push some developers toward co-located generation or more selective site selection. That is an adjustment, not a shutdown. The combination of ratepayer protections, accelerated infrastructure deployment, and explicit Trump administration support is more likely to sustain the buildout than to end it. The political signal is that Washington is prepared to let the projects proceed, provided the incremental costs fall on the operators rather than on everyone else.
Asian Energy 🛢️
Q2FY27 Results and concall update
YOY numbers look excellent (Growth of more than 100%) but are not the right metric to compare as last year same quarter was depressed and hence, base was low.
On QOQ basis
Numbers are moderate.
👉🏼Sales is flat.
👉🏼EBITDA up by 42%
👉🏼PAT up by 30%.
Company is into oil & Gas, Mineral segment and different kind of projects are being executed in different quarters and hence, QOQ also there is variation.
Outlook:
1. Oilmax merger approved by NCLT.
2. After Merger equity will dilute and total shares will rise to 8.8 cr from the present 4.87 cr.
3. Within 3-4 years, target to reach 3000 cr sales and 700 cr EBITDA..
PAT would be around 400-420 cr in 3-4 years.
Hence, Expected EPS is around 45-48, which is 2.5-3x in a CAGR of more than 30% for the next 3-4 years.
Considering above current valuations of 25 looks reasonable.
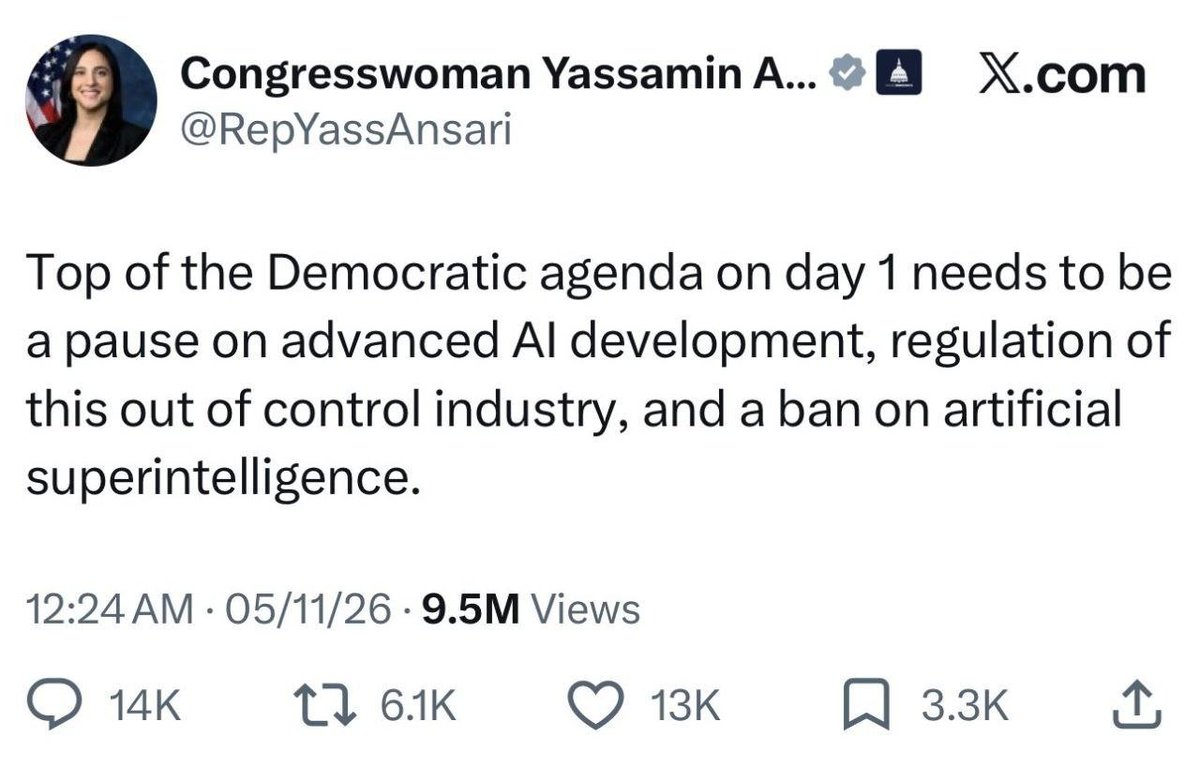
This lady seems to be a Donald Trump version of Democrats.
Such an extreme statement regarding AI which led to huge panic selling.
Can AI be banned❓
No Never
Once a new technology comes into picture, it goes forward , not backword.
TD POWER SYSTEMS
Be Bullish on India's Industrial Power Story.
Most investors associate TD Power Systems with the AI and data-centre boom.
But there is a much bigger story. It provides critical power-generation and motor solutions across multiple industries
Lets check below
Huge Rally in AI and tech stocks in US
Despite Nvidia being down 5%, Nasdaq 100 is up 2.7%
AI infra plays like Bloom Energy, Space X, Vertiv,GE Vernova, Corning etc. all up 8-14%
Expect sharp move in Ai and Infra stocks in India
🔥Diwali Picks for 2027 by Ginger Investor
Let's see how many give good returns from here on
These are not recommendation and I am not SEBI RA - So please do your research. Also I am not invested in all of these stocks, only few stocks . These stocks can give negative returns too, may become 2x - But these are my scanning list - DYOR
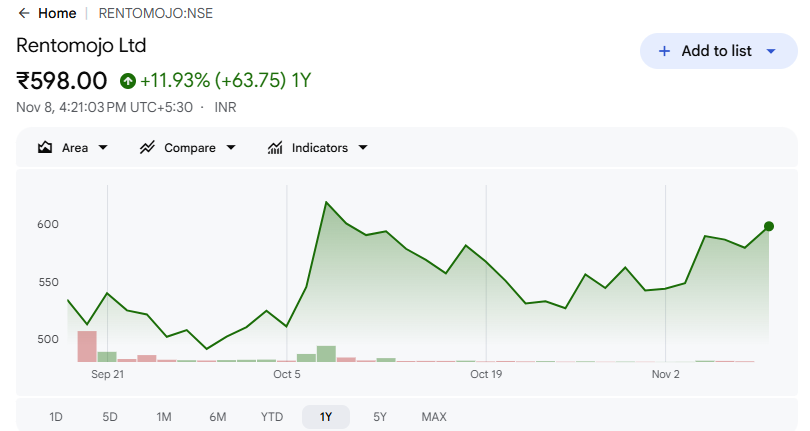
#1 - RENTO MOJO
Add in the range of 570-580
🪔 DIWALI PICK 4 🎇
⚡ TD POWER SYSTEMS LTD
NSE: TDPOWERSYS
BSE: 533553
💰 CMP: ₹576
🎯 TARGETS: ₹662 / ₹800 / ₹993+
⏳ Investment Duration: 1-2 Years
📊 FUNDAMENTAL SNAPSHOT
• Market Cap: ₹18,532 Cr
• P/E Ratio: 67.4x
• P/B Ratio: 16.8x
• ROE: 24.7%
• ROCE: 34.0%
• Operating Profit Margin: 18.0%
• EPS: ₹8.80
• Book Value: ₹34.30
• Debt: ₹18.1 Cr
• Debt-to-Equity: 0.02
• Cash Equivalents: ₹199 Cr
• Current Ratio: 1.95
• Promoter Holding: 26.5%
• Dividend Yield: 0.18%
• Profit Growth: 45.3%
• PEG Ratio: 1.89
• Industry P/E: 30.4x
📈 LATEST QUARTERLY PERFORMANCE – Q1 FY27
• Revenue: ₹640.05 Cr (+72.1% YoY)
• Operating Profit: ₹121.63 Cr (+76.7% YoY)
• Net Profit: ₹86.29 Cr (+72.3% YoY)
💡 INVESTMENT THESIS
TD Power Systems manufactures AC generators and electric motors for domestic and international markets.
The company is positioned to benefit from rising demand for power generation equipment, industrial electrification, renewable energy infrastructure and data centre power requirements.
Strong return ratios, low debt, healthy operating margins and robust earnings growth provide a positive long-term business outlook.
⚠️ KEY RISKS
High valuation compared with industry peers, customer concentration, execution challenges, working-capital requirements and fluctuations in raw material prices.
Our outlook remains positive on TD Power Systems over the 1–2 year investment horizon, subject to business performance, execution and valuation.
━━━━━━━━━━━━━━━━━━
📋 RESEARCH ANALYST DETAILS
Research Entity: StoxPlex Research
SEBI Registration No.: INH000024921
BSE Enlistment No.: 6957
🌐 Website: https://t.co/bUrbn3D1VP
━━━━━━━━━━━━━━━━━━
📢 DISCLOSURE & DISCLAIMER
Disclaimers: https://t.co/hiqvjDVbqs
Disclosures: https://t.co/Gsa5cV0gD6
Kindly do not invest more than 5% of portfolio in any stock
Investment in securities markets is subject to market risks. Read all related documents carefully before investing.
Registration granted by SEBI and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors.
My DIWALI 🪔 Stock Picks!
I'm preparing stock list using technical + fundamental analysis.
People who are interested can like and retweet for max reach.🙌🩷
I am Going to Share My Stocks Picks Tomorrow at 8pm on My Telegram Channel!👇
https://t.co/qFsO9yNCyG