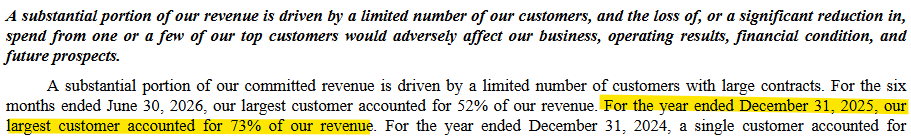@TMTLongShort Not sure I'm buying this idea that Instinct, Muse etc. will be free and just clip some portion of payment volumes.. Insane this kid is 23 though lmao
scoop: OpenAI sparked Hugging Face bids with early investment offer ahead of Nvidia’s $13 billion deal @CNBC
✔️Hugging Face saw a flurry of deal interest before Nvidia agreed to buy the open-source platform for roughly $13 billion.
✔️OpenAI offered to invest roughly $100 million in Hugging Face (after the ChatGPT creator’s agents hacked into the platform in July), according to sources.
✔️Hugging Face also attracted potential acquisition interest from AMD and Salesforce, sources said
https://t.co/a3ZkpO3VO8
I guess I see your point if you're saying the V in LTV is going down because risk-free yields are up. Still think you're over-complicating it a bit. AI infrastructure related spreads broadly have blown out. Oracle's spreads also wider too as widely discussed. Construction clearly not going great. In any event I suppose that's why you're the credit experts..
AMD HAS AGREED TO BUY FEI-FEI LI'S WORLD LABS AI STARTUP FOR $8.2 BLN TO ADVANCE THE FUTURE OF AI COMPUTING, WITH CEO LISA SU SAYING THE ACQUISITION WILL STRENGTHEN THE COMPANY'S HARDWARE ROADMAP AND THAT THE GOAL IS TO BUILD 'BETTER AI'
@ethanrkho Comps. Ilya raised at $32B for SSI, Mira Murat raised at $12B for Thinking Machines, etc. so can use those as benchmarks and adjust based on how good the founder is perceived to be.
There is no way I heard Gary Marcus just say that companies will "..use the Chinese models because at least (they) know what the rules are"..
In what world have these people been living in? The rules are clear in China..? My brain hurts.
I mean all else equal if there weren’t constraints around power generation, grid transmission capacity, labor, wafer capacity, etc. etc., there’d inevitably be more debt-financed data centers and chips.. Probably better for everyone involved over the longer-run if the build-out is financed with operating cash flows?
Has Satya gotten anything right in AI other than the OpenAI investment? And even there, could argue the one-foot-in, one-foot-out nature of Microsoft’s relationship with OpenAI is why they find themselves in such a poor position relative to where they started in 2022/2023..
The FT in a rare piece of good reporting pointing out that 73% of Nscale's 2025 revenue was from.. ByteDance. Pretty egregious that this wasn't disclosed in the S-1.
Just about through this Nscale $NSCL S-1 and man.. the only bull-cases I can come up with are that Jensen seems to like them a lot and they have a lot of big names on their board..
Amusing how every new neocloud is a self-described "vertically-integrated" operator.. Acquiring land, configuring BTM generation, securing grid connections, and building the powered shells supposedly results in a real "competitive advantage".. "Speed" and "lower costs" are often cited as the reason to self-build rather than lease data center capacity.
Yet only Oracle and CoreWeave have achieved 1GW+ of operating capacity and $10B+ of "ARR".. And both lease virtually all of their data center capacity. It's almost as if making the capital-and-operationally intensive cloud business even more capital-and-operationally intensive by self-building data centers might not be all that optimal..
$ORCL $CRWV