Not selling anything.
Not investment advice.
Personal but public journal.
Arguing with you to spare my family.
DM mutual to unblock.
Canadian Propaganda
Evergreen has the worst case of confirmation bias I have ever seen on this app. The guys monkey brain is celebrating Zuck changing the shareholder contract and seperating voting control from economic interest. True Retard: Blocked.
Who cares?
Companies raise money to attack infinite TAMs at returns > coe
It’s cool when spcx / ant / oai / private markets do it but not scaled public company with more right to win
oh noooooooo not dilution
smh gtfo
dilute me pls papa @finkd
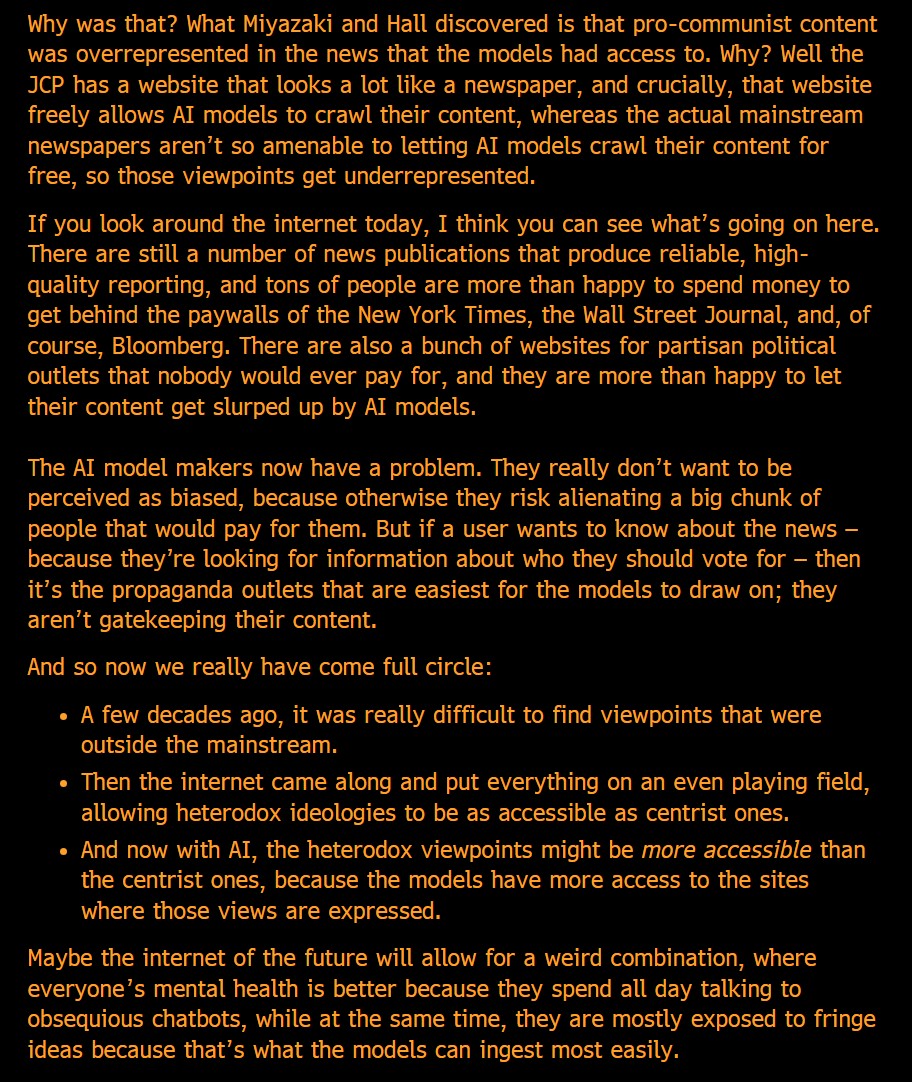
Some centrists fantasize that because all LLMs have the ideology of Ezra Klein, that we may be on the doorstep of a great political moderation.
I wrote about a fascinating paper from @ahall_research and Sho Miyazaki that, to my mind, opens the door to a very different outcome.
@QuahogCapital Ya he's absolutely wrong and has zero ability to analyze a business. There is a difference between being long term and just being an idiot. He's the later.
$META could finance $220B in CapEx in 2027 without needing to go for external financing (which is 50% more than they will spend this year on CapEx).
$META generated $133B in operating cash flow in the LTM. Next year, with modest revenue growth, they will probably be at the $140B-$150B mark (even with the $10B litigation charge). If they cut their Reality Labs spend, which is still $15-$20B per year, they get could get another $10B, which gets them to $160B. They also have $80B in cash on the balance sheet. Even if they leave $20B of cash and spend $60B in 2027, only $2.75B of debt matures, so their total spend can go up to $220B of CapEx spend.
In April 2026, they also raised $25B in bond issuances. If they did the same in 2027 (which I don't think the market would freak out about), that would get them to $245B in CapEx.
Either way you slice it, if it is $220B or $245B, they would have bought more compute than any frontier lab in 2027, and they would still secure their position in this AI infra race.
Given market conditions, if $META really believes they have to push the pedal this hard on CapEx to be in a strong long-term position, they should first clean house (especially in their RL spend) and look at other options before diluting shareholders at these valuations levels.