@hugodevere@macrocephalopod Level regressions assume stationarity, meaning the mean, variance, and autocorrelation of the variables remain constant over time. If the variables are non-stationary (e.g., have trends or unit roots), using a level regression can lead to unreliable results.
@BurnsideWasTosh They're 50 people with one Bloomberg terminal. If you want accurate forecasts you have to hire good people and give them the resources they need: https://t.co/oWY0s3bVhb
This video covering the 1990s boom is instructive. Not least crowding around one stock, Iomega, by retail. Plus the go-go managers of the day. Worth watching for an insight into market cycles IMO. Includes Cramer. Betting on the Market (1997): https://t.co/AIgnMriTbk
It’s an old observation that we have Anglo-Saxon words for livestock (cow, sheep) and Latin/French-derived words for the higher-status business of eating them (beef, mutton). Same thing shows up in finance: retail trades stocks and bonds, institutions do equities or credit.
📢 NEW PAPER OUT! 🚀
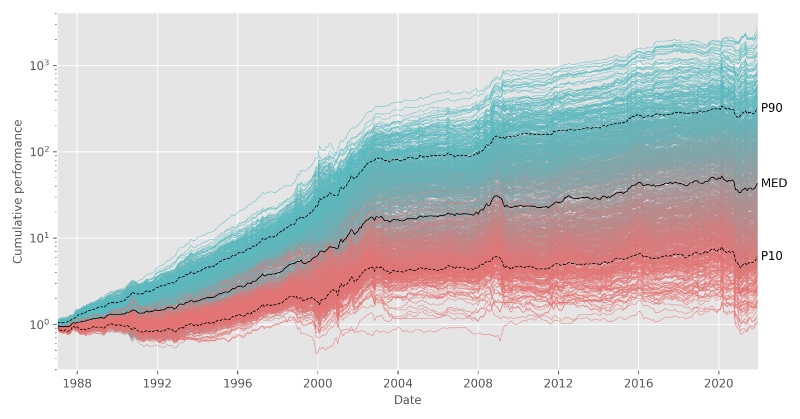
We analyze 1,056 #ML models to uncover how key design choices—algorithm, target, feature, & training—affect strategy returns.
Key takeaways:
📈 Returns vary widely; see graph below!
🔍 NSE exceed SE by 59%
💡Check out which ML design choices really work 👇