$NBIS Expected 2027 ARR guidance - $25.4B
I have been quite absent this week, but I've seen many people assuring everyone that we will see $30B, or even $40B, in 2027 exit ARR. However, this number is something that the street won’t expect unless we get such massive guidance from management during November earnings, which I don’t expect.
People know my expected 2027 ARR numbers ($35B - base case), but I haven’t discussed what I expect management to guide. So let me clarify:
1) Current ARR guidance is $7B-$9B in ARR by the end of 2026. Based on Vineland being on schedule and recent price increases, I believe that management will be confident that they will reach the upper bound of the guidance, but when constructing next year's guidance, they will remain conservative and use the midpoint of $8B (in my opinion).
2) How much active power comes online in 2027? I think this is where most people are way too bullish, and Nebius will be conservative here. They currently have around 800MW confirmed, but everything points towards at least 1GW. However, with the current skepticism around debt/capital issues and markets being scared, I don’t expect Nebius to guide above what was confirmed until today. They will rather surprise us during 2027 than put themselves under pressure with optimistic outlooks.
3) What will be the actual revenue per MW for these 800MW?
Again, I see so many bad takes here on X. People completely misunderstand the strategy that Nebius wants to go for and how the capacity is expected to be monetized. First of all, 200MW out of these 800MW will go to $META, and this is contracted at around $12M/MW. The remaining 600MW will be used for the AI cloud business and short-term deals.
What is the floor? Well, management told us many times that they could sell this capacity for $20M-$25M/MW today, which will likely be the floor. I don’t expect Nebius to go above this price because it is simply not confirmed yet, and they tend to really sandbag their guidance. Everything suggests that they very well could, as there are two catalysts: Vera Rubin capacity coming online (~$50M/MW) + short-term deals (~$40M-$50M/MW), but I expect them to stay around $25M/MW for additional 2027 capacity.
If you put these numbers together, you get:
- $8B from 2026 ARR
- $12M x 200MW = $2.4B ($META capacity)
- $25M x 600MW = $15B (remaining 2027 capacity)
That sums up to $25.4B, which I expect to be the starting point of their guidance, and they will give us a certain range. In my opinion, the range will be created around a -10%, +10% stress test (Nebius will do a detailed stress test based on their own internal assumptions that we don’t know, but usually the starting point is some hardcoded percentage discrepancy), which will give us the EOY27 ARR guidance of roughly: $23B - $28B
I know that this number might not be impressive to most of you because you’ve been reading about $40B ARR in 2027 the whole week, but you have to remember two things:
1) Nebius underpromises and overdelivers
2) It is still $7B - $12B above consensus
I am extremely excited for the earnings because the street is behind on Nebius, and they put it in the wrong basket together with all the other neoclouds. I actually agree with the narrative that it is a terrible business for most, and 80% of them will fail. So, be invested in those 20% because they will capture the whole market along with other hyperscalers as the buildout matures.
Give me your best cases 🚨
I’m looking to invest in the battery and energy storage sector for the next 10–15 years.
Which companies should I be looking at?
A big reason I own $NBIS is that they have taken an industry relatively tied to bare metal and changed it from top to bottom. They are optimizing how efficiently it can utilized the core product, inference.
This acquisition is entirely in line with that.
🚨 JUST IN:
$NBIS has acquired Inferize, an AI inference optimization startup, to strengthen its Token Factory production inference stack.
Inferize’s technology is designed to reduce model “cold starts”, the time it takes for AI models to load before they can begin serving requests. That can leave GPUs sitting idle during demand spikes, new instance launches, or model updates.
By integrating Inferize’s technology and engineering team into Token Factory, Nebius says it aims to improve GPU utilization, make capacity more elastic, reduce inference costs, and serve more customer demand from the same infrastructure.
$NBIS ACQUIRES INFERIZE TO STRENGTHEN ITS INFERENCE PLATFORM
Inferize’s technology reduces the time AI models need to load before serving requests, cutting idle GPU time and helping capacity scale with actual demand.
For Nebius Token Factory, that means higher GPU utilization and better token economics.
Inferize’s CEO summed up the objective: “serving more customer demand from every GPU.”
Following Eigen AI and the addition of Clarifai’s core team, Nebius continues building out its inference stack. More capacity matters. Getting more out of that capacity matters too.
What $META announced last night is what I would've expected from $AAPL if Steve Jobs was still around
"Hardware" company product:
- 600–650 grams weight
- $3,499 USD
"Social media" company product:
- 100 grams
- $1299 USD
Being FOUNDER LED is a HUGE Moat.
Few.
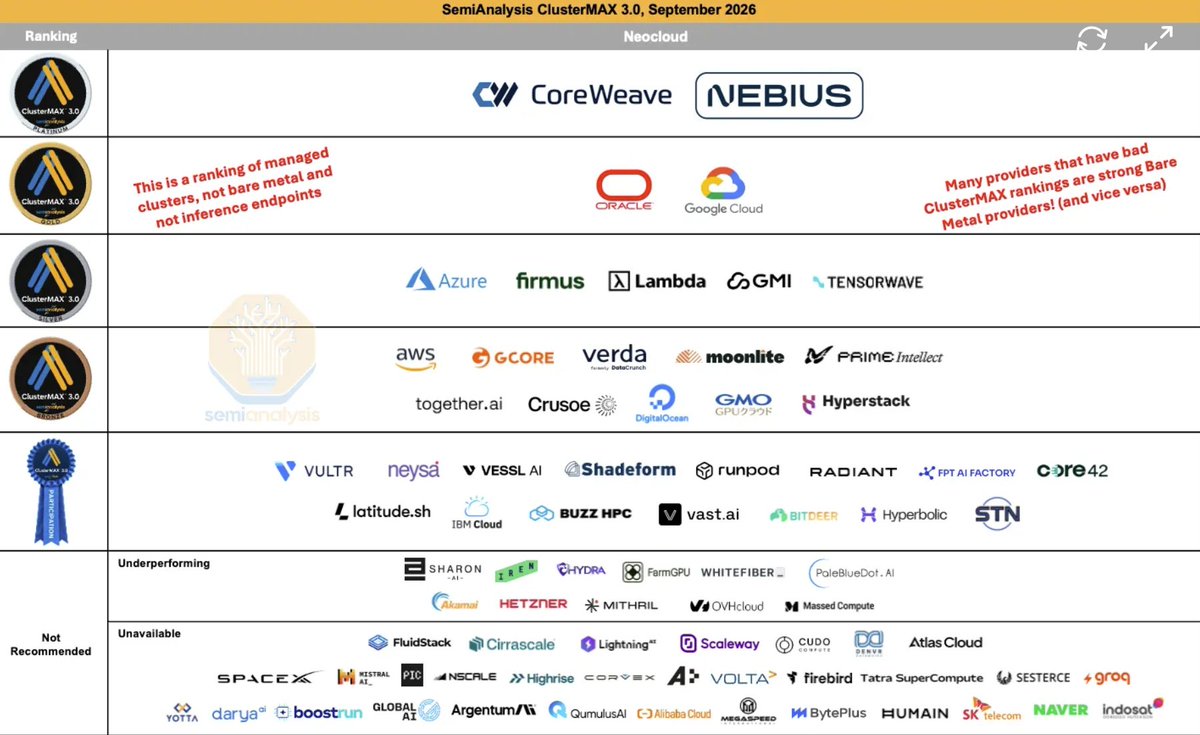
🟢 $NBIS is ranked as top tier platinum provider in SemiAnalysis ClusterMAX 3.0 alongside $CRWV
👉ClusterMAX is an industry-standard benchmark among providers, companies literally give free access to GPU clusters for testing because this is the highest regarded independent test that even influences customer decisions.
Important to note though, that this test is specifically for managed-clusters and not for bare-metal or inference end-points but it's still a very important one.
Also, to clarify, this is not rigged, it's not pay to win, it's non of that BS that you can read now on X.
The only reason you can read all those BS is because $IREN holders have to cope again with the fact that $IREN is not a recommended provider once again. In fact, their site is categorized as the worst in the industry.
The sad thing about this is that it's not surprising. $IREN wasn't even a NeoCloud by definition. I remember when Nebius' management tried to call them out about a year ago for calling themselves something they aren't.
Even Semianalysis says
"We recommend that IREN stop pretending to offer managed clusters and inference endpoints in public marketing and investment materials, and focus on their bare metal offerings, where there is plenty of market demand for their services."
The imagination that $IREN will be a cloud provider for enterprises and will rival others' software stack just because they bought Mirantis was always just a hallucination made up by X accounts.
It doesn't mean though $IREN can't be a good investment. Their new sites are getting better. Their assets *could* worth a lot and the stock *could* be cheap. But.
I just want my followers/readers to understand that the hype BS you constantly read on X is exactly as misleading as the company's own communication. When the company tries to appear better than it is and then you have the retail hypers on top of that you get a massively made-up picture about the company.
IREN is a baremetal provider. Not a company that has anything to do with Nebius and their 50m+ / MW deals.
Customers pay this much for high-level software layers and easy-of-use. Exactly what Iren called a commodity not that long ago.
100MW active power for Nebius is not the same as 100MW for IREN. But that could have been extrapolated when both of them got the $MSFT baremetal deal and even the baremetal deal was significantly inferior for Iren.
Not by coincident. It was exactly for the issues semianalysis highlight "Multi-day power outages, network upgrades, storage failures, air quality controls (issues)"
There is engineering quality differences between the datacenters and let alone the software stack on top of that.
Let alone inference, agentic workloads, token factory and open-source model serving that could be the cherry on top for Nebius according to Semianalysis who modeled around 100M / MW in that use case.
Don't get fooled by people who say the valuation difference is not justified between the companies. It is justified. It is exactly justified.
And honestly the most shocking thing is that a lot of them are completely dismissing this report and saying this doesn't change their thesis. I mean, this report is literally the thing you shouldn't dismiss.
This is a prime example of getting married to a stock with a false thesis. Huge issue for investing. Never let that happen.
I will admit I was wrong about $NBIS and sell my shares when multiple alarming signs and redflags will appear. It's not a shame to do so. I am not married to the stock, I am married to my financial life. If IREN jumped to gold tier and Nebius stayed at gold tier I would have seriously started questioning my own beliefs. Maybe something $IREN investors should also try once in a while.
$NBIS
Even if frontier models are temporarily constrained, the compute still gets built. You don’t stop preparing for the next generation just because you pace its release.
And for the models that exist, inference and deployment will require enormous amounts of compute anyway.
The AI thesis is still intact, the demand is increasing each day and the development of more complex compute demanding applications are not slowing down.
The AI Singularity
The argument goes like this:
1. Humans build an AGI.
2. The AGI becomes good at AI research.
3. It designs a smarter AI.
4. That smarter AI designs an even smarter AI.
5. The cycle repeats faster and faster.
Looking at the results and capabilities from the various labs over the past few weeks I would say we are firmly in this loop now.
The next 18months will be wild.
Recursive self improvement will dramatically increase capability very quickly from here.
Marginal costs of all models will go to ~$0.
Big news in Big D!
Following 100,000+ autonomous rides on @Uber, we’ve expanded our Dallas robotaxi area to 31 square miles, more than tripling in size since launch.
Catch a ride in the Uber app today!
Don't get too stuck on share prices on companies that are serial dilutors.
Take $IREN for example. Last time it traded at $35, it was worth under $10B. Today, at the same $35, it's worth around $13.8B.
Shares outstanding went from 283M (EOY 2025) to 394M (Now, per 10-K Annual Report). That's why dilution matters.
I'm not saying the dilution was bad or unnecessary. The point is that "it's back to $35, so it's cheap" doesn't mean much without looking at the market cap.
Same share price but a very different valuation.