That BNB concentration is a useful correction. We don't track cNGN yet on https://t.co/9eB3WsekkG among the 44 tokens we cover, so our naira figures understate the market. The naira token we do track, NGNC on Stellar, is still tiny in value despite thousands of transfers. Happy to compare notes
@0xjrey@stable_summit Good luck at Stable Summit. On the sterling side, the only GBP denominated stable we track on Solosolver track so far is GBPA on @arc blockchain ~$1.03M over 30 days. Still early, so the useful question is how much of that becomes GBP pairs rather than sterling-only transfers
The non-USD side of that showdown is less lopsided than it looks. Among the tokens we track on Solosolver, the AUD book on Polygon moved ~$105M on Nov 3–9, and has stayed in a ~$100–110M weekly range since late July. Curious if euro and Aussie rails will also be on the card in Singapore
Onchain FX on Arc needs local-currency inventory, not just dollar books. EURC on Arc, one of the chains Solosolver tracks, moved ~$102M in transfers on Nov 3–9. MXNB and GBPA sit on the same chain, but much smaller comparing with euro pegged stable. The test is whether Aave can turn that into pairs
@coincamps The EURC settlement leg already has flow. Across Solana, Arc and Stellar blockchains. The question for CPN is how much of that becomes institution-to-institution settlement.
@ErhanKOfficial The EURAU line is the one I'd watch. Among the euro tokens our platform tracks, EURC on Stellar moved ~$67M over 87k transfers on Nov 3–9, while EURAU on the same chain did ~$3K across 4 transfers. Custody is ahead of circulation. Coverage is partial
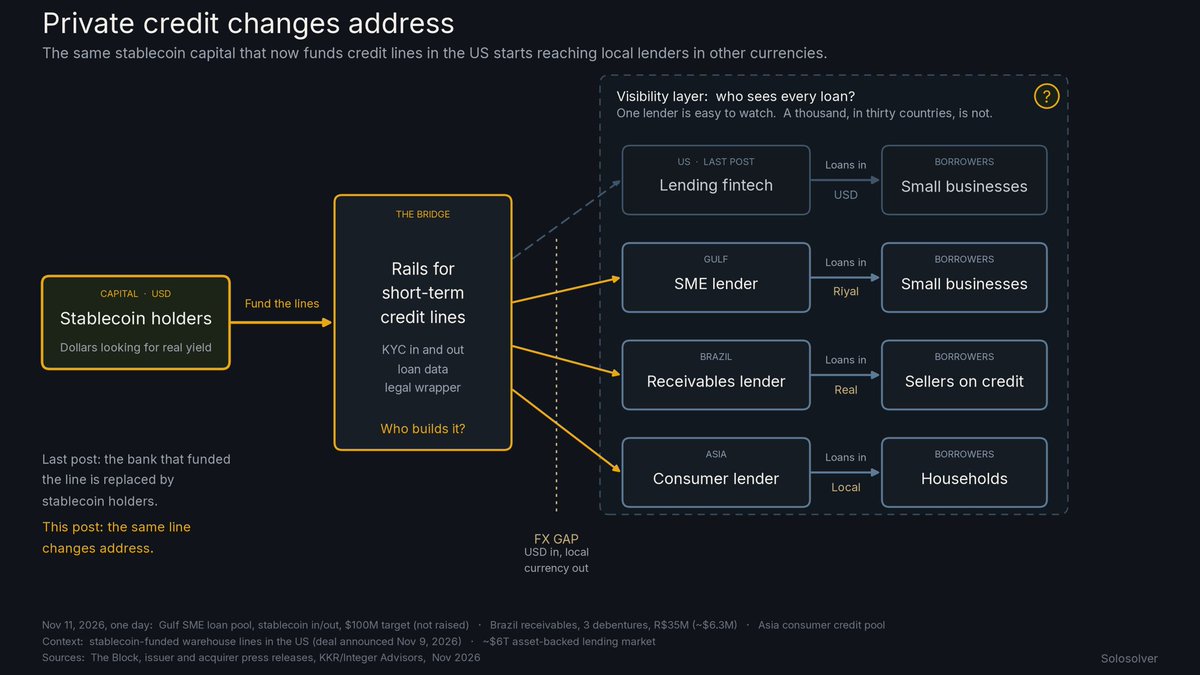
Two days ago I wrote that @Securitize buying @RiverOneHQ moves stablecoins to the start of the credit chain: the short-term line a lender draws on, the part a bank used to fund.
On November 11 the same idea showed up far from New York, three times in one day.
A pool of loans to Saudi small businesses opened on BNB Chain, with stablecoins in and out, KYC at both doors and a $100M target. Brazilian receivables, money buyers still owe to sellers, came onchain as three debentures worth R$35M under the local securities regulator. And a consumer credit vault for emerging markets opened in Asia
Private credit doesn't disappear. It changes address.
For the first time, a local lender meets capital that simply couldn't reach it before. Not a trend called RWA. A road that didn't exist.
But the road has two potholes the US version doesn't. The capital is in dollars, the loans are in riyals and reais. Someone carries that gap. And the question from last time gets louder: when there are a thousand lenders in thirty countries, who sees every loan?
The question is no longer whether credit gets tokenized. It's who builds the bridge between thousands of local lenders and the stablecoin dollar, and makes it visible end to end.
That bridge will not be the last layer. Just the next one.
#PrivateCredit #Stablecoins #RWA #EmergingMarkets #Onchain
@RobertoBalbinoX Agree, the cap chart misleads. Same outside the dollar - the non-USD stablecoins I track moved ~$6.8B in 30 days, and nearly half was one token, A7A5, a ruble stablecoin under sanctions. Activity and concentration say more than supply
@harshamv Good roundup.
A non-USD angle from our data across the non-usd denominated stables which we track shows that BRL stablecoins moved ~$115M on Nov 3–9 vs ~$87M the week before, while tracked MXN tokens are still near zero. The BRL leg is where local-currency volume shows up first
@Securitize, the platform behind @BlackRock's tokenized funds, is buying @RiverOneHQ.
Why it matter in my eyes -
When a fintech lends to small businesses, it doesn't use its own money. It borrows from a bank on a short-term credit line, makes the loans, bundles them, sells the bundle, and repays the bank. River One wants stablecoin holders to provide that line instead of the bank.
Until now, stablecoins mostly bought finished products: like a token of a fund that already holds loans. This moves them to the start of the chain, where credit is actually created.
The gap is reak. Of the ~$30B in "tokenized private credit", 90% are home loans recorded on a blockchain. Stablecoin capital actually funding credit is ~$5.8B. The market for asset-backed lending is estimated at ~$6T.
The open question is control. Because a bank sees every loan and can shut the line when something goes wrong. Of the bank is removed, then visibility has to be rebuilt as data anyone can check.
That's the real work ahead. Not another token, but credit a user can see
#Stablecoins #PrivateCredit #RWA
@HookedExchange GYEN is a good case of issuance without adoption. On Stellar chain it still logged ~15K transfers in October as we track it the data. But total value was around $1K
@TBariach@trondao USDT on Tron is not under control of Tether, they cannot freeze it there. On a smart contract level there is no opputunity to make it, the logic is hard and cannot be change. That's why people prefer to use it inspite of a huge fee even for a small transaction amount
@candowa_au Absolutely right, distribution decides a lot of tasks
On Stellar, the only AUDD chain our platform tracks so far, October transfer volume was ~$17M over 36K transfers, about half of September
That Tron gap shows in platform data too. The only non-USD stablecoin we track on Tron is A7A5, the ruble pegged stablecoin, which is under sanctions
Indeed, a compliant local-currency liquidity sits elsewhere, so routing USDT0 into cNGN pairs is a practical fix. How deep is the cNGN book today?
@joinrepublic Access is the right question, and the next is settlment. We track Solana non-USD stablecoins, EURC made $1.7B transfers there in October. Private credit priced and repaid in euros on the same chain is a short step
@io_enthusiast@StartaleGroup Yield and settlement on one rail is the right direction for japanese yen. The gap is usage, as JPYC on Polygon did ~$44K across 910 transfers in October in the tracked by our platform data, and Coinbase is winding down GYEN
@industryspread The 30% unremunerated floor is the real design choice, as it caps float income and pushes issuers toward payments volume. For scale, the GBP denominated stablecoin we track on Arc blockchain moved ~$1.25M in October. Long way to go before a £40bn cap matters
@AfricaWeb3_Inst@gftn_official@AIRinnovate I'd ask how the ₦10bn bar treats issuers already live. On Stellar blockchain NGNC logged ~7,100 transfers in October but only about $2K in value in the tracked data. The capital rules will decide if that turns into real flow or stays a pilot
@Pankujasrotia11 The licensing filter point is the strongest part. Supply lagged, but usage didn't, The euro pegged stablecoins we track moved ~$2.4B onchain in October, mostly EURC on Solana. Small float, high turnover. Our coverage is partial, but the euro looks used, just not hoarded
@CharmanderX81 BRL is the interesting test case right now. BRLA supply went from about R$209M to R$316M between Nov 6 and Nov 9 per DefiLlama, roughly 95% of it on Celo. The rails exist, the open question is where the two-sided flow comes from