A SWE in Charlotte told me they had a few interviews go south.
It surprised me because they had a really good resume.
Here's how I told them to diagnose where it might be going wrong:
Go back through every process from the last four months and write down where each one ended.
- If it ends at the phone screen, your positioning or your story needs work.
- If it ends at the technical, you were either underprepared, not technical enough, or didn't talk through your solution.
- If it ends at the panel, you're either interviewing above your depth or explaining your work below it.
- If it ends at the behavioral, your stories aren't landing. You're telling them what you did without showing why it mattered.
- If it ends at the manager round, they liked your resume but didn't connect with you in the room.
- If it ends after the final round with "we went another direction," you were often the second choice. That still has a cause, like weaker stories, a weaker close, the wrong level, the wrong answer on pay, or another candidate who showed more urgency.
If they go quiet after a strong final round, that's often the company's timeline, not a verdict on you. Follow up once, mark it as "no response," and keep moving.
Things hiring managers say after the interview that mean no:
• We’ll keep you in mind for future roles
• The team really enjoyed meeting you
• We’re still talking to a few more people
• You were a strong candidate
• We’ll be in touch soon
📍🟡 “Kalau pergi interview kerja, kami orang pertama yang kena reject.”
Firdaus, Pengasas Pertubuhan Kebajikan Pesakit Ichthyosis Malaysia (PEKIM) menceritakan pengalamannya sebagai seorang penghidap iktiosis:
• Perbezaan antara iktiosis dan psoriasis
• Diskriminasi yang dihadapi daripada masyarakat
• Kos yang perlu ditanggung
• Harapan untuk pengidap lain
Video penuh ⬇️
27 simple (and surprising) lessons for living a Rich Life
1. Stop agonizing about the amount you spend on coffee. Focus on the $30,000 questions, not the $30 questions — things like your savings rate, investment rate, debt payoff plan, and housing costs.
2. I can fix a lot of problems with money, but I can't fix cheap. If your friends or family have ever joked about you being cheap — even though you prefer "I'm selective" — good luck.
3. The way you feel about money is highly uncorrelated with the amount in your bank account. If you believe that when you have $50K or $500K more, you'll finally feel better about money, you won't.
4. Quick back-of-the-napkin rules I use:
- True price of a hotel: Take the price and add 50%, which covers tax + tips + incidentals.
- True price of housing: I personally add 50% to a mortgage to account for Phantom Costs (transaction fees/maintenance), though most people will pay less — I'd use 30% for most. Definitely run a calculation for this one.
- How much to spend on housing: Total housing cost should be less than 28% of gross income, though these days you'll likely stretch to 32% or even 34%. Higher than that, you're in financial risk.
- Car payment: 2.5x the payment for true out-of-pocket cost. It might even be more — my $350/month car payment was over $1,000/month once I factored in everything — but 2.5x is the sweet spot.
- Home renovations: Take your first budget and double it — and grizzled renovators say even that's light.
- Eating out: Triple it. Couples tell me they eat out 5x/week; the real answer is 15x (breakfast, lunch, dinner, coffee, everything).
5. If you're paying your financial advisor 1% in fees, you'll pay approximately 28% of lifetime returns in fees. Most people can manage their own money, but if you need help, get an advisor — just never pay a percentage-based (AUM) fee.
6. Renting can be a better financial decision than buying. Sometimes buying wins. You must run the numbers, starting with a buy-vs-rent calculation. I've made much more money renting for 20+ years — and lived in better places with almost zero maintenance. RUN THE NUMBERS.
7. What's your Rich Life? You should be able to answer with incredibly specific answers. "Financial freedom" is just words. "So I can do what I want, when I want" is embarrassingly vague. In my early 20s, my Rich Life was taking a taxi in the August NYC heat so I didn't have to sweat before a meeting. Then it was affording appetizers (because as a kid, we couldn't). THAT is specific.
8. You cannot live a Rich Life if you hate spending money. Learn to feel JOY spending, tipping generously, and paying your taxes. As Dan Kennedy says, "Why pay less when I can pay more?" (For the important things in life.)
9. There's a limit to how much you can cut, but no limit to how much you can earn. Learn to negotiate your salary (a single negotiation in your 20s, properly invested, can be worth hundreds of thousands). Start a side business. Yes, even for public school teachers.
10. Yes, you can get paid more. Earning is a skill. Whenever I post salaries, a LOT of people refuse to believe they're real. Step 1: recognize there are many highly paid jobs out there. Step 2: study those people's backgrounds (free on LinkedIn). Step 3: build similar skills (informational interviews are a great approach).
11. Increase your investment rate by 1% every December (e.g., from 6% to 7%). This single decision will be worth hundreds of thousands of dollars — more than all the coffee and vacations you ever take, combined.
12. Insurance is insurance, not an investment. If you follow someone telling you their insurance is a great way to make money, you're following a scammer.
13. Get the Big Wins right and the small stuff takes care of itself. There are about five: learn the basics of money, invest early and automatically, land a great well-paid job, secure stable housing, and invest in positive relationships. Nail those and you'll never spend 25 years agonizing over the price of coffee.
14. Two keys to a Rich Life: (1) Know your numbers — net worth, Fixed Costs (50-60% of take-home), Savings rate, Investment rate, and Guilt-Free Spending. Get my free CSP template to figure these out in 10 minutes. (2) Master your money psychology.
15. Fight for simplicity in your finances: 1-2 credit cards, 1 savings account, 1 checking account, and (depending on your needs) simple investments like a target-date fund. Then get on with your life.
16. If you have debt, make a payoff plan so you know the exact month/year you'll be debt free. 90% of people in debt don't know how much they owe, and 95% have never made a payoff plan. People in debt do everything EXCEPT pay it off — jumping between 0% cards, consolidating, running gimmicks. Make a plan and automate it.
17. Create a Worry-Free Number, below which you simply won't worry. You wouldn't stress over the price of a pack of gum. Start at $20 and revisit once a year. Your number may eventually reach hundreds or thousands. Good — adjust over time. If you're in a relationship, do this together.
18. If you have money but constantly feel anxious, add an extra $5,000 or $10,000 to your checking account.
19. To save money, pick your 3 biggest discretionary expenses and cut 50% within 6 months. That frees up hundreds a month. Trying to cut 5% on everything guarantees failure and makes you miserable.
20. Most people have the same vacation budget in mind: $5,000 — regardless of age, kids, or trip length. It's a number they picked up in their early 20s and it stuck, the same way you can spot older men by the hem of their pants. Adjust with the times and your ability.
21. You can live a Rich Life today AND a richer life tomorrow. Yes, even if you're in debt, even if you're not perfect, even if you regret decisions from years ago. Do not put yourself in purgatory.
22. There should never be "a money person" in the relationship. Both people must be engaged. One of you might focus on investing, another on certain bills — but both partners need to own a number and share it. Use the monthly money meeting agenda from my book, Money For Couples.
23. Build generosity in NOW — don't wait until you're "rich." Pick up the check. Tip big. Set an amount you want to give away every year and automate it. Wait for some magic number and you'll never build the muscle. The highest level of personal finance is always about the WHO: who do I get to surprise, delight, and be generous to?
24. Teach your kids about money young. Most people tell me their parents either never talked about money or only said "We can't afford it" — and now they do the SAME thing to their own kids. Money isn't something to protect kids from. Get them excited, teach tradeoffs, and by their teens they should be handling tax/tips at dinner and helping plan a family trip or car purchase. But first: you have to master it yourself.
25. Every December, do a Rich Life Review — solo or, in a relationship, together. Share your 20 most memorable photos of the year. Talk about what you want MORE and LESS of. Create a theme (one year ours was A Year of Beauty, another A Year of Adventure). THEN — and only then — look at your numbers. This should take days. Don't rush it.
26. A Rich Life is lived outside the spreadsheet. There's a subset of people — Optimizers, usually men — who spend thousands of hours reading financial subreddits and running Monte Carlo analyses.
27. Stop using the excuse "I wish they taught this in school." Many schools did — you didn't care. And there's unlimited free content and great books now. Get my book, I Will Teach You To Be Rich, from any public library.
Follow me, @ramit, for more on money psychology
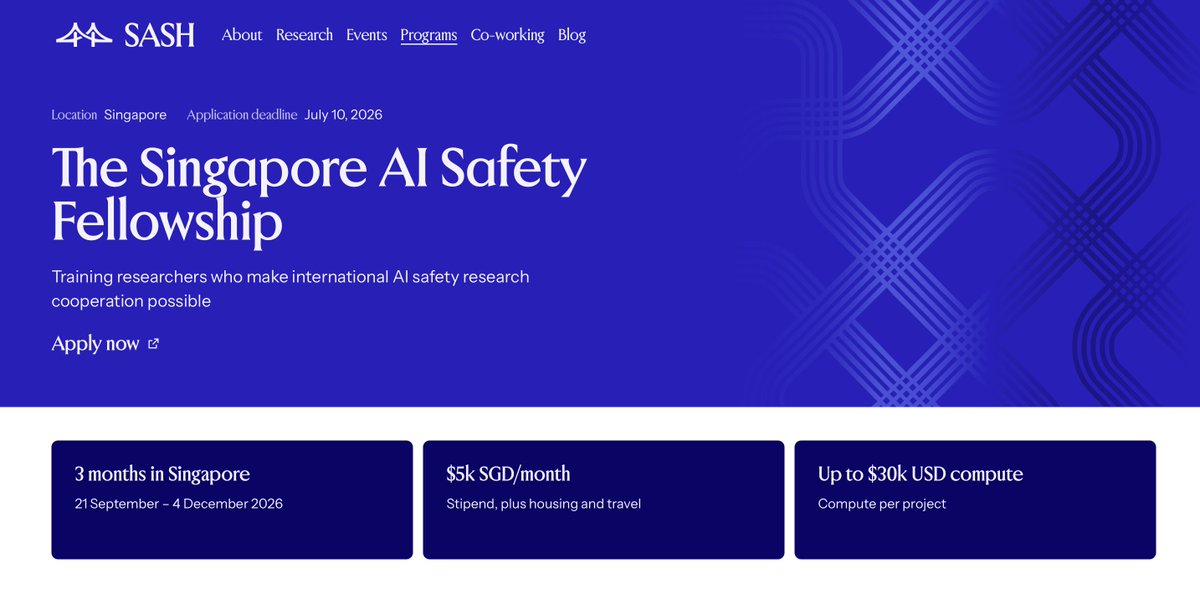
Calling all Malaysians in the AI space! The Singapore AI Fellowship just launched 🇸🇬
3-month FT research fellowship in SG focused on technical AI safety & governance research. Fully funded with $5k SGD/month stipend, up to $30k USD per project, etc.
📍https://t.co/JWefsqRCo9
Singapore’s Foreign Minister, Dr Balakrishnan casually explaining how he built his own AI agent (a 2nd brain for diplomacy) using Claude & WhatsApp integration etc. on a Raspberry Pi
“You cannot govern a technology you have only been briefed on.” 🇸🇬
I’ve noticed the happiest women in marriages are the ones who fundamentally do not idolize or center men. They don’t see marriage as an achievement or a man as the source of their worth. They had a full sense of self, purpose, and identity before the relationship, and they kept it after.
Recruiters aren't using the LinkedIn you're using.
We're on a $12K/year product called LinkedIn Recruiter.
It resembles more of an ATS/Job Board than a social media feed.
We type keywords, scan results, and the first that pops up is your headline.
Here's how to fix yours:
Title | Skills | Value Prop
This keeps it makes it easy to identify what you do as we scroll through 100s of candidates to "stop the scroll" and click your profile.
https://t.co/DyD0zNS0KC
🗞 MALAY MAIL: MyDigital, Oracle team up to train 300,000 Malaysians in AI by 2029
🌐 MyDigital Corporation will collaborate with Oracle to train 300,000 Malaysians in artificial intelligence (AI) to enhance employability and support career growth by 2029.
💪🏼 Digital Minister Gobind Singh Deo said the 300,000 Malaysians, comprising students and professionals, will be equipped with AI skills through free skills and technology training, with globally recognised certification.
“I have launched the Oracle Skills Development Initiative (SDI), a collaboration between Oracle and MyDigital Corporation, at Oracle AI Experience Live 2026.
“This initiative will enhance employability and support career development,” he said.
He added that the training will encompass technologies such as Oracle Cloud Infrastructure (OCI), OCI Generative AI, OCI Data Science, Oracle APEX, OCI DevOps and OCI Security.
“The programme is accessible free of charge via Oracle MyLearn, a comprehensive training and empowerment platform by Oracle University.
“Talent development and empowerment are crucial for us to collectively achieve Malaysia’s goal of achieving AI nation status by 2030."
https://t.co/2xZPbf9xGc
#AINation
#Training
#MalaysiaMADANI
Oracle just laid off up to 30,000 people with a 6am email.
We're now closing in on 100k tech layoffs in 2026 and it's only April.
The stock market is near all time highs, and most of these companies are posting record revenue.
They're not struggling, they simply just don't need you anymore.
This doesn't mean give up on work. You obviously need to work hard to put a roof over your head and to live a good life. But it means setting your expectations accordingly.
For most of you reading this, your work should not be your life. It should be a tool to get you where you want to go, not your entire identity.
I was the #1 recruiter at my last company for years. The definition of a company man. I was still laid off last year along with a ton of other US based recruiters and sales reps due to "offshoring and AI".
Everyone realizes this eventually. The only question is whether you realize it today or 40 years from now when you wasted your life on a few companies or a whole industry that gives two shi*ts about you.
So here's the mindset: your company is a tool.
Try hard. Make money. But understand it can all go away tomorrow.
Build your golden parachute. In this market, you should have at least a few months of cash to cover bills while you job search, plus a buffer for emergencies.
But don't stop there. As you make more money, keep your expenses low. Invest the difference. Get out of corporate America as fast as you can. Take it from all the people in their 50s+ laid off, it's pretty hard to job search at that point.
Tap into your network now, not when you need it. If you're good at your job, your body of work does most of the heavy lifting here. That's why it still matters to try hard. Start with previous colleagues. But you have to be genuine, like you're actually making friends. You can't just ask for stuff, you need to give value and care about the other person.
And when it comes to your industry, skate to where the puck is going, not where it is. The skills that got you here might not be the skills that keep you employed in 3 years.
Clues that someone grew up poor:
- Stores a massive amount of food in the pantry
- Cannot say no to children
- Isn't particularly worried about losing a job or financial calamity ("I've been poor before, I can do it again")
- Can remember a specific moment from childhood when they realized they were poor (often involving shoes or bread)
- Proudly not going to pay for kids' college ("I did fine without help. They can too" <-- it's always a man saying this, never a woman)
- Not expecting to live past ~40
- Don't ask for help
- When in deep financial trouble, they double down and work harder, including nights/weekends, even when their health suffers
All of these are real clues from real people on my podcast, Money For Couples
Signs Your Manager Is Setting You Up To Fail
(If you have more than 5... RUN!! )
1. You're given vague instructions then blamed for missing details.
2. They overload you with tasks... then act surprised when you drop one.
3. Critical Info is 'forgoten' or shared too late
4. Deadlines are unrealistic - but expectations stay sky-high.
5. They assign you roles outside your expertise -without support.
6. You're excluded from key meetings but still held accountable.
7. You get zero feedback... until it's time for a performance review.
8. Your wins are ignored but your mistakes are documented.
9. They keep shifting the goalposts so you never "measure up."
10. You're isolated, overworked, and slowly doubting your own value.
(Which one did I leave out?)
Your resume isn't the (only) problem.
The recruiter or hiring manager simply might not be seeing it.
Most recruiters manage 20-40 roles with 100+ applications each. While some recruiters read every resume, a lot more recruiters don't. They find 3-5 candidates who fit the specs and move on.
You could be Lebron James of whatever your niche is, but if your resume is #51 in cue, you might be beat.
Stop applying through portals. Go direct:
• Target 75%+ fit roles only
• Find the hiring manager on LinkedIn
• Get their email
• Send a short, direct message
• Then apply through the portal
https://t.co/YgLsq1li3o
The hiring process is illegal or marketing is fiction.
👇👇👇
“AI you can trust.”
That’s how Eightfold AI is marketing itself today. (email screenshot of what I got below)
The most recent explosive lawsuit featuring Workers vs AI describes Eightfold's system as it: “lurks in the background of job applications” and “score[s] [applicants] from 0 to 5.”
Lower-ranked candidates are “discarded before a human being ever looks at their application.”
Applicants have “no meaningful opportunity to review or dispute” the report.
The complaint is explicit:
“There is no AI-exemption to these laws.”
Hidden system.
Unseen scores.
Life-altering decisions happening without the candidate. But yeah... totally fair hiring process right?
Went on a work trip to johor and stopped by this cafe called knock knock. Istg the food is insanely good!! 🤯
I had the best truffle pancake ever and I’d honestly drive all the way from Cyber to Johor just for it again