➡️Key execution risk: Capacity expansion is far ahead of current volumes; the business needs strong volume growth to justify the capital deployed.
Not a buy/sell recommendation
#zelio
➡️Growth optionality: High-speed scooters, Tanga e-3W, exports and expansion from 400+ dealers provide multiple growth avenues.
➡️Big capital raise: ~₹168 Cr preferential issue at ₹853/share, plus ~₹84 Cr promoter warrants. This gives the company substantial growth capital.
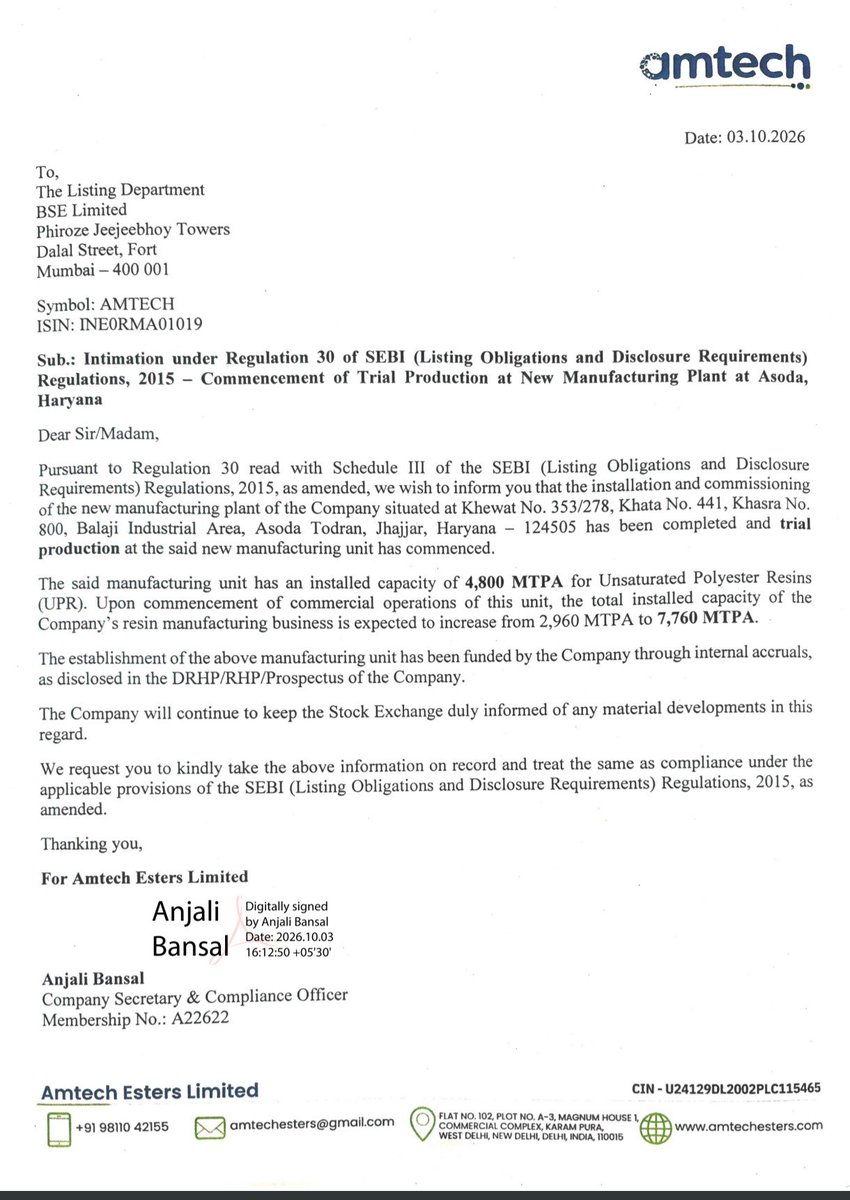
🚨 Amtech Esters — New Manufacturing Plant Update
Amtech Esters Ltd. has commenced trial production at its new manufacturing plant in Asoda, Haryana. 🏭
🔹 Installed capacity: 4,800 MTPA of Unsaturated Polyester Resins (UPR)
🔹 Total resin capacity to increase from 2,960 → 7,760 MTPA
🔹 Capacity addition: ~2.6×
🔹 Plant funded through internal accruals
🔹 Commercial operations expected to further strengthen the company’s manufacturing scale.
A meaningful capacity expansion that could support the company’s next phase of growth. 📈
#AmtechEsters #AMTECH #SME #SmallCap
Amtech Esters: Trial production has commenced at its new 4,800 MTPA UPR plant in Haryana, taking total resin manufacturing capacity from 2,960 MTPA to 7,760 MTPA (~2.6×). The expansion is funded through internal accruals. 🚀
#amtech
➡️ Long-term ₹500 Cr peak revenue potential is being discussed, but depends on phased expansion and future capital raising
➡️ Key concerns: working capital, government receivables, capital requirements, facility execution & potential dilution
Not a buy/sell recommendation
➡️ Business mix targeted to shift from 65:35 trading/manufacturing toward 50:50, potentially strengthening the manufacturing base
➡️ ₹47 Cr PSU order remains largely unexecuted, with execution dependent on advance payment and facility readiness
➡️ EBITDA margin declined in H2 FY26; 100% imported cells and China dependence remain important monitorables
📌 Key monitorables: Duhai ramp-up, ESS/3W traction, EBITDA margins,working capital, funding/dilution & execution of the large capex plans
Not a buy/sell recommendation
MaxVolt | Recent Call — Key Points 🧵
➡️ FY26 Revenue ₹296.7 Cr —+176% YoY; EBITDA ₹35.6 Cr with ~12% margin
➡️ H1 FY27 revenue is around ₹236 Cr
➡️ ₹150 Cr order book
➡️ E-scooter battery packs contribute~73% of revenue, with ESS showing strong growth from a smaller base
➡️ 10 GWh mega-plant planned in two phases, involving ~₹700 Cr capex and significant long-term revenue potential
➡️ ICAT L5 approval opens the door to the electric 3W segment
➡️ Battery recycling subsidiary MaxVolt ReEarth plans a 7,600 MT/year facility at Auraiya
@ApurvBajpazk9o Let’s wait for some positive development, results, or any meaningful update from the company.
Expecting a good set of results. Let’s see how the business performs. 🤞
@ApurvBajpazk9o No major update on Anondita as of now.
Traders are active in the stock, without any meaningful business update or positive announcement from the company, it may be difficult for the price to sustain an upward move.
➡️ BIS certification for the new facility remains an important milestone for discom-specific approvals
📌 Key monitorables: Plant commissioning, HT ramp-up, revenue growth, margins, receivables, debt/capex funding & BIS approval.
Not a buy/sell recommendation.
#Bhadora
Bhadora Industries | Recent Call — Key Points 🧵
➡️ FY26 Revenue ~₹125 Cr; PAT remained around ₹10 Cr
➡️ ₹100 Cr order book, with ~85% from private customers and ~15% government
➡️ FY27 revenue guidance: ₹210–225 Cr, implying strong growth from FY26 levels
➡️ HT cables expected to contribute ~25–30% of FY27 revenue
➡️ New demand opportunities emerging across railways, metros, data centres & renewables
➡️ Exports being explored across Africa, Nepal and UAE