$NBIS shelved overpriced unsecured HY debt because they closed a $3.5B secured Citi bridge at SOFR+275bps instead, backed by $7.43B in cash.
Q3 earnings already answered the funding question as upfront customer prepayments now cover >100% of equipment CapEx, funding 75-85% of the $40-45B FY27 buildout via prepayments + ABS.
The real risk is execution on delivery timelines and collecting the $4.04B in Q3 receivables on schedule.
@malmadhi2018 Exactly. $NBIS and $CRWV are effectively using customer balance sheets via >70% CapEx prepayments, while $ORCL is levering up its own IG balance sheet to fund the buildout hence the downgrade overhang.
In my opinion, the acute AI credit panic is over as $CRWV shelved unsecured HoldCo debt until 2027 and proved the funding model shifts to customer prepayments ($9B in 3 mos) + asset-backed debt.
Now it’s strictly an execution check. Three things that matter next:
• $CRWV ~$4B IG loan (MS/MUFG): Backed by chips & $META contract. Needs to clear at 7–7.5%; >8% means lenders still charge a distress tax.
• $ORCL Moody’s decision (~Dec 9): Baa2 (Neg) vs S&P’s BBB-. One downgrade triggers forced IG-fund selling.
• $NBIS $3.5B Citi bridge: 364-day clock ticking to Oct '27 (stepping up to SOFR+350bps) right into a $40–45B FY27 CapEx wave.
Solvency stress is fading as execution risk is taking the wheel.
@SpV_coin Fair.
Flows always beat spreadsheets in the short run. SOTP just tells me where the real floor is once the defensive rotation into staples runs out of gas
Post-earnings SOTP math on $NBIS at $115.88/share (~$33.9B MCap + $6.8B Net Debt = ~$40.7B EV):
ClickHouse Stake (~25-28%): Last valued at $15B (Jan '26 Series D), now past 5,000+ paying customers (up from 3,000 in Jan) following the Nov 9-11 Xata acquisition and Managed Postgres GA launch. At a $15-18B mark, $NBIS's stake is worth $3.75–5.04B gross, or $2.63-4.03B net after a 20-30% illiquidity discount (DLOM).
Other Non-Core (Avride, TripleTen, Toloka): Conservatively $1.0-2.0B.
Implied Core AI Cloud EV: Subtracting non-core assets leaves ~$34.7-37.1B for the core data center business.
The takeaway: You’re paying ~2.8–3.0x FY27E revenue ($12-13B guide) and $7.0–9.2M per contracted MW (on >4 GW contracted, scaling to 5 GW) essentially near replacement CapEx ($21.5B PP&E on balance sheet / $27B FY26 CapEx plan) with almost zero platform premium priced in after the Q3 timing push-out.
@RealJimChanos They aren’t unprofitable on GPU rentals GAAP net income is just masked by front-loaded D&A on multi-GW sites that aren't energized yet. At $3.10/hr, incremental EBITDA margins are ~50% with a 19-month payback and >100% upfront CapEx prepayments
Elon’s whole populist victory lap over Jensen’s exit like offering him a job and playing the savior is pure theater.
Dario Amodei (the biggest beneficiary of Jensen getting pushed out) can easily tear up contracts with Elon’s data centers almost without warning.
Spare the PR tweets.
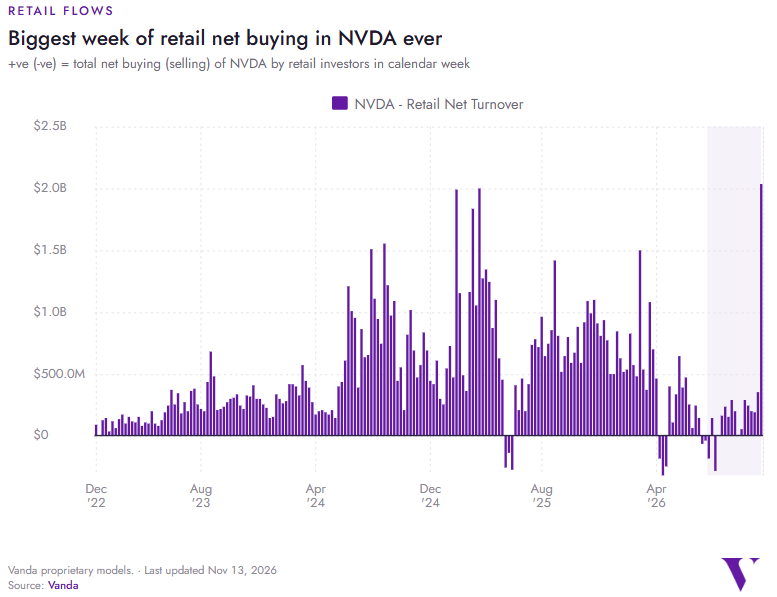
So when the marginal retail buyer is already maxed out and gets liquidated on the next leg down who exactly is left to buy the dip? Institutional exit liquidity at its finest.
@AlphaOwlTrading Ngl I caught a bit of FOMO and added too on those days 😅
Expected an $IREN type reaction like mixed print, rips anyway clearly didn't happen. Thank god I trimmed some longs yesterday, reloading today.
$NBIS BHM01 Birmingham, AL Site Update:
A Mechanical permit MEC2026-00852 was issued yesterday, Nov 12, for "installation of all mechanical equipment and piping systems." That's the cooling and piping package, so the MEP fit-out is starting. The portal also confirms the substation permit (BLD2026-00780) and HV electrical permit (ELE2026-01902) are issued, while sprinkler permit FPT2026-00380 ("First Light," seven systems) and the fire alarm/VESDA permit FPT2026-00388 are still only submitted.
-Ace ♥️
$IREN
Zero alpha in predicting PPI. Setup fir today is:
Hot (>0.6%): pure pain, very bearish.
Cool (~0.4%): gives us a shot at a massive technical bounce.
On a cool print, real estate and CapEx-heavy plays like $CRWV $IREN $NBIS are the first places I'm looking for a squeeze.
@benshanyoufeng@cemaxunfeng@grok Any shareholder would vote for his return as this is the only way nvidia saves its extravagant growth. Actually shareholders should consider voting on firing the board.