@JokerForAll1@_KiranRajput What is inflation numbers in India? How much you will get through FD ? When they both are near to equal and after taxation for FD you are making negative returns simply. Just go ahead if you are happy with it
Starting a SIP takes 2 minutes.
Staying invested can take 10 years.
In August, the SIP stoppage ratio was 81%.
That means for every 10 new SIPs, around 8 SIPs were stopped or matured.
The real challenge in equity investing isn’t starting.
It’s staying invested when the market tests your patience.
“Sir, your policy has changed. 40% co-pay is now compulsory. You should port your policy.”
That’s the call my client received at renewal.
And the shocking part?
The caller knew:
• His policy details
• His renewal date
• His premium
• The policy terms
He sounded so confident that my client almost believed him.
Then came the next statement:
“Your premium will increase by 15% every year. Better move to another company.”
Thankfully, my client called me before taking any action.
The truth?
There was NO such compulsory 40% co-pay imposed on his policy.
This is exactly how some people misuse customer data.
They call you around renewal, create fear, confuse you about your existing policy and then push you towards another policy — because there is a commission waiting for them.
Another client recently received a call:
“Sir, you have a free Personal Accident cover worth ₹45,000. Some amount will be deducted from your account…”
He simply disconnected the call and called me:
“Nikhil Sir, is this genuine?”
I told him:
“No. Don’t entertain these calls.”
And this is where the insurance industry loses trust.
Customers already have enough confusion about insurance.
They don’t need someone creating MORE fear just to earn a commission.
So if your renewal is coming up, remember this:
DON’T port your policy because someone called you.
DON’T believe claims about changed terms without verification.
DON’T share OTP, bank details or payment information.
And most importantly
Before making any decision about your existing policy, call your insurer or your trusted advisor.
One wrong decision at renewal can create a much bigger problem when you actually need to claim.
Insurance is supposed to protect you from uncertainty.
Not become the reason you live in fear.
Please share this.
Someone in your family may receive this call tomorrow.
🚨As IRDAI cracks down on mis-selling and dark patterns in insurance,
Here’s a real claim story that shows why selling a policy is only half the job🔥🔥
A customer messaged us 5 days ago.
He had bought his health insurance policy ONLINE.
Recently, he was hospitalised with dengue.
When he filed a claim, the insurer rejected it, saying:
“Hospitalisation was not necessary.”
He was scared.
He didn’t know what to do.
So we stepped in.
We connected with the insurer’s claims team, understood the issue, raised the matter
Within 24 hours, the claim was settled.
The customer bought the policy online.
But when he needed help, we didn’t tell him:
“You bought it online, now handle the claim yourself.”
We helped.
And this is especially relevant today.
IRDAI is cracking down on
1. mis-selling,
2.dark patterns(spam calling customers)
3. poor customer support in insurance.
And honestly, this is exactly the direction the industry needs.
Because selling a policy is only half the job.
Standing by the customer when they actually need the insurance—that’s the other half.
We don’t earn even *₹1* from helping settle a claim.
In fact,
we sometimes have to fight with insurers for our customers.
But we do it because we want people to trust insurance.
We want customers to:
→ Buy the right policy
→ Understand what they’re buying
→ Get claims that are rightfully payable
→ Have someone to turn to when things go wrong
One day, I hope mis-selling, dark patterns and selling policies purely for commissions become things of the past.
That will be a very, very good day for insurance.
Until then—
On to the next claim that needs help.
Small caps get all the attention.
But midcaps have the better track record.
Look at the long-term numbers,
as of 31 Aug 2026.
20-year CAGR
✅Nifty Midcap 150: 16.0% 🔥
✅Nifty Smallcap 250: 13.8%
✅Nifty 500: 12.5%
✅Nifty 100: 12.1%
The gap looks small.
But over 20 years,
even 1% makes a big difference.
Midcaps have quietly compounded faster.
Flexi Cap isn't the only category with market cap flexibility.
These can also invest across large, mid & small caps:
Value - Buys stocks it believes are cheap
Contra - Buys out of favour stocks
Focused - Invests in a few high conviction stocks
ELSS - Tax-saving equity fund with a 3 year lock-in
Different strategies, similar flexibility across market caps.
🚨Cancer is brutal
It doesn’t just attack a person’s health.
It can destroy a family’s finances.
2 years ago,
A follower bought ICICI Lombard Elevate with us for his parents,
Premium: ₹70,000/year
In the 2nd year, his mother was diagnosed with blood cancer.
She has undergone repeated chemotherapy and is still under treatment.
Claims so far: ₹24,90,911
Premium paid in 2 years: ₹1.4L
Treatment covered:~₹25L
We got each and every claim piad with ZERO deduction on any claim,
He told us:
“Thank you for pushing me to buy a ₹25L policy.
I almost didn’t have enough money to support my mother’s treatment.”
For everyone calling health insurance a “scam”:
This is what good health insurance can do.
It can protect a family from being forced to choose between treatment and financial survival
When a critical illness strikes,
health insurance isn’t a luxury.
It can be the financial lifeline a family desperately needs.
Praying no one gets cancer and the follower's mother gets well soon🙏🙏🙏
This correction feels painful.
And it should.
But nobody rings a bell at the bottom.
Historically, some of the biggest opportunities appeared when fear was highest.
✅️2008 – GFC: -65%
Next 5 years: +300%
✅️2015 – Correction: -26%
Next 2.5 years: +73%
✅️2020 – COVID Crash: -39%
Next 1.5 years: +145%
✅️2022 – Russia-Ukraine: -19%
Next 2 years: +75%
The difficult part?
Staying invested when it feels hardest.
₹16,000 PREMIUM. ₹4.90 LAKH APPROVED.
Read that again.
This policy was taken in June with a ₹25 lakh sum insured, for a premium of just around ₹16,000.
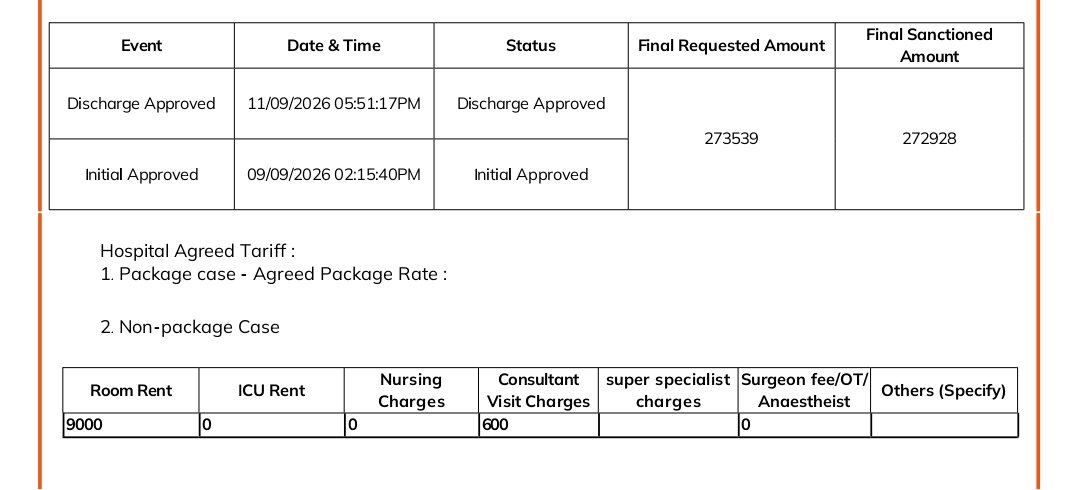
And yesterday night, after several rounds of continuous follow-ups, we finally got the discharge approval:
Final requested amount: ₹4,95,145
Final sanctioned amount: ₹4,90,360 ✅
Almost ₹5 lakh of hospital expenses covered.
Think about it…
You can save for years.
You can build a portfolio.
You can invest in stocks.
You can create a corpus.
But when a medical emergency suddenly demands ₹5 lakh, none of these were created specifically to protect you from that risk.
Insurance was.
₹16,000 might have felt like an expense when the policy was purchased.
Yesterday, it became a ₹4.90 lakh financial shield.
And this is why I always say:
Investments create wealth.
Insurance protects the wealth you create.
And there is one more important lesson here.
Buying insurance is only half the job.
Being there when the claim happens is the other half.
The customer should not have to fight alone when they are already dealing with a medical emergency.
₹16,000 → ₹4,90,360
No magic.
No shortcut.
Just the power of being adequately insured at the right time.
Insurance isn’t an expense.
It’s a blessing when life decides to test you. ❤️
Why does wealth seem to explode after ₹1 Crore?
It’s not magic.
It’s TIME + COMPOUNDING.
A ₹30,000/month SIP at 12% can approximately grow like this:
• ₹50L → 8 years
• ₹1 Cr → 12 years
• ₹2 Cr → 17 years
• ₹3 Cr → 20 years
• ₹4 Cr → 22 years
• ₹5 Cr → 24 years
The interesting part?
Getting from ₹0 to ₹1 Cr takes around 12 years.
But the next ₹4 Cr can come in roughly another 12 years.
That’s the power of compounding.
Start early.
Stay consistent.
Let time do the heavy lifting.
Investing as early as possible and investing the max possible amount matters along with the rate of return and time period you will keep your investment.
SIPs don’t fail because of the market.
They fail because investors don’t stay invested long enough.
Here’s where SIP money was held:
✅ 0–2 years: 49%
✅ 2–4 years: 24%
✅ 4–5 years: 7%
✅ >5 years: 20%
So 63% of SIP money is held for less than 3 years.
Only 20% stays invested for 5+ years.
And that’s the real challenge.
SIP is simple.
Staying invested is the hard part.
🚨 3 popular health insurance policies.
But if you could buy only ONE, which would you choose?
🥇 Niva Bupa ReAssure 3.0 (Black)
🥈 HDFC ERGO Optima Secure+
🥉 Aditya Birla Activ One MAX
All 3 look strong on paper.
But the real question is:
Which one gives you the best overall protection when you actually need to claim?
👇 Which one would YOU pick — and why?
COST OF DELAY
One year may look small.
But in long-term investing, it can cost you BIG.
Every year you delay is not just one year of missed investment. It is one year of lost compounding on all the future growth that money could have created.
The earlier you start, the longer your money gets to compound.
Don’t underestimate the cost of waiting. Start early. Stay invested. Let compounding do the heavy lifting.
Hope this image helps you understand the real cost of delaying your investment journey.
Fortune Investment Services (P) Ltd.
ARN: 197457
Disclaimer: This analysis is shared purely for educational purposes. It is not investment advice. Always do your own due diligence and invest based on your financial goals, investment horizon, and risk appetite. Please keep in mind that mutual fund investments are exposed to market risk. Before making any investment decisions, review all scheme-related documentation thoroughly. The material of the reports is intended solely for informational purposes and should be used by the recipient. While we made significant efforts to compile the data and contents of this report, we give no promises about the logic of the assumptions or the veracity of any data. Any decisions made using this material are completely the responsibility of the recipient. We reserve the right to correct any errors or discrepancies in the reports that are discovered or brought to our attention at any time. Perform your research thoroughly before making any investments. Why? Just because it's interesting.
🚨A bank employee came to us to buy health insurance.
Sounds strange, right?
He works at a large private-sector bank that already sells health insurance.
So I asked him:
“Why not buy it from your own bank?”
His answer was eye-opening:-
“Sir, at the bank, we have targets to sell policies.
Nobody really understands the policies in depth.
And nobody talks about claim support.”
His biggest concern wasn't the premium.
It was:
“Who will help me when I actually need to claim?”
And that's the problem.
When insurance is treated primarily as a sales/commission product,
Customers often get attention only until the policy is sold.
After that?
Good luck when a claim arises.
Bank employees themselves dont buy policies from the bank,
They are worried about claim support
RBI & IRDAI need to look closely at this.
Insurance isn't just about selling a policy.
It's about being there when the customer needs it the most.
Investing money in a real estate property which gives rental yield of 3 % and it appreciate over the years. SWP can be used as better alternative than the real-estate property
SWP is a brilliant concept.
If you invest 1 crore at 8%* returns,
withdraw 50,000/month for 30 years,
you could still end up with over 3 crore.
That's the power of SWP!!!💪
Just finished a 1-hour call with a customer.
We discussed 4 health insurance policies in detail:
1️⃣ HDFC ERGO Optima Secure+
2️⃣ ICICI Lombard Elevate
3️⃣ Niva Bupa ReAssure 3.0
4️⃣ TATA AIG Medicare Select
We went through everything:
📈 Inclusions
📈Exclusions
📈Waiting periods
📈Claim process
📈 And most importantly — our role in supporting him during claims.
The call was long.
But the customer said:
“Thank you for being patient and explaining everything.”
THIS is how health insurance should be sold.
📈Not by hiding exclusions.
📈Not by overselling benefits.
📈Not by saying “claim ho jayega.”
Really standing with customers during buying and also claims
Explain the policy BEFORE the customer buys it.
Slowly but steadily, I hope more agents start selling this way.
Because an informed customer is far less likely to be surprised when a claim happens.
Insurance is not just about selling a policy.
It’s about making sure the customer understands what he has bought. 😆
💯 fact. Those events are finished so we clearly know what happened but the ongoing correction nobody knows how deeper it will go and the recovery time how much it takes.
HDFC ERGO ONLINE POLICY → CASHLESS REJECTED 🚨
@oxsanthu Mr. Santosh had purchased his HDFC ERGO health insurance policy online.
When his wife was hospitalised in Hyderabad, the cashless facility was rejected.
That’s when he approached us.
We are in Mumbai.
The client is in Hyderabad.
Still, we managed the entire reimbursement claim remotely.
✅ Claim documentation
✅ Follow-ups
✅ Coordination with insurer
✅ Reimbursement claim handling
✅ Claim amount received in his bank account within 20 days
No physical meetings.
No running around.
Just proper guidance and continuous follow-up.
The policy was bought online.
But when the claim got difficult, he needed human support.
Insurance can be bought online.
But when you need it the most, having someone to guide you can make all the difference.
Review your term insurance.
It’s not a “buy once and forget” product.
You may have bought term insurance at a young age with a 50lakh or ₹1 Cr cover.
It may have been sufficient then—but is it sufficient today?
Recently, a customer’s wife approached us for a claim and realised that her husband had only ₹1 Cr term insurance, taken in 2019 when he was earning around ₹12 lakh/year.
In the last 6 years, his income increased almost 7–8 times.
For the last 2 years, he was earning around ₹90–100 lakh/year.
His loans and financial responsibilities had also increased significantly.
But his term insurance remained at ₹1 Cr.
₹1 Cr is a good cover—but it may not be enough when you consider inflation, income growth, lifestyle expenses, loans and your family’s future financial needs.
👉 Review your term insurance every few years.
👉 Increase the cover as your income and responsibilities grow.
👉 Or, when buying young, consider a higher sum assured keeping your future needs in mind.
Your income grows. Your responsibilities grow. Your term insy cover should grow too.