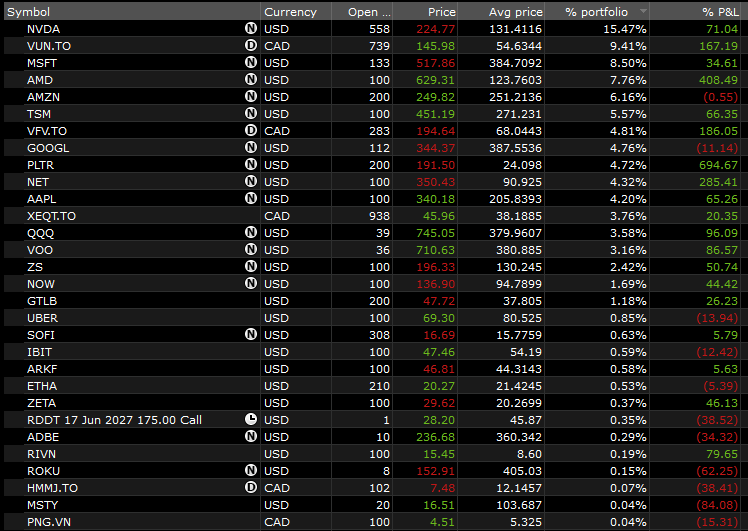
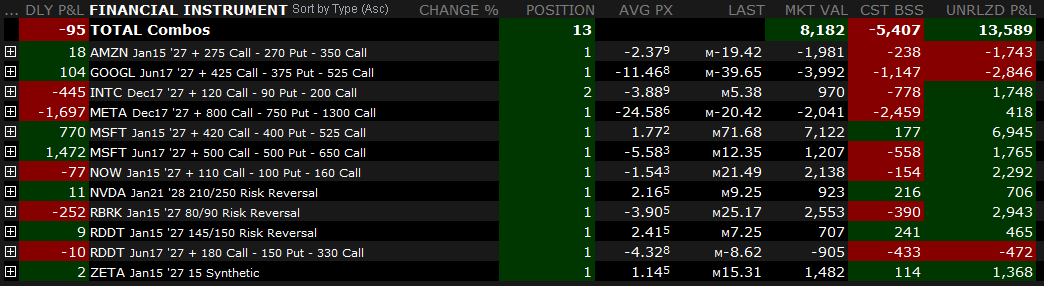
@InvestingAddict Starting early and consistently investing is the 🔑! I started managing my own investment portfolios late (late 40s), but have helped get my kids start young by showing them how and where to invest consistently.
Here is one of the best YT channels if you are starting out as a diy index/ETF investor in Canada. Justin Bender does a great job of covering all the details - https://t.co/l41AXSdtbt
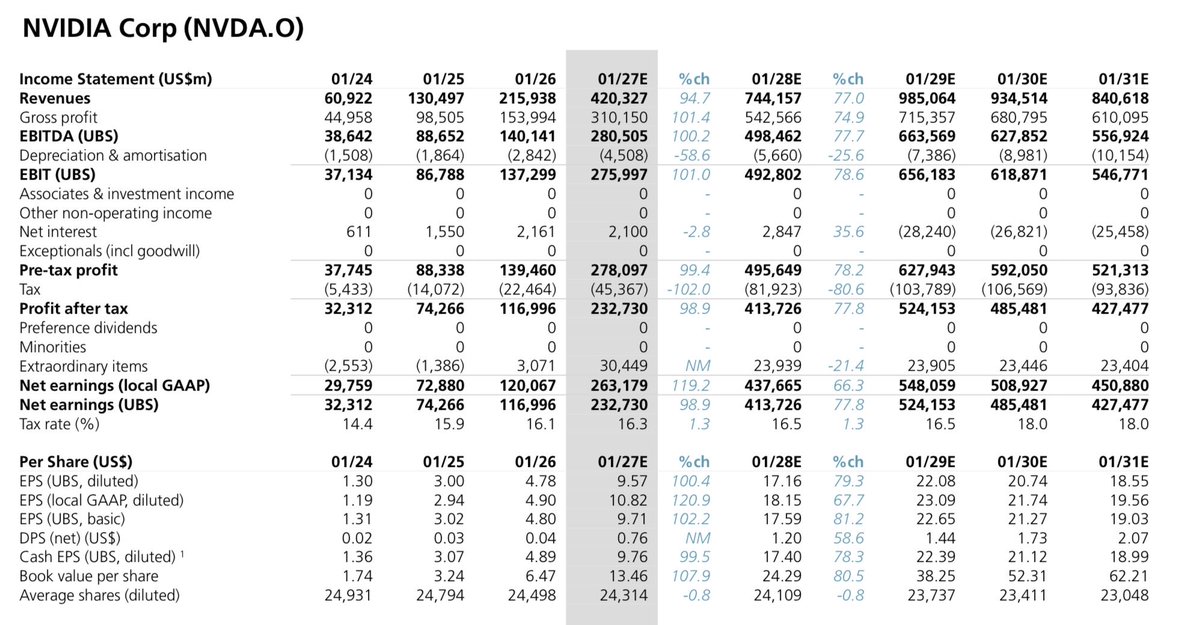
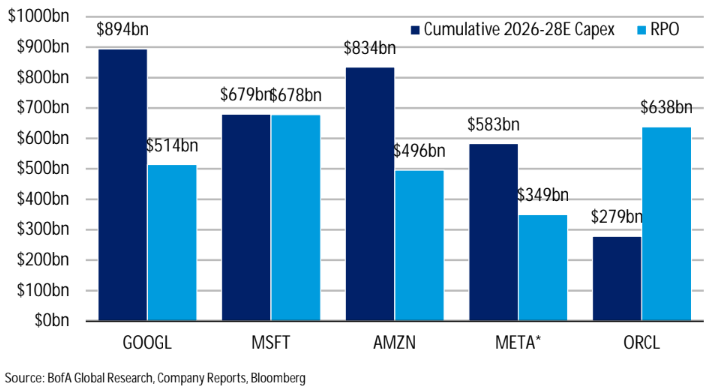
BofA on cloud capex ahead of Q3 earnings: Data center remains the key stronghold into Q3 earnings, with four major US hyperscalers (Google, Microsoft, Meta, Amazon) set to report in the coming weeks. Our tracker indicates Q3 global hyperscaler capex at $291bn (+27% QoQ/+110% YoY). For CY26/27E, capex now $1.01 T/$1.39 T (+98%/+37% YoY), well above our +78%/+35% post-Q2 outlook in Aug, partly as we now include neoclouds (e.g. xAl, CoreWeave). Despite ongoing volatility in Al semis and concerns of an Al slowdown (e.g. OpenAl ARR now reported at $50 B vs. $70 B prior), we view capex as sustainable into CY27E and beyond, backed by: 1) commitments and backlog, with RPO exceeding ~$2.3Tn across the top 4 CSPs, 2) near-high spot GPU rental prices, suggesting continued training and inference demand, and 3) a near-annual cadence of new Al use cases (e.g. agentic Al) driving token generation.
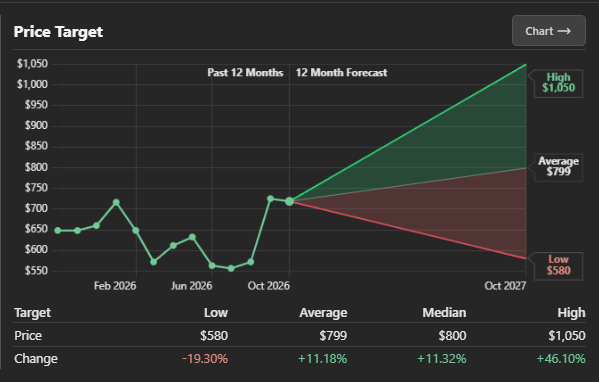
MS: Al world is becoming multi-model, and that's good for $MSFT. In an increasingly multi-model world, Microsoft can potentially win by owning the infrastructure that runs the models (Azure + Maia/Cobalt), the enterprise data that makes them useful (Fabric), and the control plane through which enterprises consume them (Foundry), while providing the application and distribution layer through which that intelligence reaches users and workflows (Copilot). In short, this can be referred to as the Enterprise Al Flywheel, in which Fabric supplies enterprise context, Foundry selects the appropriate model, and Copilot delivers the result to end users, with the resulting usage driving incremental Azure consumption. Bottom line, Microsoft's differentiation increasingly extends beyond the underlying infrastructure or any individual model to the
context, orchestration and application layers surrounding them. The Al debate has historically centered on access to GPUs and which frontier model wins, though we think the next phase increasingly shifts toward who can deliver the right intelligence for each workload while integrating it with proprietary enterprise data and applications. Remain OW, PT 600.
$SPCX reached a deal to buy cellular spectrum licenses from investment firm Grain Management, its biggest move yet into a wireless market dominated by traditional telecom companies. The U.S. licenses, which are in the 800-megahertz band, are tailored for wireless service from cellphone towers rather than satellites. The spectrum could serve SpaceX’s stated ambition of moving its Starlink satellite service beyond broadband into the wireless market to compete with the likes of $T and $VZ.
https://t.co/CadAXkalr1 via @WSJ
Whether a U.S.-listed ETF is worth buying here in Canada depends on foreign exchange costs, taxes, MERs, and your investment account - https://t.co/M1PyNNMNfS
Relatively a new account here, and like your work a lot. I am primarily a LT investor with some swing and options trading in my cash/margin account. I am sharing my portfolio/journey, and useful market info to provide value to the X community. Will appreciate a follow as I would like to grow verified followers as a newbie to this platform, thanks.