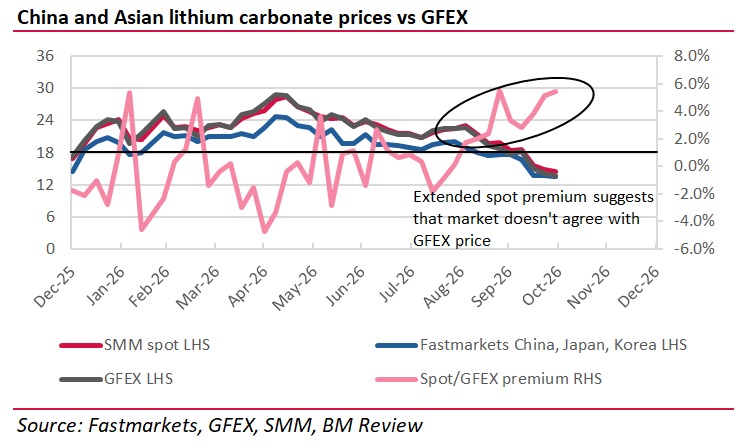
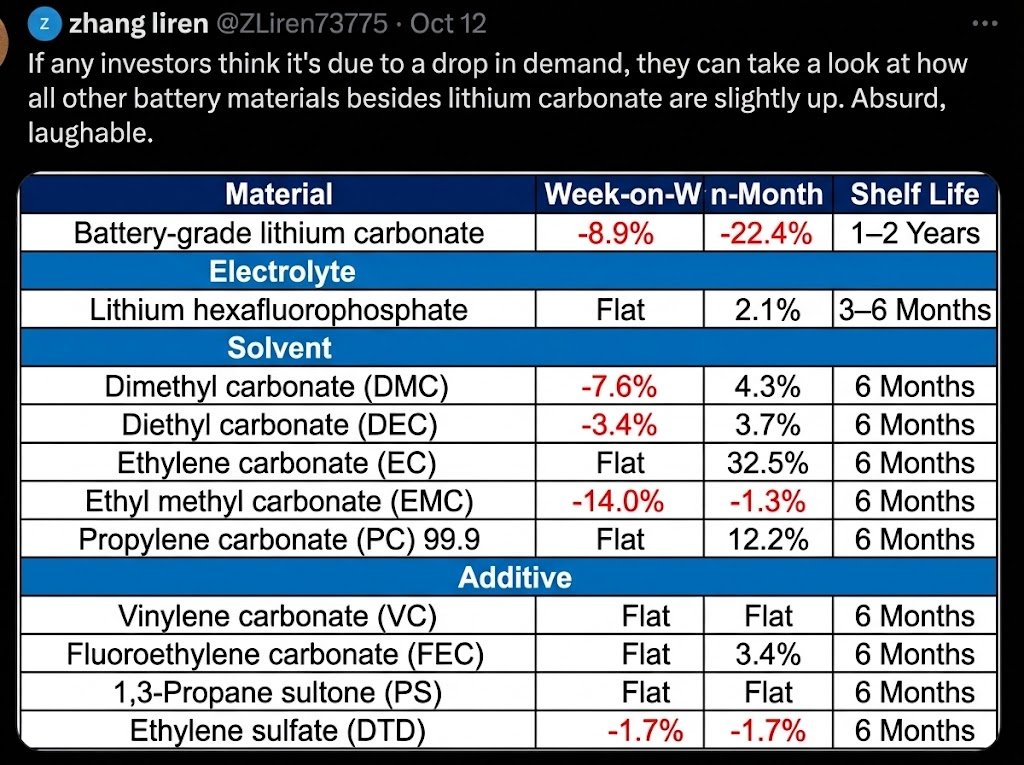
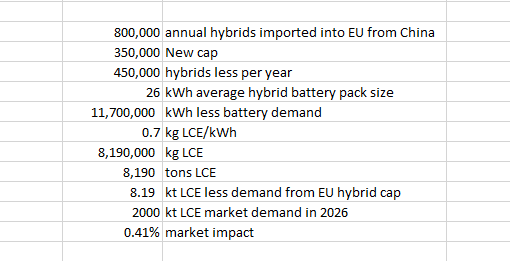
Thanks to Jordan Roberts from Project Blue for pointing out the disconnect between spot prices and the GFEX. It is substantial and extended and suggests that the market itself does not agree with current GFEX pricing...
@WayneHines24470@MinerDeck I'm afraid that the only way to stop the manipulation is for western interests to increase refining and cathode production... until then they can do what they want.
The #lithium market continually reacts to short term rhetoric that is often incorrect rather than looking at the bigger, long term picture. Buy quality and long term - lithium stocks will be just fine. If you are a trader, good luck. When SMM purports to know lithium production and inventory to the kg, the real story is people believe them.
Sentiment on lithium has turned very negative, mostly on the back of unrelated bits of information. So let's talk numbers, not opinions. What do we actually know?
Demand. The hard data: China's battery production through August 2026 is up the equivalent of ~400kt LCE vs last year. If we carry only part of that growth through to year-end, Chinese batteries alone add at least ~500kt LCE of demand vs 2025.
Supply. Here the only hard data is exporters' trade statistics. Change vs 2025, in kt LCE (YTD Aug → full-year 2026F):
🇦🇺 Australia: +30 → +60
🇨🇱 Chile: +70 → +50
🇦🇷 Argentina: +30 → +65
🇧🇷 Brazil: -10 → -15
🌍 Africa: +50 → +65
🇨🇦 Canada: 0 → 0
🇨🇳 China: +40 → +70 (the softest number)
Total: +210 → ~+295
Even after adding the production that projects and producers have announced, 2026 supply growth comes to roughly 300kt. It's not much more than that. It can't be much more than that.
So for 2026:
Demand: +500kt
Supply: ~+300kt
Balance: a deficit of ~200kt LCE
The deficit is already here.
2027? The bears say demand will pull back. That's much harder to agree or disagree with. But the inventory drawdown happening right now will clearly push the market into deficit.
Figures and views are iLiMarkets' assessment.
@sachzaus@ElevraLithium Your numbers seem reasonable, if not conservative. This would be the entire FY26 profit in Q1. I think some folks will be surprised when this comes out.
🚨 CATL JIANXIAWO: The market may be jumping the gun.
There are TWO separate environmental approval workstreams:
1️⃣ The MINE itself
2️⃣ The CONCENTRATOR + TAILINGS facilities
The current EIA covers the mine — NOT the concentrator and tailings facilities.
Even if the mine EIA is approved, full production cannot simply restart. The downstream concentrator/tailings environmental procedures still need to be completed.
That means more regulatory steps — and more potential for delay.
So don’t assume ~100ktpa LCE suddenly comes back after the mine EIA.
Q1 2027 may be achievable if everything moves smoothly, but a restart slipping BEYOND Q1 is a very real possibility.
Mine EIA approval ≠ production restart. 🔋⚡️
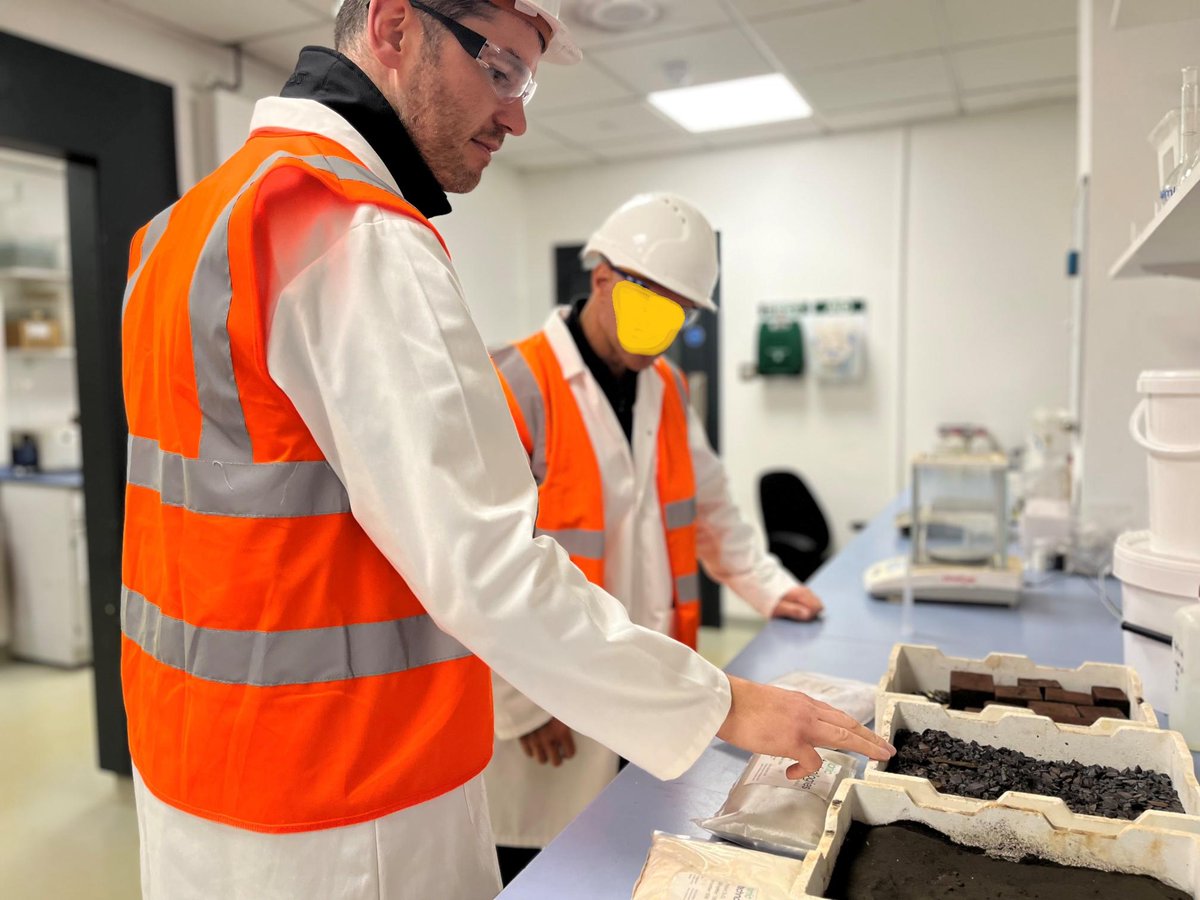
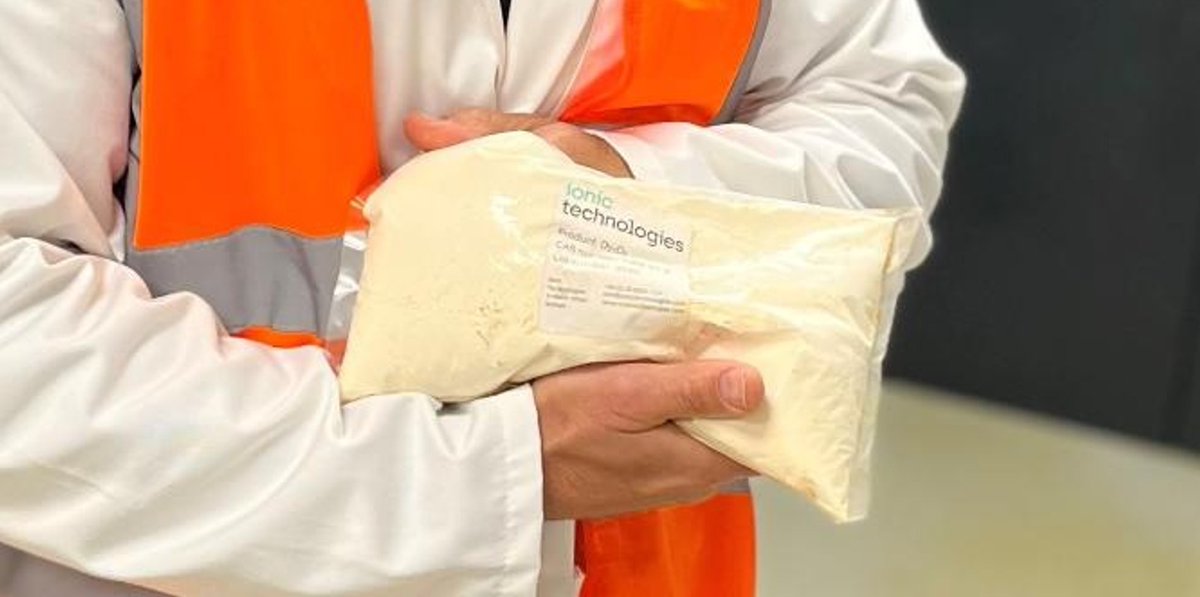
🚨🇬🇧 A fellow IXR shareholder just spent 3.5 hours INSIDE Ionic Technologies' Belfast rare earth recycling plant, and held a sealed bag of separated DYSPROSIUM OXIDE, the heavy rare earth everyone says the West can't make. His first-hand account, with photos approved by the company. 🧵
🔗Full Post on HotCopper Can Be Found Here
https://t.co/Iyw3rBrrJr
📍 The Visit
A long-term shareholder (Koproskilo on HotCopper — report and photos shared with his permission) was hosted at Ionic House, Titanic Quarter, Belfast Harbour by Thomas Kelly and Fergal Coleman, the latter straight from Queen's University Belfast that morning, where the MAIL technology was invented by Prof Peter Nockemann, who still sits on the Ionic Tech board.
🔒 Strictly no photos inside after a previous incident risked IP, Thomas took these at predetermined locations and approved them for sharing
🏢 Corporates, financiers and unnamed major tech manufacturers are now regular visitors to the plant
🧲 The Feedstock Machine
Pallets of magnets on site, sorted into buckets by source: EV motor magnets, hard-drive magnets, MRI magnets.
🤝 EMR has ~25 tonnes warehoused a mile away, with pricing being locked in per magnet type, years of unglamorous collaboration maybe only 1–2 other UK/EU operators can match
🆓 As the company's name grows, feedstock is being OFFERED to them, some of it free
♻️ Visitors were told EV makers scrap up to 10% of e-drive motors on epoxy bonding failures, a potential OEM scrap loop, with return-of-swarf clauses planned in every offtake. A true circular economy
🌍 Even reagents are supply-chain conscious: oxalic acid sourced from Spain, not China
⚗️ The Product In Hand: Dy₂O₃
That sealed, labelled bag is dysprosium oxide — a few percent of a magnet's mass but an outsized share of its value, and one of the rare earths China restricts hardest.
🏭 The demo plant has run 24/7 for 30+ months, producing 10+ tonnes of separated REO at 99.5–99.9% purity
🧪 An unnamed peer stuck at 90% purity sent samples to Belfast, Ionic lifted them to 99%. Epoxy-contaminated feed goes to 99%+ with NO pre-cleaning step, while many newer processes can't reach spec on real, untreated feedstock
🚗 The same Belfast oxides Ford just validated in 100% recycled magnets, 99.87% Nd oxide, 99.56% Dy oxide, 99.75% Tb oxide, on the first attempt
🏗️ Demo to Commercial
🔧 New larger mixing tanks just added to the heavy circuit, the Dy/Tb end is being expanded
⚡ Nth Cycle is sending a demo unit to Belfast for installation into the circuit, the technologies are proving genuinely complementary
📋 Permitting progressing well; the harbour authority welcomes them as a permanent fixture. Long-lead commercial equipment is being specified and quoted NOW, the demo plant's 30 months of bug-hunting is exactly why the commercial ramp should be faster than peers jumping straight from pilot
🎓 ~25 staff and a QUB PhD pipeline for rollouts flagged in the USA, Brazil and beyond, while competitors rehire 80-year-old retirees, China has banned exporting rare earth IP, equipment AND talent
💰 DFS: US$108.7m capex, 400 tpa commercial plant, post-tax NPV US$502m, IRR 43.6%, £12m UK Government offer in principle, FID targeted this quarter
⚠️ Honest caveats: the capital stack still has to close, and the solar-heavy power plan for a city with ~108 sunny days a year is still being optimised (green grid power /Battery and carbon credits under evaluation). Demo scale is not commercial scale, but all the right ingredients are there.
👀 The Bottom Line
📍While others publish renders, IXR ran a "show me" play with its own shareholders, and a retail investor walked the floor, saw the feedstock buckets, and held separated dysprosium oxide in his hands. His takeaway: the commercial plant feels close to fruition.
📍Grade sets the prize, but feedstock partnerships, magnet liberation logistics which is now being executed through the Drive 35, @theapcuk, UK funded CirculaREEconomy Project with EMR (Feedstock Logistics) and chemistry proven on real, dirty feed win the game, and Belfast is the rare place where all three are visible in one building.
📸 Photos: taken and approved by Ionic Technologies on site, shared with the visiting shareholder's permission.
@IONIC_RE@IONICTECH_UK
#RareEarths #IXR #IonicRareEarths #MagnetRecycling #Dysprosium #NdFeB #PermanentMagnets #CriticalMinerals #HeavyRareEarths #Belfast #CircularEconomy #SupplyChain #Ford #EVs #Recycling #MineToMagnet
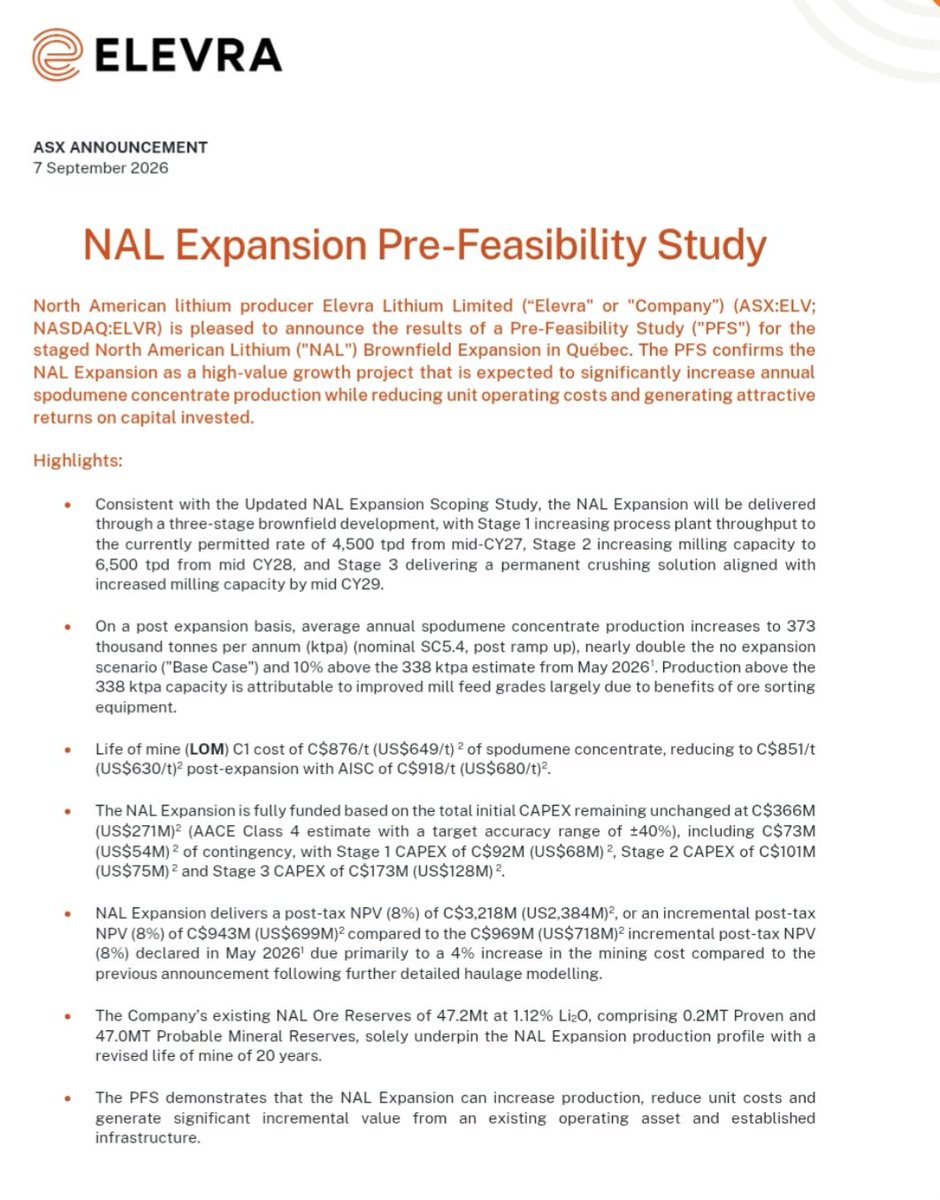
@ElevraLithium#NAL Expansion PFS confirms 373ktpa spodumene production
• C1 costs down to US$649
• Post-tax NPV of US$2.3B
• 》Fully funded《
More tonnes, lower costs, stronger economics. The value proposition for Elevra Lithium keeps getting better 🔋🚀
$ELV #Lithium#EV
@FieferP43990@WayneHines24470 You have nailed it!!
Let me see if I got this right.
GFEX kills high frequency trades to stop the price from rising because that was not fair.
They limited how fast the price can run up, because that was not fair.
BUT CATL can dump 10k in minutes, because that's fair.
China’s biggest lithium mine has lost its environmental approval, putting supply at risk as the market moves toward deficit.
CATL’s Jianxiawo mine is back in care and maintenance, with Benchmark cutting its 2026 production forecast 49%, from 62,500 to 32,000 tonnes of LCE.
A prolonged shutdown could further tighten a market where stronger EV and battery-storage demand is challenging years of oversupply.
Benchmark says a sustained restart could slip into 2027.
Meanwhile, other Jiangxi mines representing another 108,000 tonnes of expected 2026 production are facing inspections.