Everything (process, which results in making it a single horse race, price, which is atrociously low, government officers sitting on both sides) is wrong with IDBI bank sale. It is a black chapter in India’s public asset privatisation history. https://t.co/mixWRDQA3b via @YouTube
A VOICE THAT DESERVES TO BE HEARD!
Former Finance Secretary of India, Shri Subhash Chandra Garg, IAS, shares his views on the proposed privatisation of IDBI Bank.
His perspective deserves serious attention and thoughtful consideration.
The issue goes far beyond the sale of a bank. It concerns public interest, social justice, financial inclusion and the future of thousands of dedicated employees who have served the nation.
IDBI Bank is not just a financial institution; it is a public asset built on people's trust.
Our demand is clear: Protect public interest, safeguard employees' rights and keep IDBI Bank in the public sector.
IDBI BANK IS FOR THE PEOPLE, NOT FOR SALE!
#SaveIDBI #IDBINotForSale #StopPrivatisation #BankBachaoDeshBachao
#RollBackIDBISale
@DFS_India@PMOIndia@FinMinIndia@SecyDIPAM@rashtrapatibhvn
Former Finance Secretary of India, Shri Subhash Chandra Garg, IAS, speaks out on the proposed privatisation of IDBI Bank.
His views deserve serious attention. The fight to protect IDBI is a fight for public interest, social justice and employees' rights.
#RollbackIDBISale@Subhashgarg1960
VC : @thewire_in
VIDEO | Chennai, Tamil Nadu: AIBEA General Secretary CH Venkatachalam opposes the proposed majority stake sale in IDBI Bank, saying, "No public sector bank should be privatised; they are not contributing to the country's development."
(Full video available on PTI Videos - https://t.co/bIyFWTfmBd)
IDBI बैंक नुकसान में नहीं है। इसका Non Performing assets सिर्फ 2% है। यह बैंक लगातार मुनाफा दे रहा है।
⦿ 2021: 1,359 करोड़ रुपए
⦿ 2022: 2,439 करोड़ रुपए
⦿ 2023: 3,645 करोड़ रुपए
⦿ 2024: 5,634 करोड़ रुपए
⦿ 2025: 7,515 करोड़ रुपए
⦿ 2026: 9,513 करोड़ रुपए
2021 से 2026 तक IDBI बैंक का कुल मुनाफा 30,105 करोड़ रुपए है।
प्रति कर्मचारी सबसे ज्यादा मुनाफा देने वाले बैंक में IDBI 49.8 लाख रुपए Per Employee के साथ सबसे आगे है।
ऐसे में सवाल है- एक ऐसा बैंक जो इतना ज्यादा मुनाफा दे रहा है, उसे क्यों बेचा जा रहा है?
: @shaktisinhgohil जी
📍 दिल्ली
कानूनन किसी भी Disinvestment के लिए Valuation होना चाहिए। IDBI के मामले में ये Valuation 94.42 रुपए प्रति शेयर तय हुआ।
Valuation तय होने के बाद Bidder मंगवाए गए- लेकिन इसमें सिर्फ Fairfax का नाम ही सामने आया।
नियम कहता है- टेंडर खुलने के बाद प्रॉपर्टी का Valuation तय नहीं हो सकता, लेकिन इस केस में टेंडर खुलने के बाद Valuation 94.42 रुपए प्रति शेयर को रिजेक्ट कर दिया गया। फिर इसे घटाकर 75 रुपए प्रति शेयर कर दिया गया।
IDBI के बारे में राहुल गांधी जी ने जो सवाल उठाए, उनमें से किसी का जवाब सरकार द्वारा नहीं दिया गया।
RBI का नियम है- अगर कोई एक व्यक्ति किसी बैंक में 50% से ज्यादा स्टेक लेकर कंट्रोल करता है तो वही व्यक्ति दूसरे बैंक में कंट्रोल नहीं ले सकता।
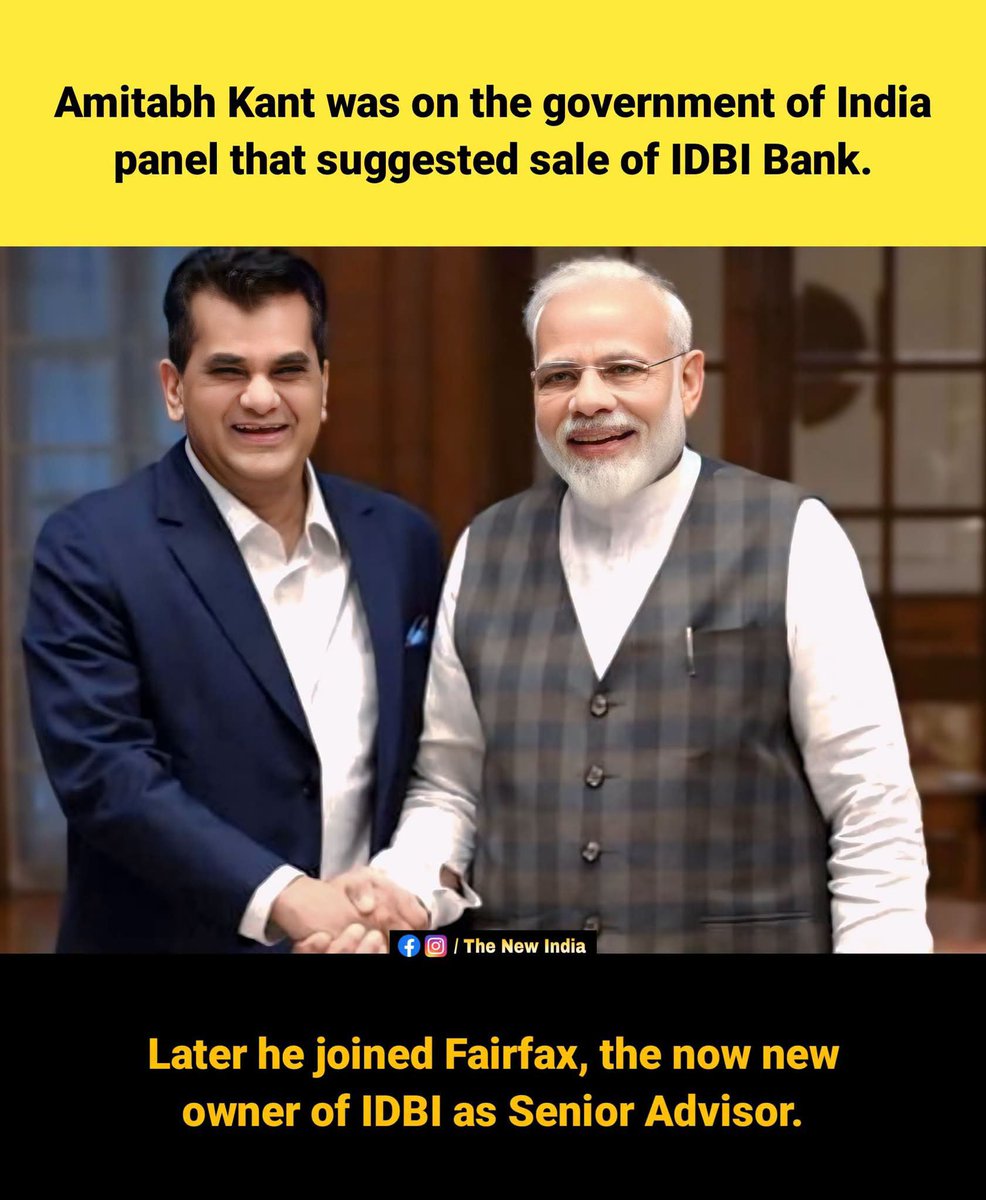
लेकिन Fairfax के केस में मोदी के करीबी को ढील दी गई। मोदी सरकार ने कह दिया कि अभी IDBI बैंक ले लो और फिर दो साल में दूसरे बैंक में स्टेक 50% से नीचे कर लेना।
: @shaktisinhgohil जी
📍 दिल्ली
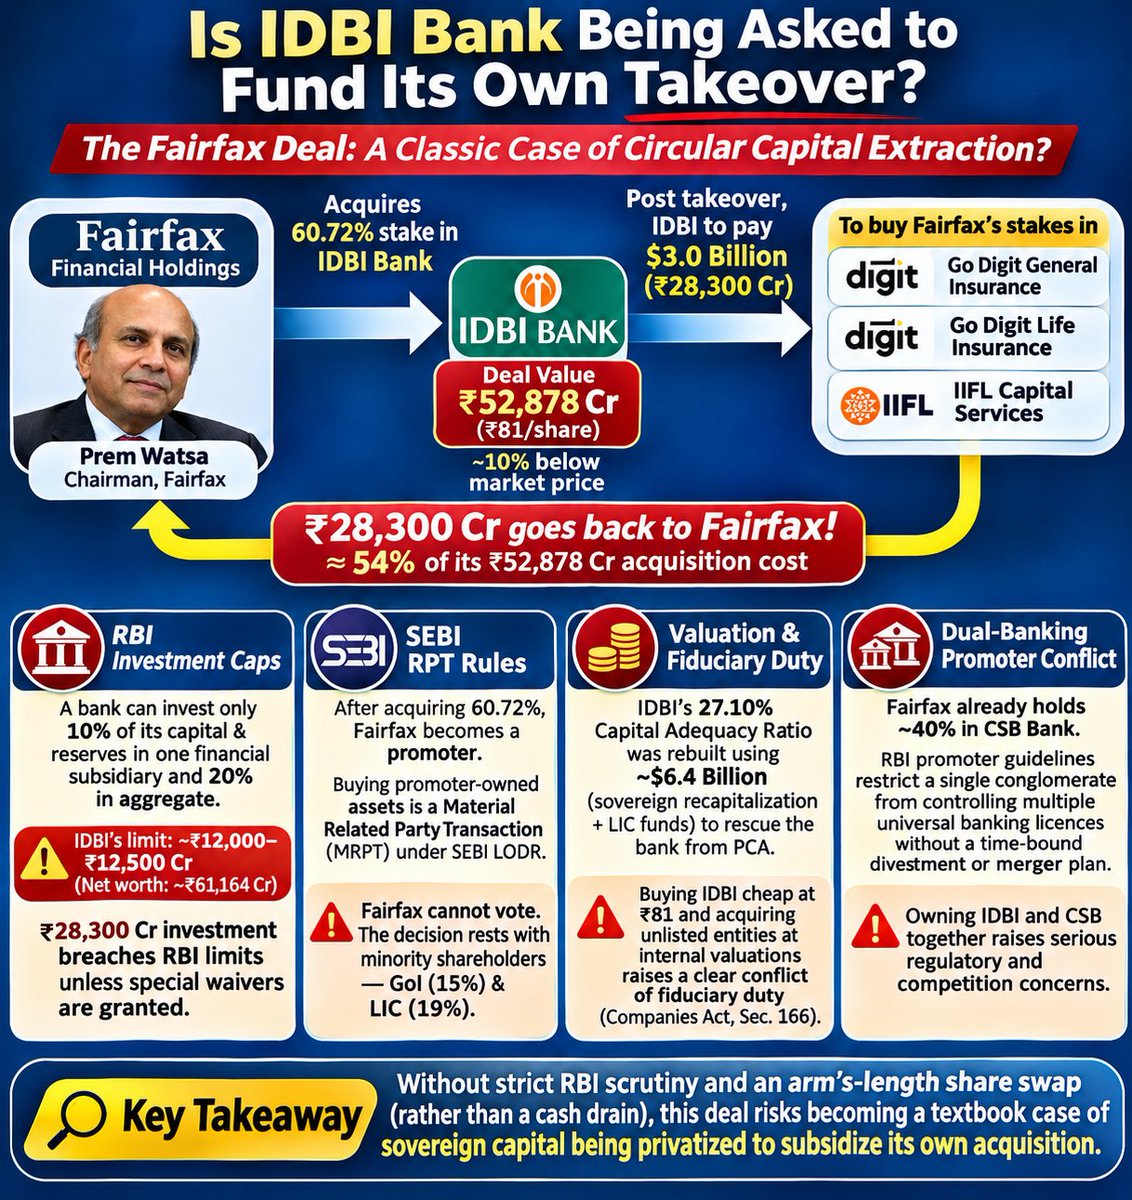
🚨 BUSINESSWORLD RAISES ANOTHER SERIOUS CONCERN IN THE IDBI SALE: IS IDBI BANK BEING ASKED TO FUND ITS OWN TAKEOVER?
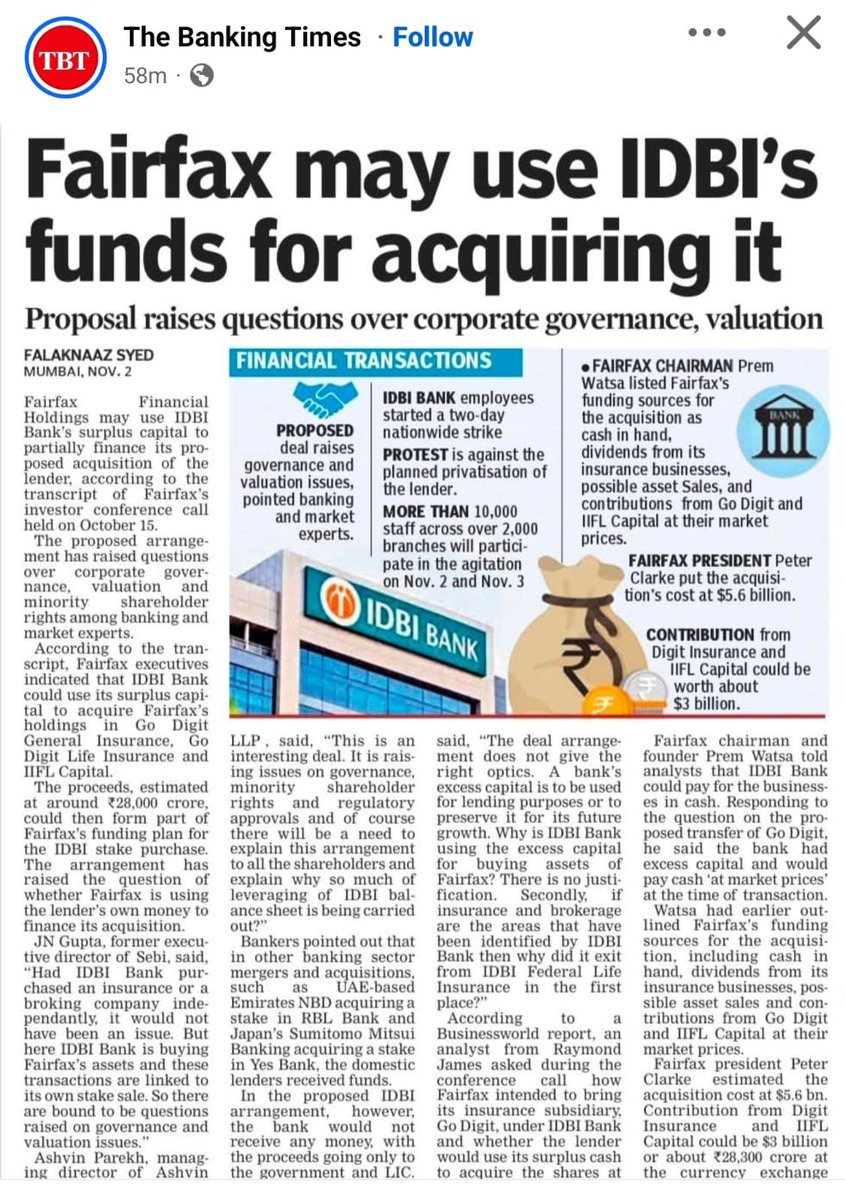
The details emerging around Fairfax’s ₹52,878 Cr bid (at ₹81/share, ~10% below market price) to acquire a 60.72% controlling stake reveal a troubling playbook of CIRCULAR CAPITAL EXTRACTION.
Prem Watsa’s investor call indicates that once in control, IDBI Bank will pay $3.0 Billion (₹28,300 Cr) in cash to buy out Fairfax’s stakes in Go Digit General, Go Digit Life, and IIFL Capital at "market prices."
That cash injection back into Fairfax accounts for nearly 54% of its acquisition cost.
HERE IS WHY THIS STRUCTURE FACES MASSIVE LEGAL, STATUTORY AND REGULATORY FRICTION IN INDIA:
1️⃣ RBI SUBSIDIARY INVESTMENT CAPS
Under the RBI Master Directions on Financial Services, a commercial bank cannot invest more than 10% of its paid-up capital and reserves in a single financial subsidiary, capped at an aggregate 20% across all subsidiaries.
With IDBI’s net worth at ~₹61,164 Cr, the aggregate statutory ceiling sits around ₹12,000–₹12,500 Cr. Pumping out ~₹28,300 Cr in cash directly breaches these prudential limits unless Mint Street grants unprecedented regulatory waivers.
2️⃣ SEBI'S "MAJORITY OF THE MINORITY" FIREWALL
Once Fairfax assumes 60.72% ownership, it becomes a promoter. Shifting promoter-owned assets into a listed bank for cash triggers SEBI LODR Material Related Party Transaction (RPT) rules.
Fairfax is statutorily barred from voting. The decision falls squarely on the minority shareholders—where GoI (15%) and LIC (19%) hold the decisive votes.
Can state institutions justify draining the bank's liquidity for promoter assets?
3️⃣ VALUATION ASYMMETRY ON PUBLICLY FUNDED CAPITAL
IDBI’s stellar 27.10% Capital Adequacy Ratio is not private windfall—it was rebuilt through ~$6.4B in sovereign recapitalization and LIC policyholder funds to rescue the bank from PCA restrictions.
Buying IDBI cheap at ₹81, while vendoring in unlisted, non-market-discovered entities like Go Digit Life at internal valuations, creates a clear conflict of fiduciary duty under Section 166 of the Companies Act.
4️⃣ THE DUAL-BANKING PROMOTER CONFLICT
Fairfax already holds ~40% in CSB Bank. RBI promoter guidelines explicitly restrict a single conglomerate from controlling multiple universal banking licences without an ironclad, time-bound divestment or merger roadmap.
Capital efficiency through bancassurance synergies is sound business logic, but extracting bank cash to fund promoter buyouts sets a dangerous precedent for Indian disinvestment.
Without strict RBI scrutiny and an arm’s-length share swap rather than a cash drain, this deal risks becoming a textbook case of sovereign capital being privatized to subsidize its own acquisition.
#IDBIBank #FairfaxGoBack