Capital is moving to new rails. Fund operations shouldn't have to.
Tahoe gives fund managers the infrastructure to run subscriptions, redemptions, investor reporting, and NAV workflows across any rail.
One fund, any rail.
Your investors have a short list of questions before they put money into a private lending fund.
Who audits the fund? Does a third party administrator work on it? What is the fund's record on defaults? How open is the manager with investors?
@MHaas2020 Point 4 is the interesting one. When an equity shop moves into credit, the investor side changes too. Regular income goes out, not one check at exit.
Some investors want to fund in stablecoin. Others only send a bank transfer. One fund can offer both, and either way the investor signs in to the fund's own portal. Does your fund need both? See how Tahoe handles it at https://t.co/UeIHN2aOv5
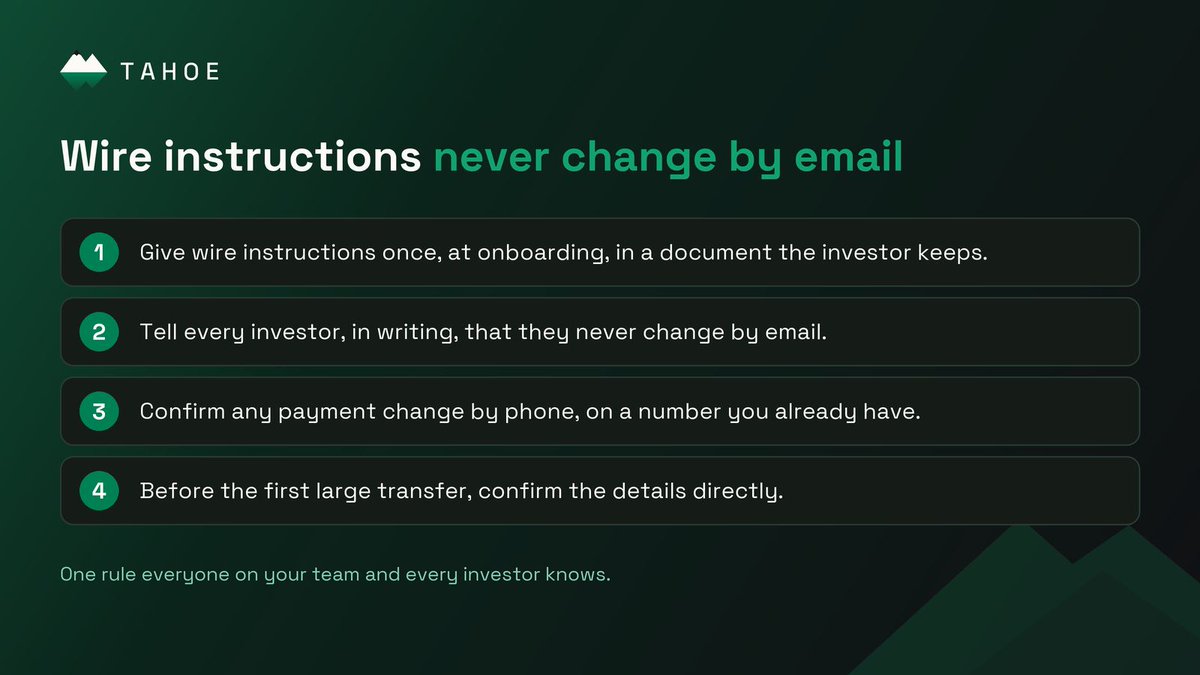
An email says your fund's wire details changed. It could be fraud.
Give wire instructions once, at onboarding, in a document the investor keeps. Confirm any payment change by phone, on a number you already have.
Who tells your investors?
@EarnestSweat The letter is the one place a GP has to put the numbers next to the story. Did she say what separates the letters she actually reads from the ones she skims?
@hajekd The small stuff is the tell. When last quarter's closing numbers don't match this quarter's opening ones, the polished commentary stops landing. What's the first red flag you look for?
Trust is the whole business in a fund. Many small funds keep the record in a spreadsheet.
We built Tahoe so each share is represented on a shared ledger, beside your administrator's books.
Would your investors trust that more?
@NoCapCapitalLLC The real ones ask boring questions first, like who controls the bank account and how you report. The "no risk" crowd skips straight to the upside.
@wealth_mgmt Fast growth in semi liquid funds shows up in ops first. Every month brings more subscriptions to process, and every quarter more redemption requests to handle.
@megzenger Activity based. LP count alone changes the math: 40 LPs in one fund is a quiet quarter, while 400 across a few SPVs means hundreds of notices, statements and questions every cycle.
@PE_Insights Evergreen venture is a hard ops problem. Money can come in often, but the portfolio gets valued quarterly at best, so how the entry price is set is the first thing investors will ask about.
@tasniahuque Agree on the slide marathon. Sending the fund numbers a week ahead lets LPs show up with their questions, so the room can stay on the founders.