They say that most amateur tennis matches are lost, not won. I.e., it isn't about hitting winners but about avoiding mistakes. Just keep returning the ball and it will work out.
I think that's more true in investing than many of us want to admit.
I think most of the FOMC participants are at this point “Warsh-pilled.”
From Wong-Webster dictionary;
Warsh-pilled (adj.) — So provoked by Kevin Warsh’s florid, substance-free rhetoric that you start taking the other side of whatever he says, regardless of what the data show.
On one hand, stay the course is generally what individual investors should do.
OTOH, most advisors who blithely tell their clients to "stay the course" just don't know what else to say.
@tracyalloway We don't use Chinese models but use open weight heavily.
If you can build an AI process using Claude/ChatGPT, but then use any open model for the ongoing implementation, I do think that shifts the economics. Open weight is arguably the most commodified segment of the AI space.
@SteveMatthews12 Idk Steve... I can't recall a time when a sitting governor made statements this diametrically opposed to the Chair.
That is of course unless you count Warsh himself just after he resigned.
I don't know how to read this other than Waller openly revolting against Warsh's communication strategy. He's literally saying "we should do forward guidance."
The family fight is spilling out into the street with the whole neighborhood watching.
https://t.co/J8pa3BxGlW
I couldn't agree more with Nick here. This is what Warsh seems to not understand. If you give clear guidance, you can afford to take more deliberate action. If you refuse to give guidance, you have to act sooner. Your actions do all the talking.
There’s a broader point here beyond December tactics. Imagine no dot plot, no rate projection in the SEP, maybe no press conference, and no balance-of-risks language in the statement. That’s roughly the pre-1999 Greenspan setup.
In that world, words can’t do the work of action, because you’ve stopped using words that way. You have to act.
The implication of what Waller is saying here is if the committee is truly putting away the communication tools it built over two decades, a 25 followed by silence about what comes next is inadequate.
IMO two things can be true.
1) NVDA supplies a lot of vendor financing, without which the AI ecosystem might be wildly different.
2) The Jensen scandal shouldn't change any of that.
If NVDA stops financing GPU buys, it won't be because the CEO changed.
This whole idea of $NVDA as the "central bank of AI" is a little too cute IMO. There are other big players with plenty of cash, either from revenue or investors.
But for the challenger firms. The non-incumbents. For the neolabs and neoclouds, NVDA's role seems quite significant.
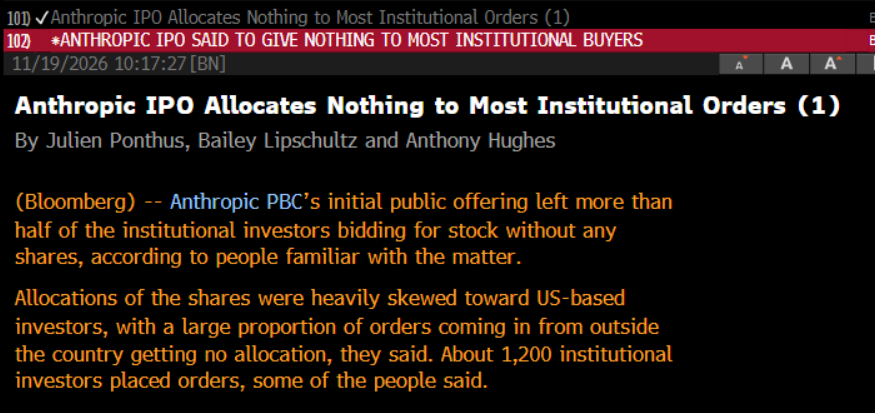
The risk was never that $ANT IPO wouldn't be oversubscribed. Of course there is demand.
The risk is that public company pressure changes how they spend.
That's a story that plays out over months and quarters, not just one transaction.
https://t.co/FUUvyrcjgJ
@aRishisays Also why Warsh completely eschewing forward guidance creates problems. He could have more or less promised a hike in December and more hikes if necessary.
Instead is makes us divine why in the world they didn't hike in October and question his resolve.
Waller went from 0.3% core inflation is the threshold for a skip vs 25bps hike in Sep; to 0.3% core inflation is the threshold for a 25bps hike vs 50bps hike in Dec, despite no major surprises in inflation in 2H 2026.
Perfect example of how underreacting to inflation forces central banks to overreact later!
This is why I always thought it made sense to be short FFG7 to own the optionality (50 or consecutive 25s). I do think we’ll get 25bps in Dec, with
1. dovish guidance (one or none hikes) if equities in a deep correction and oil around 80 because this will revise projections for 2027 lower
2. hawkish guidance (two or more hikes) if things stabilize here or improve.
The bar for any other outcome is incredibly high!
I find this statement to be absolutely incredible.
At the October meeting, you vote to not hike.
Then there is a very modest beat on CPI and suddenly we need to do 50bps?
I'm sorry, this isn't how monetary policy should be run. Should have hiked in October.
Waller says if you were to get a third straight 0.3% rise in core inflation for October, that's annualized inflation running at 3.5%. That lack of progress would be an argument for frontloading anticipated hikes: "You can't just keep sitting there and staring at it."