When ChatGPT launched in late 2022, the consensus inside China’s AI industry was that domestic labs were roughly two years behind on models, while export controls would leave China’s AI stack woefully incomplete.
Three and a half years later, that framing looks ... outdated.
DeepSeek and GLM forced a rethink of what was possible on the model building and also inference side. Meituan LongCat raises the same question for training.
None of this means China has caught up. Nvidia still has a massive manufacturing advantage, and US labs continue to lead in enterprise adoption, developer ecosystems and revenue.
But we do think the burden of proof has shifted.
The question is no longer simply whether China can build a frontier AI stack on domestic infrastructure. It’s how quickly that stack improves from here.
For the longer version of this argument:
- WeChat’s native AI assistant Xiaowei began expanding gray-scale testing on June 20. It (Jun 2026)
https://t.co/bPDmLXC3wt
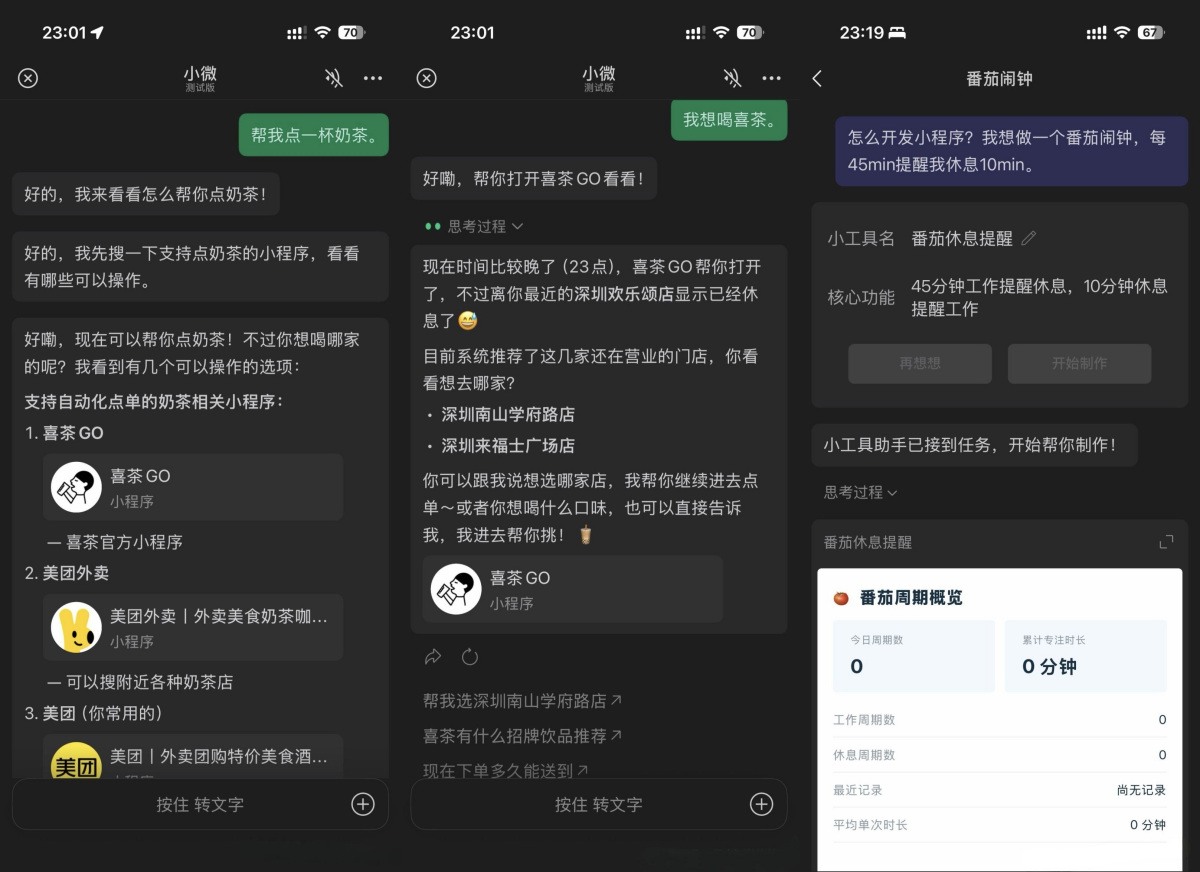
WeChat’s native AI assistant Xiaowei began expanding gray-scale testing on June 20. It appears as a new robot icon in the top-left corner of the main WeChat app. Users can use text or voice to search, generate images, set reminders, recommend music, access WeChat features, and use mini-programs. One notable feature lets users generate a mini-program from a simple prompt, although the resulting apps are currently limited to personal use and cannot be shared.
More than the assistant itself, what stands out is Tencent’s approach. Rather than building a separate AI app, Tencent is embedding AI directly into WeChat. Xiaowei can access WeChat’s 4M+ mini-program ecosystem and connects to the AI Exclusive Card that WeChat Pay recently introduced for AI agent payments. Earlier this month, Tencent also released tools that allow WeChat AI to interact with mini-programs on behalf of users.
The strategy is straightforward: keep users inside WeChat from request to transaction. If successful, Tencent strengthens its position at the center of discovery, services, and payments. Partners such as Meituan and JD gain access to users but may become increasingly dependent on Tencent to surface their services.
It’s still early. Access remains limited, and the mini-program generation feature is restricted to personal use. Tencent also tried Xiaowei before, nearly a decade ago, without much success. The bigger question is whether people actually want AI to sit between them and the apps they use every day.
$700.HK $TCEHY
WeChat's in-app AI assistant Xiaowei hit 30 million daily active users, the company said on November 18, as testing widened into chats, Moments, official accounts and Channels.
Xiaowei runs on WeLM, a custom model Tencent says it tuned for cost efficiency. WeChat expects some inference to move onto user devices later, which would cut server costs further.
WeChat calls Xiaowei a personal assistant for everyone, usable inside the WeChat ecosystem. Privacy protection was built in from the design stage, and usage and operating costs are low. WeLM's tuning keeps inference costs very low and still falling, the company says.
Xiaowei builds agent capabilities on the ecosystem, including payments and mini-program services. WeChat says it will not conflict with the interests of mini-program service providers. On commercialization, WeChat says Xiaowei will multiply its commercialization capabilities, though it gave no figures in the announcement.
Our read: the 30 million DAU matters less than the cost line. A custom model plus a path to on-device inference is how WeChat can put an assistant in front of 1.4 billion users without paying for every query.
Alibaba's September-quarter revenue rose 10% to RMB 271.52 billion. Adjusted net profit of RMB 19.91 billion came in well below the RMB 26.61 billion analysts expected, and adjusted EPS of RMB 8.10 missed the RMB 10.75 estimate.
Cloud external recurring revenue growth accelerated to 67%, and AI product revenue grew triple digits for a thirteenth straight quarter. The company also pushed out a full stack of upgrades this quarter, from its own AI chips and supernode architecture to agent-native cloud infrastructure. That includes a new-generation AI chip, Zhenwu V900, from T-Head.
The profit miss sits next to a cloud number that keeps accelerating, and we doubt that is demand softening. E-commerce adjusted EBITA rose 243% year on year, and instant retail kept its share while losses narrowed sharply, which is where a good chunk of the spending went.
$BABA
The food delivery subsidy war is over. Meituan, Alibaba, and JD are now competing over who organizes supply.
All three moved in early November. JD's local services head left, and its delivery arm pivoted to "supply chain innovation." Taobao Flash launched a high-end home dining pilot in Beijing, covering 6 brands and 18 stores. Meituan promoted two VPs to run healthcare and commercial monetization.
UBS estimated March daily orders at 62M for Meituan, 52M for Taobao Flash, and 8M for JD. From Q2 2025 to Q1 2026, the three lost about RMB 173B (~$24B) combined. Meituan's per-order economics went from roughly -RMB 1 (~$0.14) to +RMB 0.16 (~$0.02) between Q1 and Q2 2026. JD relies more on full-time riders, so its per-order costs stay higher.
The new battleground is kitchens and warehouses. Meituan's raccoon canteens target 1,200 locations in three years. Alibaba's Hema plans over 1,000 front warehouses by year-end. JD's 7Fresh combines store and warehouse to cut costs.
We're not convinced any of these models scales quickly without giving up quality or margin, because subsidies can buy orders but they can't make each delivery cheaper to fulfill.
$MPNGY
h/t @TMTPostGlobal
Baidu's AI revenue passes half its total, stock still sinks
Baidu's AI revenue topped 53% of the total for the first time. The stock hit a new low anyway, on investor worry that Baidu is mostly subsidizing compute costs.
We'd be careful with the mix number on its own. If compute bills eat most of that AI revenue, passing half changes what Baidu is on paper rather than what it earns. The milestone is a cost line moving up the income statement.
Huawei Cloud opens its first embodied world model
Huawei Cloud released CloudRobo-WM1.2 on November 16, its first Ascend-native embodied world model. It says it will open the weights, post-training code and pretraining recipes on November 30. The model tops RoboTwin 2.0 and LiberoPro 2.0. Huawei also claims 80% of Chinese embodied-AI companies use Ascend Cloud, a self-reported ecosystem penetration figure, not third-party revenue share.
The design detail worth keeping is DualAct: one world-model brain with two action paths, a fast reflex route and a slower expert route. Customers can also pick among four inference modes, trading compute and latency against each other. We doubt the benchmark wins are what sells this. The elastic modes are the pitch, because they admit deployment cost, not model quality, is what gates industrial scale, and open weights are how Huawei buys developers for Ascend.
H/t @Chinazhidx
A few earlier TBC pieces are useful context:
- Alibaba's May 13 earnings for the March 2026 quarter offered a useful look at the econo (Jun 2026)
https://t.co/PGF8rLOSB0
- Baidu has just streamlined its job classification system, merging technical and managem (Apr 2026)
https://t.co/Y0XolZx0Q7
- The five TBC posts that traveled furthest this week all circled the same hard question (Aug 2026)
https://t.co/AvkTPwpckK
Alibaba's May 13 earnings for the March 2026 quarter offered a useful look at the economics of the AI transition.
Cloud revenue grew 38% year-on-year, while AI-related product revenue posted its eleventh consecutive quarter of triple-digit growth. Alibaba says its AI business is now approaching an annualized revenue run rate of RMB 40 billion.
What's equally notable is the cost side. Capital expenditures have risen to roughly RMB 120 billion, while profits have come under pressure. At least for now, Alibaba's AI business looks less like a traditional software business with expanding margins and more like an infrastructure business requiring sustained investment.
When we wrote about China's AI chip market earlier this year, one observation was that the competitive focus had shifted from peak benchmark performance to delivery continuity, ecosystem depth, and long-term control of the stack. Alibaba's recent results suggest it is pursuing exactly that strategy: developing in-house chips through Pingtouge, building a large model ecosystem around Tongyi Qianwen, and leveraging an enterprise footprint that reportedly reaches around 63% of China's A-share listed companies.
The strategic value may not be the model itself, but the infrastructure layer underneath it. Once an enterprise fine-tunes models, builds workflows, and deploys applications on Alibaba's platform, future iterations, scaling, and optimization become increasingly tied to Alibaba's cloud and AI services.
One way to interpret the revenue growth is that enterprises are moving from buying software licenses to purchasing AI capabilities and compute consumption. If that trend continues, the companies that own the underlying infrastructure may capture a disproportionate share of the value created by AI adoption.
$BABA
Baidu's AI cloud is now half its core revenue
Baidu's Q3 revenue fell 1% year over year to RMB 30.8 billion. AI-driven business brought in RMB 13.2 billion, or 53% of general business revenue, the third straight quarter above 50%. AI cloud infrastructure did most of the work: RMB 8.2 billion, up 94% year over year, with GPU cloud revenue up 191%.
Traditional search and feed advertising fell 24% to RMB 9.4 billion. AI native marketing services dropped 15% to RMB 2.4 billion, which Baidu attributes to prioritizing user experience over monetization during its AI search transition. AI application revenue was flat at RMB 2.6 billion.
We doubt the 53% AI share means the application layer is carrying the company yet. Baidu is converting GPU demand into revenue, but the three largest GPU cloud customers renewed multi-year contracts, the longest at six years, which tells you where the recurring money sits. CEO Robin Li also said Kunlunxin secretly filed for an IPO earlier this year.
$9888.HK
h/t @Chinazhidx
Tencent's executive office is telling managers to get out of the way of AI-driven org change.
Earlier TBC coverage framed this one: that is not normal.
Tencent's Executive Office Says AI Should Thin the Ranks
Tencent's executive office (总办) is arguing that AI-driven reorganization means fewer management roles are needed. It warns that middle managers who guard territory and resist change will block progress.
We doubt the warning is aimed at Tencent's own layers alone. A company that expects AI to flatten its org chart is also telling the managers who would have to carry out that flattening that they are the obstacle.
Earlier TBC coverage frames this one.
The archive has a few angles on this story:
- ByteDance raised the internal repurchase price of employee-held “Doubao shares” from $1 (Jun 2026)
https://t.co/OYpWtfgBpP
- ByteDance is negotiating a roughly $20 billion overseas loan, the largest offshore fina (Jun 2026)
https://t.co/1K9fs8VJai
ByteDance raised the internal repurchase price of employee-held “Doubao shares” from $13.08 to $14.85 in just two months, a gain of 13.5% and 48.5% above the original $10 grant price. Over the same period, ByteDance’s broader employee stock buyback price increased only 2.63%, from $229.5 to $235.5. The gap suggests ByteDance is increasingly treating Doubao as a standalone business with its own performance incentives and talent retention strategy.
Doubao’s paid plans are now public: 68 RMB/month ($9) for Basic, 200 RMB/month ($28) for Enhanced, and 500 RMB/month ($70) for Pro, with annual plans reaching 5,088 RMB ($708). But subscriptions alone are unlikely to move the needle. Based on previously disclosed figures, Doubao generates less than $1 million in daily revenue while incurring more than $10 million in daily costs.
The bigger story is infrastructure spending. ByteDance reportedly increased its 2026 AI capex budget from 150 billion RMB ($20.9 billion) to 200 billion RMB ($27.8 billion), with some reports later referencing as much as $70 billion in total AI infrastructure investment. The company is also said to be pre-purchasing more than $50 billion worth of domestic AI chips, including Huawei Ascend and Cambricon hardware, alongside 50,000 inference chips from Tianshu Zhixin. This is a scale strategy, not a subscription business strategy.
The paid tiers appear less about immediate monetization and more about user segmentation. Free users help build habit and distribution, while paid plans target developers, researchers, and other power users who need stronger models and larger usage quotas. With its infrastructure budget, ByteDance can afford to subsidize premium AI services at a level many competitors cannot.
The separate “Doubao shares” program also gives employees a direct stake in Doubao’s performance rather than ByteDance’s overall results, increasing internal pressure to improve the product.
The challenge is that Doubao still trails competitors such as DeepSeek, Kimi, and Zhipu in reputation, particularly for coding. ByteDance is betting that scale, distribution, and investment can narrow that gap before rivals build enough paid-user loyalty to make switching difficult. Whether that works will depend on how quickly Doubao’s capabilities improve.
h/t @TMTPostGlobal
ByteDance Puts a $400B Price on Its Own Stock
ByteDance told investors it plans a new $6 billion share buyback at $241.35 a share. That price implies a $400 billion valuation, 20% above its buyback a year earlier, per The Information via Bloomberg on November 13.
The same letter pushes the deadline for an IPO, or a right for outside shareholders to sell their full stakes, out four years to December 11, 2030. The buyback hands staff and early holders cash without a listing. The new deadline keeps ByteDance, not investors, in charge of when anyone can exit.
It also describes a plan to grant AI staff 300 million shares tied to the value of the AI business. That pays frontier-lab money without repricing the whole company. Our read: the retention tool becomes the thing employees are stuck holding if the internal mark stops climbing 20% a year.
Baidu's ERNIE 5.5 Flash Preview took first on two of eight benchmarks on November 11, ahead of Claude Opus 5.5 on AutomationBench and SpreadsheetBench V2. Those are Baidu's own scores, and Baidu calls it a mid-training version that may still have gaps.
The price is the sharper number: RMB 2 (~$0.28) per million input tokens and RMB 8 (~$1) output at busy hours, currently half off. Weights go out under Apache 2.0 by November 25, which reverses Li Yanhong's 2024 line that open models would fall behind. Baidu is buying its way back into the first tier with price and open weights, not a clear capability lead. We would be careful about reading two self-reported wins as a durable position.
$9888.HK
h/t @TMTPostGlobal
We've been circling this from a few angles:
- The Month China Closed the AI Stack (Jul 2026)
https://t.co/kqtecU0asR
- Tencent's AI Bet Is Not a Chatbot. It Is WeChat as an Action Layer (Jun 2026)
https://t.co/FHuIVu8pE8
Baidu says its internal agent count went from 5,000 to 37,000 in a year, and effective weekly work tasks from 84,000 to over 1 million. Li Yanhong put those numbers on screen at Baidu World on November 12. His argument: AI's next phase is the "intelligent organization," agents and digital employees inside real business processes rather than chat windows.
The model news got the headlines. ERNIE 5.5 Flash Preview has 280B total parameters, 14B active, and a million-token context, and Baidu also released an 800B-parameter deep-reasoning application model that previously served Baidu Search. Sun Tianxiang, the post-95 head of Baidu's foundation model unit, presented them in his first public appearance. The demo was a 116-second 2D short, written from scratch in Python, of a pelican on a bicycle riding through 20 art styles.
The parameter count is not the number to watch. It's the 88.2% first-pass acceptance rate Baidu reports for Baidu Dazi on long multi-system tasks over 15 steps, up from 67.6%, which decides whether agents save labor or just create review work. Baidu also cited a materials firm that cut weekly procurement from 10 people and 100 hours to 2 people under an hour.
The hardware is being sized for that load. Baidu's Tianchi 1024-card supernode, shipping next year, is built for 5-trillion-parameter training, with Baidu claiming 3x inference performance and 90% lower first-token latency on cache-hit multi-turn chats. Kunlunxin's M-architecture chips arrive this year and next, N-architecture in 2028.
We doubt the constraint on the intelligent organization is model capability now. It's whether enterprises can absorb 37,000 agents without drowning in them, and Li's answer that jobs converge into builders and sellers is a cleaner story than a plan.
$9888.HK
h/t @Chinazhidx
Tencent Yuanbao's search lead, Li Ruizhang, sat for an interview on whether web search still has a place in the AI era and how AI-native search gets built.
We doubt the interesting question is whether search survives. It's who owns retrieval once answers replace links, and a search lead doing this interview suggests Tencent wants that layer inside Yuanbao rather than handed to a partner.
Tencent launched Yuanbao Search on November 11 as a standalone consumer product, reachable through its own site and a QQ Browser entry. The retrieval stack behind it was opened to enterprises and developers on October 20 via API, MCP and Skill. Tencent describes that base as a hundred-billion-scale index with 157 authoritative sources across 13 verticals. Consumer and enterprise products share it but are sold separately.
The WeChat channel is the most concrete differentiator. In Zhidx's hands-on test, a search for Tianjin civil service exam surfaced a 2027 recruitment notice posted that same day in the official-account channel. The video channel's first screen was all clips labeled a year old, with some off-platform content mixed in. Zhidx also found official-account links that would not open and a slow-updating content library, so the ecosystem advantage is real but uneven across formats.
Product lead Li Ruizhang said Yuanbao Search is not opposed to advertising, and will rely on clear ad labeling, limited formats, a collapse button and tighter relevance. In testing, commercial keywords like omeprazole returned no obvious ad slots; an ad appeared on the civil service query, small and collapsible. Li also said the product will keep adding features but will not evolve into an AI assistant.
We doubt Tencent is trying to win search on index size, where it is late. It is trying to win on source trust and WeChat exclusivity. The ad restraint is the price of training users to treat this as a reference tool rather than a shopping entry. That works only if the freshness gap between official accounts and video closes, because otherwise the authority pitch is undercut by the product's own results page.
H/t @Chinazhidx