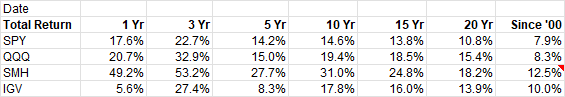Happy belated 4th.
My occasional reminder that the best gift you can give yourself and everyone around you is the awareness of index ETFs.
99% of investors cannot beat these incredible ETFs that provide exposure to the best companies in the strongest economy in the world, automatically rebalance to add winners / remove losers, can be held forever, and require you to pay little to no taxes.
SPY: 13.8% compound return over 15 years. Up 11% YTD. Trades at 21x forward P/E vs 10 year mean of 20x. Average of 9% EPS growth over past 10 years. (If you want the SP500, buy VOO which has lower fees instead of SPY).
QQQ (Nasdaq 100): 18.5% compound return over 15 years. Up 18% YTD. Trades at 24x forward P/E vs 10 year mean of 25x. Average of 13% EPS growth over past 10 years.
SMH (Semi's): 24.8% compound return over 15 years. Up 71% YTD. Trades at 25x forward P/E vs 10 year mean of 20x. Average of 22% EPS growth over past 10 years.
IGV (Software): 16.0% compound return over 15 years. Down -12% YTD. Trades at 20x forward P/E vs 10 year mean of 35x. Keep in mind this EPS also is a blend of consensus so excludes plenty of SBC depending on the company (just saying despite the SaaS-pocalypse, the group doesn't stand out as "cheap"). Average of 12% EPS growth over past 10 years.
Think about that for a second. You can own QQQ which is America's best tech companies (and the world buys American tech) for 24x EPS or a 4.2% yield on NTM that goes to a 4.7% yield on Y+1 to a 5.3% yield on Y+2, ... And you regularly get to buy QQQ at 20x or a 5.0% yield that increases over time. To me, that's a shockingly good deal compared to a risk-free rate that pays you in devaluing USD and is taxed.
It's kind of remarkable that vehicles that have provided better returns than 99% of the active management industry (and 100% of the industry on an after-tax basis) with pretty digestible downside volatility aren't at least 50% of everyone's portfolios.
I guess there is no face to these vehicles out there promoting them non-stop and no fees to feed an eco-system of advisors / marketers / etc.
Anyways, I just encourage people to actively think about VOO / QQQ. Have you outperformed it over 20 years on an after-tax basis? Have your fund managers? ...
Great thoughts. Thx.
Curious if you have thoughts on the concern that there are now 5 players spending half their AI compute budgets on training more or less the same AGI model. So arguably half the spend is duplicative investment.
And that the models already seem pretty good for most things so maybe a rationalization post-AGI leads to a glut that isn’t far off.
@stockswithsanj I suppose that might then suggest ad potential on Muse is real. I wouldn’t mind seeing ads for other dress shoes - even if they don’t meet the criteria which Muse is using for its search.
3 random thoughts on $META
1) Re: The Cheeky Pint podcast - It's kind of crazy they admitted that their AI buildout is a huge bet that will have "very, very, very bad" financial consequences if it doesn't work out. Especially bc monetization is likely far into the future so doesn't that suggest 2027 potentially sees material EPS headwinds as the depreciation comes online?
I get it. There isn't a way to be competitive in AI w/o making big infra bets and I'm sure they were excited in the moment about Muse success. But certainly pulled the curtain back a bit...
2) Muse is great. I get a monthly note on all local events in my area (sports, music, theater, restaurants, etc.). I paid two parking tickets with it. And I have it looking for a new pair of dress shoes and a PS5 Pro (we haven't found either to my liking so the search continues).
But I'm not sure what else to do with it so I haven't checked the app much after that.
3) I assume the Muse data will be added to the knowledge graph. That's interesting bc now META knows far more about me and my ongoing searches. I would think that has to improve targeting / pricing on core META properties.
As opposed to just showing me general products that match my interests / pixel data, they now know that I am in need of new dress shoes on an ongoing basis since the search is still outstanding - and I would think advertisers that have shoes exactly like or even adjacent to what I'm looking for would want to target me on FB / IG.
Anyways, the thought is maybe monetization of Muse actually first shows up as higher monetization of core META.
Ok, it might be over folks.
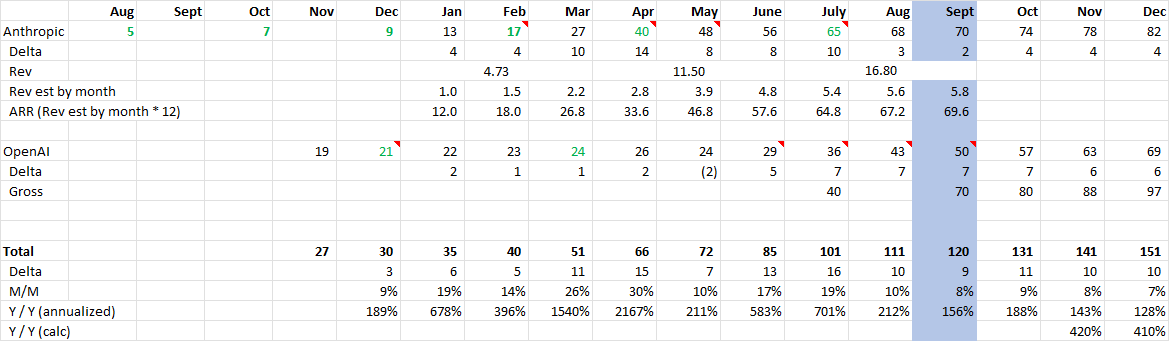
Anthropic revenue disclosure maps to ~5.8b in September revenue or 70b ARR which means August / September only increased by 2-3b ARR in each month.
[There is no way that ARR is calculated using last day of the month as that would be more aggressive than anything I've ever seen out of companies this size (exception: Musk).]
Worst monthly numbers by far this year. (Maybe some self-infliction from cleaning up distillation?).
My rough math indicates OAI / ANT ARR monthly add softened from 16b in July to 10b in Aug to 9b in Sept. That is no bueno...
Supportive of the view that either CAPEX is getting cut or pricing is going to weaken substantially.
@jukan05 This exchange:
Analyst "So, should we expect a re-accel to maybe 100-110b by year-end"
Anthropic CFO: "We aren't commenting on forward looking figures but believe in a large opportunity over time"
Analyst "Got it" [Writes down "management didn't talk me down from 110b"].
Dumb question but what's the advantage of $META having spent 100b+ to develop their own model under Muse, as opposed to having kept that money and just built Muse with whatever model gets the job done?
@RHouseResearch I'm not meeting with Anthropic today so I don't know - but I would have to imagine that if that explanation is significant, it is definitely being discussed.
Because otherwise the M/M growth implies a dramatic slowdown.
Thx for the thoughts.
I think the pushback would be great models are available from 5-10 players who have been neck and neck forever, so seems like inference margins will be quite low over time (although I hear your point that this isn't a certainty), and that LLMs don't seem to present a distribution threat for now.
@Networthknowing I'd say that's a strong point if there was only 1-2 labs w/ good AI. But there are plenty of them to make sure LLMs are available at great quality / price specs.