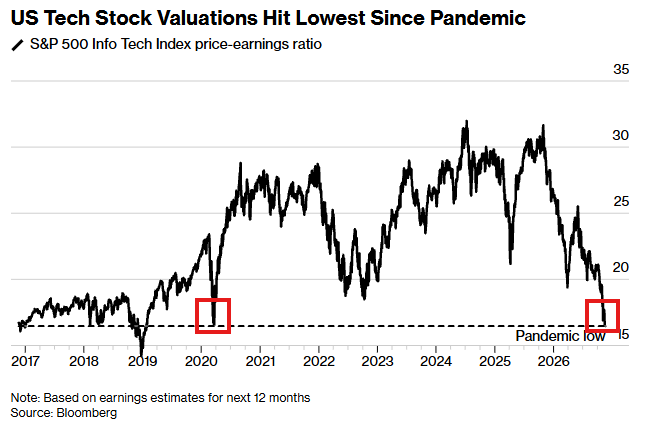
BREAKING: US technology stock valuations have hit their lowest level since March 2020 amid the market correction.
The S&P 500 Info Tech Index P/E ratio is now at its lowest since March 20th, 2020, at 16.4x.
It's clear now more than ever:
Ultimately, this bear market in tech stocks will be remembered as the best buying opportunity of the last decade.
Unless your view is that the AI is worthless and the AI Revolution is over, many key parts of this market are extremely cheap.
Democrats will be more friendly to AI than expected, Nvidia will survive its leadership crisis, and concerns around CapEx and free cash flow will prove to be overblown.
To top it off, current sentiment is as if the market has just gone through another 2008, all while the S&P 500 is posting +32% earnings growth.
The comments on this post will show you just how polarized sentiment has become in the direction "bubble" callers.
Fear creates an investor's biggest opportunity.
Bookmark this post.
@XYZalerts@michaeljburry Big overreaction. Nothing has changed fundamentally about nebius or the economy or the AI trade. Just market perception and scared investors. You’re proving that lol
@NebiusAllin Have a little patience 😂😂😂 markets been down for what, a month/two months. Just wait it out. Stop checking the chart if it bothers you so much
$NBIS
Nvidia's release tonight named five clouds already running Vera Rubin NVL72 racks: CoreWeave, Google Cloud, Microsoft Azure, Oracle Cloud and Nebius.
Nebius is also on the list building with Vera CPUs.
Two neoclouds next to three hyperscalers.
$NBIS
Nobody has to marry a stock. But the bull case already accounts for credit, capex and the tape, so here it is with the numbers.
Credit and capex:
• 2027 capex is $40-45B. Prepayments ($17-20B expected) plus asset-backed debt on $40B+ of investment-grade contracts cover 75-85% of it. Over 90% of Q3 contract value came prepaid, covering more than 100% of the capex behind it
• That leaves ~$6-11B to fund (my math). ClickHouse alone covers most of it: Nebius's ~27% is ~$4B at January's Series D and ~$15B at Clarity's ~$295
• Lenders haven't walked. Citi wrote a $3.5B facility at SOFR+2.75% days after CoreWeave's unsecured bonds blew out past 15% in October. Equity went out at ~$225 on average this year (my math), and debt was $14.2B against $7.4B of cash at Sept 30
What the capex buys:
• More than 1 GW in 2027, over half on owned sites, with all power and components secured. Q3 deals priced above $25M per MW and pay back in 19 months
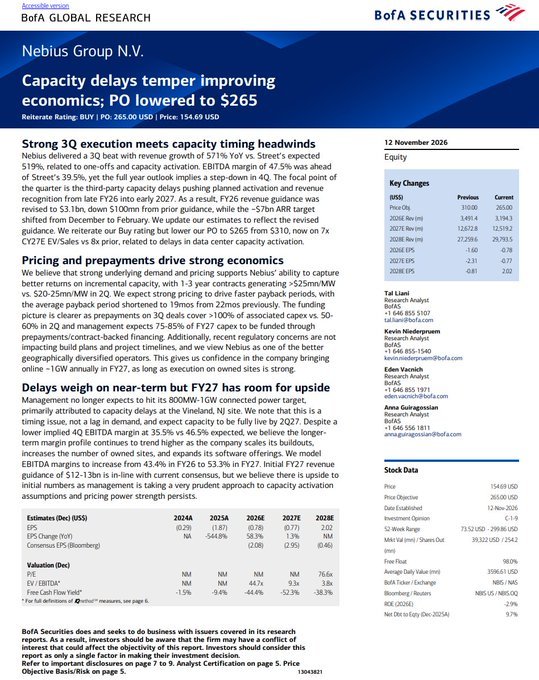
• 2028 revenue: February's >$7B of ARR plus 1 GW at Q3 pricing is ~$32B (my math). BofA, after cutting its target, models $29.8B
• Margins: BofA has adj. EBITDA going from 43.4% this year to 53.3% in 2027, and its own valuation table implies ~55% in 2028 (my math). That's ~$16-18B of 2028 EBITDA
• Today's ~$36B market cap plus ~$35B of net debt by end-2027 is ~4x that. At 7x it's ~$255-280 a share by end-2027, before ClickHouse, Avride, Toloka or Token Factory (my math)
The tape:
• Brutal, $236 to $116 since Sept 30, with two-thirds of it before the print. The estimates went the other way. BofA raised 2028 revenue by $2.5B, 2027 EPS from -$2.31 to -$0.77 and 2028 EPS from -$0.81 to $2.02, then cut its target from $310 to $265 by lowering the multiple. That's the tape repricing better numbers, and it's why I ignore price targets, $300 ones included
"Russian Google":
• In context it's shorthand for the team. Arkady left Yandex with the international businesses and 1,000+ engineers who built its search, cloud and data centers. They design their own servers, build their own campuses and wrote their own cloud and inference stack. SemiAnalysis rated 77 GPU clouds in September and put two in Platinum, CoreWeave and Nebius, above Google Cloud, Oracle and Azure
• The same Yandex engineering produced ClickHouse, Avride and Toloka, and Nebius still owns stakes in all three
"Excellent team":
• ARR went from $1.25B in December to $6.4B in September, Microsoft and Meta signed, and Q3 adj. EBITDA margin came in at 47.5% vs. the Street's 39.5%. They missed the December ARR target by about two months because third-party sites slipped, which is why 2027 moves most new capacity onto sites they control
Skin in the game:
• Mine is at the bottom of every post. Nebius is my biggest position and I've held it through this entire drop, which is exactly why I post the math instead of slogans. Check any of it.
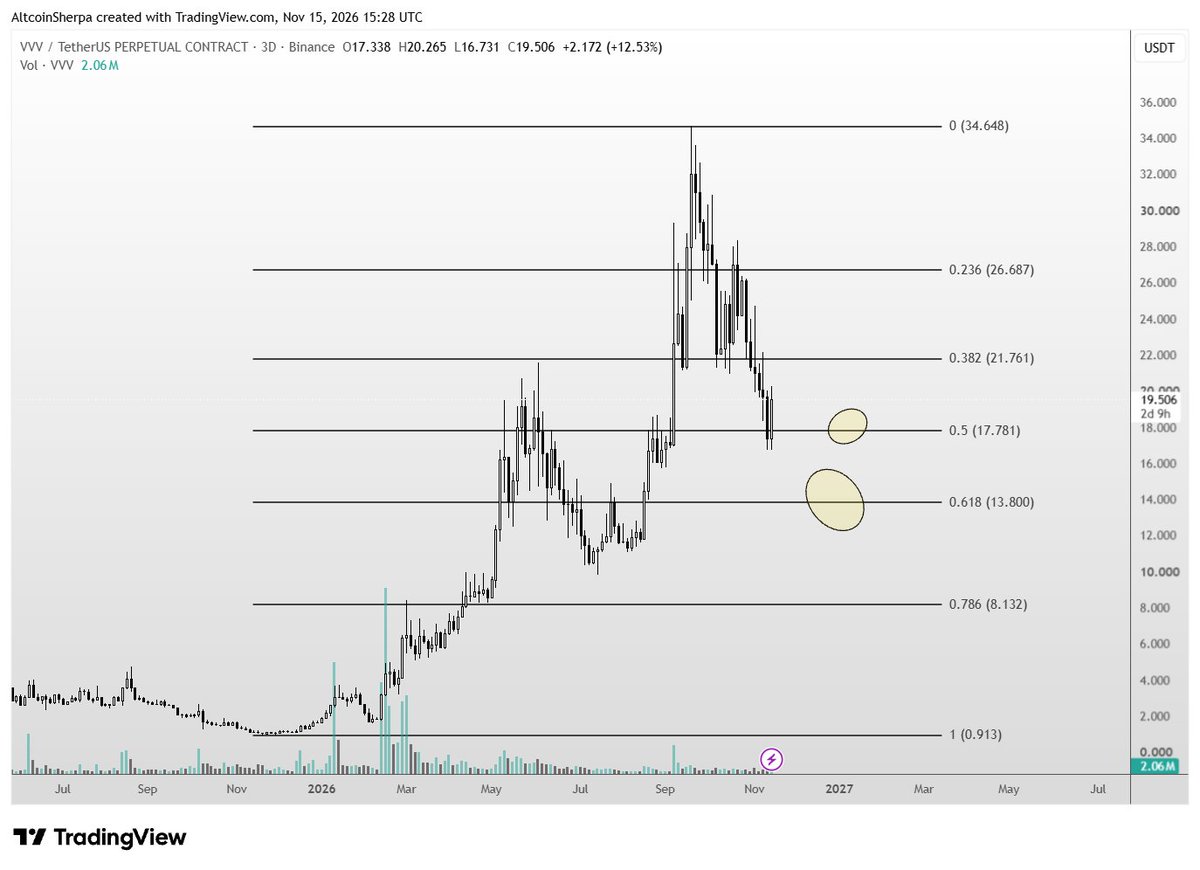
Could be dumb hopium but I strongly believe that many of these good altcoins will be trading significantly higher in the next 6-12 months from today. Coins like $NEAR $ENA $VVV aren't going to go away overnight. Yes, there will be short term volatility but if you have a long enough time horizon, these will still have good upside later.
@PlantInvestor16@Ben_Liquid1@daniel_koss This. I don’t think people realize how expensive it is to deliver. And I don’t think people realize compute will become the baseline for business/society to run, just like how internet is the baseline for business/society now