@cellamonett Sorry to hear that. If you're weighing your options, owning might be worth a look too: Calgary's apartment condo benchmark was $288,800 in October, down 7.9% from a year ago (CREB). Happy to help run the numbers. 🏡
@CdnMortgageNews Not surprising with so many renewing at higher rates. One simple step: you can usually start comparing renewal options about 4 months before your date, which leaves time to plan instead of just signing. 🏡
@GlobalCalgary Months of supply tells the same story: detached sat at just over 3 months in October, while row climbed to 4.4 (CREB). For buyers, that means more choice and more room to negotiate on townhomes and condos. 🏡
@danielfoch Fingers crossed it's practical. One mortgage-side tip for small business owners: lenders usually qualify you on the income you report, so plan with your accountant before you buy, not after. 🏡
Calgary's October numbers are in 📊 The benchmark price was $564,200, down just 0.4% from a year ago (CREB). Detached and semi-detached held steady, while row (-5.1%) and apartments (-7.9%) gave buyers more room. Thinking of buying this winter? Let's chat. 🏡
@hiscanada Ha! 😄 Same energy as the renewal letter that shows up with one rate and a signature line. Friendly reminder: the first offer isn't your only option, so compare before you sign. 🏡
@MoveSmartly@Dave_at_IMP Helpful explainer. For variable-rate borrowers, the hike has already flowed through: big-bank prime went from 4.45% to 4.70% on Oct 29. Fixed rates track the 5-year Government of Canada bond yield instead, so the two can move differently. 📈
@CMPmagazine Affordability is the key word. One Alberta difference that helps: there's no land transfer tax here, so registering the title on a $500K home costs about $550 in Land Titles fees, leaving more cash for the down payment. 🏡
@BagelPolling Very true. Even within Calgary it splits by property type: CREB's September numbers had detached prices only about 1% below a year earlier, while apartments saw most of the decline. Local data by property type beats national headlines. 📊
Myth: if you're self-employed, you can't get a mortgage. 🙅♀️ Fact: you can. Most lenders want about 2 years of tax returns and Notices of Assessment. Big write-offs can lower the income you qualify on, so plan with your accountant early. Questions? Let's chat. 🏡
@CdnMortgageNews Good to know for Laurentian customers. If your mortgage is part of the move, watch for letters about any changes to payment details, and treat your next renewal as a chance to compare options rather than auto-signing. 🏡
@SpecialSitsNews That's the national number, and it's very regional. In September, Calgary's benchmark price was down 0.8% from a year earlier (CREB) and Greater Edmonton's just 0.3% (RAE). Alberta looks very different from the national average. 📊
@BenRabidoux Oil cuts both ways out here in Alberta: lower prices ease the energy-driven inflation the BoC flagged, but they also weigh on our provincial economy. For variable-rate borrowers, that's why Dec 9 is one to watch closely. 🛢️🏡
@danielfoch Agreed, that's the number to watch. If rates stay higher for longer, the stress test matters more too: uninsured borrowers still qualify at the higher of their contract rate + 2% or 5.25% (OSFI). Worth knowing your qualifying number before you shop. 🏡
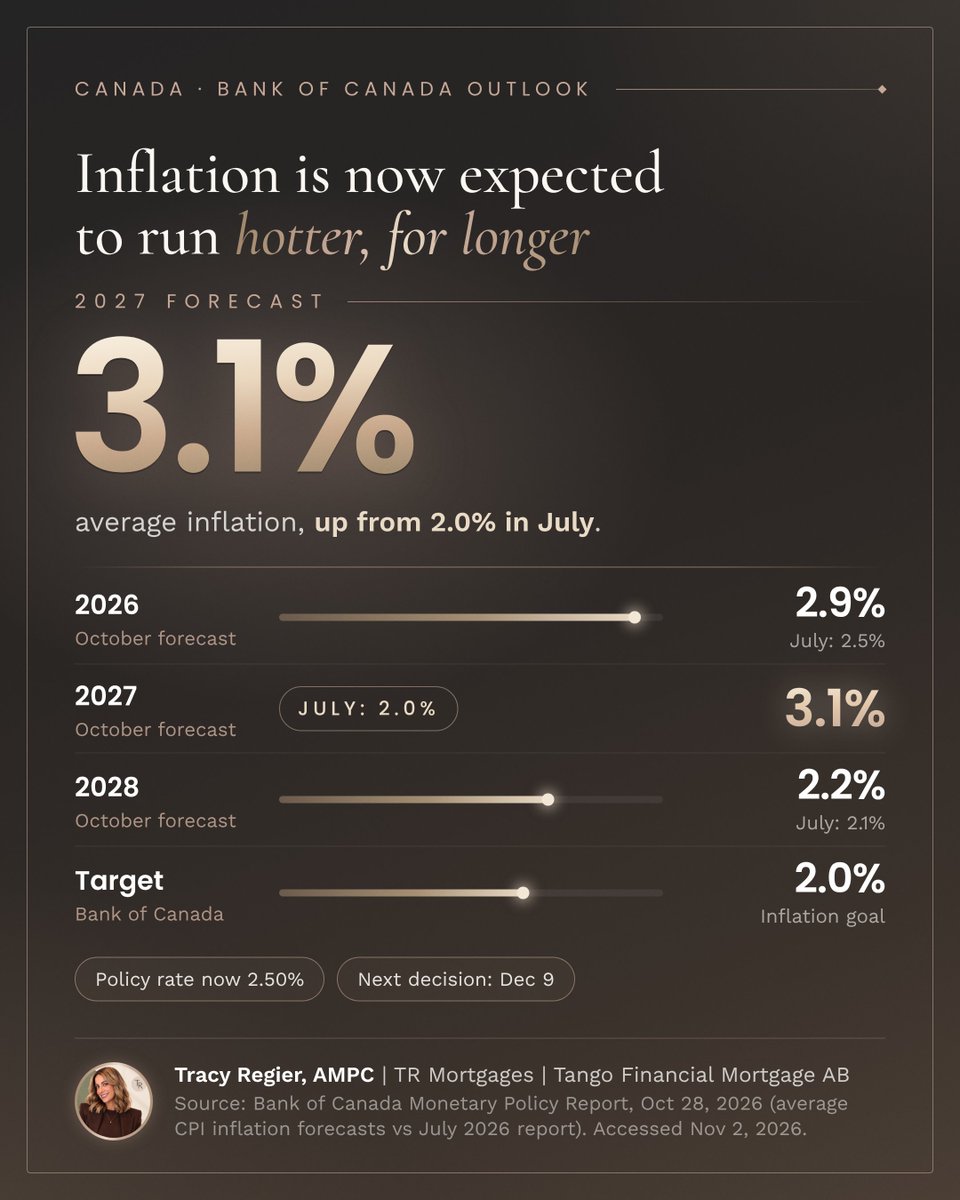
New Bank of Canada forecast 📊 Inflation averaging 3.1% in 2027, up from 2.0% in its July outlook (Oct 28 MPR). That could keep rates higher for longer than many hoped. Renewing or buying in the next year? Plan at today's rates, not hoped-for cuts. Let's chat. 🏡
@SecureMyOffer@MPelletierCIO It happens. A bigger deposit can strengthen an offer, but it doesn't reduce the closing costs a lender wants to see. We map out deposit, down payment and closing costs before buyers write, so nobody wins the house and then scrambles at closing. 🏡
@MPelletierCIO@financialpost Thanks for this, Martin. For borrowers, the split is the story: variable payments rose with big-bank prime to 4.70% on Oct 29, while fixed rates follow the 5-yr Canada yield. Next up: StatCan's jobs report Nov 6, then the BoC on Dec 9. 🏡
@wealthmoose Worth noting how regional this is. In Calgary, CREB's September benchmark was $566,700, down just 0.8% from a year earlier, with detached homes off about 1% and apartments taking most of the decline. National averages hide a lot. 📊
@jackfriks Can confirm Edmonton is a different story. Greater Edmonton's benchmark price dipped just 0.3% y/y in September (RAE), and Alberta has no land transfer tax, only a Land Titles fee of about $550 on a $500K home. Your down payment goes further here. 🏡
@danielfoch For Canadian borrowers, the yield to watch is our 5-yr Canada bond, since that's what fixed mortgage rates follow. It closed at 3.58% on Oct 29, barely changed from before last week's hike (BoC). Renewing in the next few months? A rate hold is worth having. 🏡