@SamsungIndia@SamsungMobile@Samsung@SamsungNewsIN
Please accept my phone as a gift that’s parked at your service centre since 9th July 2025, all incl. of repair estimates quoted by you and any dormant damages born thereon. Happy New Year to the best customer care ever!
Is anybody hiring in Mumbai? My help’s brother is desperately looking for a job.
He can drive. He’s open to working ANYWHERE. Both blue collar and entry level desk job
"how many in Mumbai can afford a Rs20cr house?" The answer is many. Think most seniors from BFSI, VC, PE, MF, wealth, investment banks, etc. this is from salary + bonus. And then comes the top slab: promoters, founders, investors. All of them. Many. And they don't need loans to buy a house.
The unintended consequences of MDR. Small personal loans could get costlier.
@deepakabbot breaks it down
For example, a ₹20,000 personal loan for six months at 30% annual interest. The EMI is approximately ₹3,631 and total interest earned is about ₹1,786. If every EMI were collected through chargeable UPI, MDR would total about ₹87.
₹87 sounds trivial. But it is almost 5% of the lender’s entire interest income. This could result in annualised yields falling from 30% to approximately 28.6%, a 144-basis-point yield impact from a 40bps MDR. For a three-month loan, the impact rises to roughly 248 basis points.
Why not simply use UPI AutoPay which is free from any MDR?
Because AutoPay being free doesn’t mean AutoPay always succeeds.
NPCI data showed business declines averaging nearly 74% across the top 50 banks for UPI AutoPay transactions due to insufficient funds. More than 20 million AutoPay mandates were also being revoked every month as customer didn’t have the money to fulful. This does not mean 74% of loan EMIs fail, the data covers AutoPay generally but it demonstrates why a UPI mandate is not a guaranteed collection.
On our ₹20,000 six-month loan, even if just 10% of repayment value attracts UPI MDR, the yield impact is roughly 14 basis points; at 25%, approximately 36 bps; and at 50%, approximately 72 bps
Khetwadi
Parel
Lalbaug
Falkland Road
These areas have the highest concentration of large Ganpati pandals in the tiniest lanes. All of them have old Mumbai history (British era, mill land, etc) embedded. It's a great experience to walk through the pandals even if things have become "commercialized". So much of Mumbai history will fade away once high rises start popping up. Go visit while you can. For 10 days in a year, this is the Mumbai we all remember.
Being rich means buying the iPhone Duo because you want to and you can and prices don't really matter. Being financially free means accepting you can't buy even if you want to because you never included it in your corpus also the Nifty has given 0% for two years.
I’ll share something which I did contrary to what I was advised back then:
When I was in the U.S., I held a few credit cards there- Amex Plat and Chase Sapphire Reserve. Both were some of the best cards back then and I made the best use of it and a lot of bills came down drastically. Especially my travel.
When I left the U.S., almost everyone told me to close the cards. I didn’t. I knew they had high annual fees and I decided to keep it for a year(as I had paid my annual fees a few months back).
But till now I have kept them. It’s been years now. Reason:
1. These cards don’t get declined anywhere globally, Chase is on Visa which works almost at 100% of the places.
2. Both the cards are forex free. In any country.
And despite not being in the U.S., these cards still has given me better benefits than any Indian card I own. And that’s the reason I hardly have any reason to own any card other than my Axis Vistara, Atlas and Infinia card. (And because I don’t have the patience to switch cards or keep buying Gyftr vouchers).
But more than rewards or anything, I have kept these because I don’t want to get humiliated anywhere because my card gets declined. And most of the Indian cards I have owned now or in the past get declined a lot abroad. Even the Indian issued Amex plat which I had in the past. And I should not get started about those Neo Cards which had come.
If you are have a card issued abroad, makes sense to keep it. Because Indian banks when it comes to reliability abroad, are notorious.
A 24-year-old earning ₹80k/month and renting in Andheri wanted to buy a home. Anywhere.
It’s a bad idea. ₹80k/month salary is almost poverty line in Mumbai.
Instead focus on career, save, earn more - and then buy in Andheri. Buy Late but Buy Right.
Got this memorable opening pitch from a startup building in wealth tech
"India has more Tigers than SEBI-Registered Advisors, and we’re fixing it."
Turns out it is also true because India has 3,600 tigers and 1,000 RIAs
Clearly a yawning gap in the investment advisory space
@SamsungIndia You still have my phone at your service centre! It’s been 9 months?! You have the lousiest and the most dishonest customer service. Is your shame up for sale at the repair estimate?!
This is exactly the experience you intend and expect your customers to have. My issue remains unresolved for 9 months! MY PHONE IS STILL WITH YOU and your vile customer service closed the escalation on shady grounds.
@tweetpratiyusha This is not the experience we would expect our customers to have and would like to help. Kindly share your detailed concern and contact details via direct message (DM) so that we can look into this. https://t.co/avriiVOR5I
Bandra is going to define the word unlivable in Mumbai. Here's what's going to happen once all the re-development of all the old buildings is done:
1. Entire property market will go into a bear market. It's already begun.
2. There will be luxury (Carter Road, Band Stand, Pali Hill) and middle class (everything else).
3. The quantity and quality of people will change fundamentally. The cute, next door, middle class will give way to a nouveau riche crap crowd.
4. The Maruti Zen will be replaced by the Thar, the Honda City by Audi, Merc, BMW. Welcome to a new 2Rs type of people.
5. The traffic will become so bad, the rich will demand for flyovers from Linking Road to Carter Road.
6. Like SoBo, the crowd will become Jurassic Park level dinosaur who send their kids abroad. These kids will come back for term break and stand outside Boojee, Bokka.
8. The number of restaurants and pubs will x 100 as new commercial buildings come up and every politician launders money in hospitality and real estate.
7. The smart ones will be those that sold their house to a builder, moved to a much larger house further up north.
Welcome to the true Queen of Suburbs.
Lodha has finally launched that fancy Juhu property and promptly renamed Juhu as Juhu Seaface! Where is their Bandra project? I can't wait to see what they will rename Bandra Seaface, Carters, Band Stand or Reclamation 😂
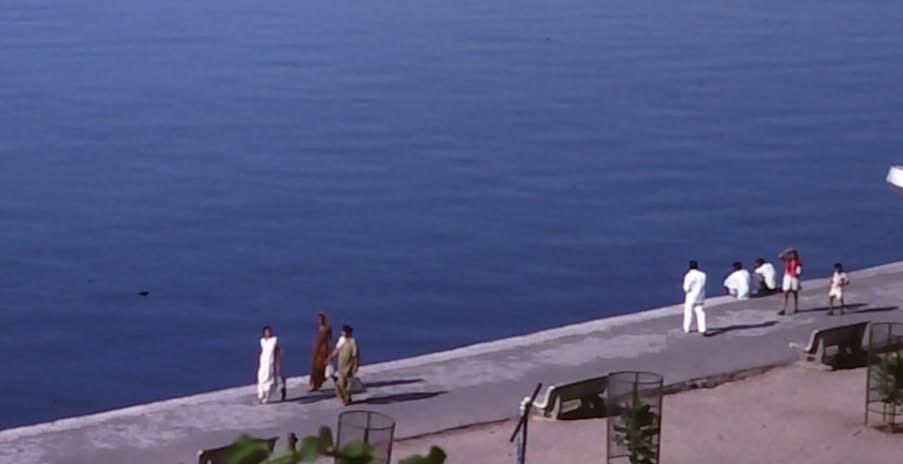
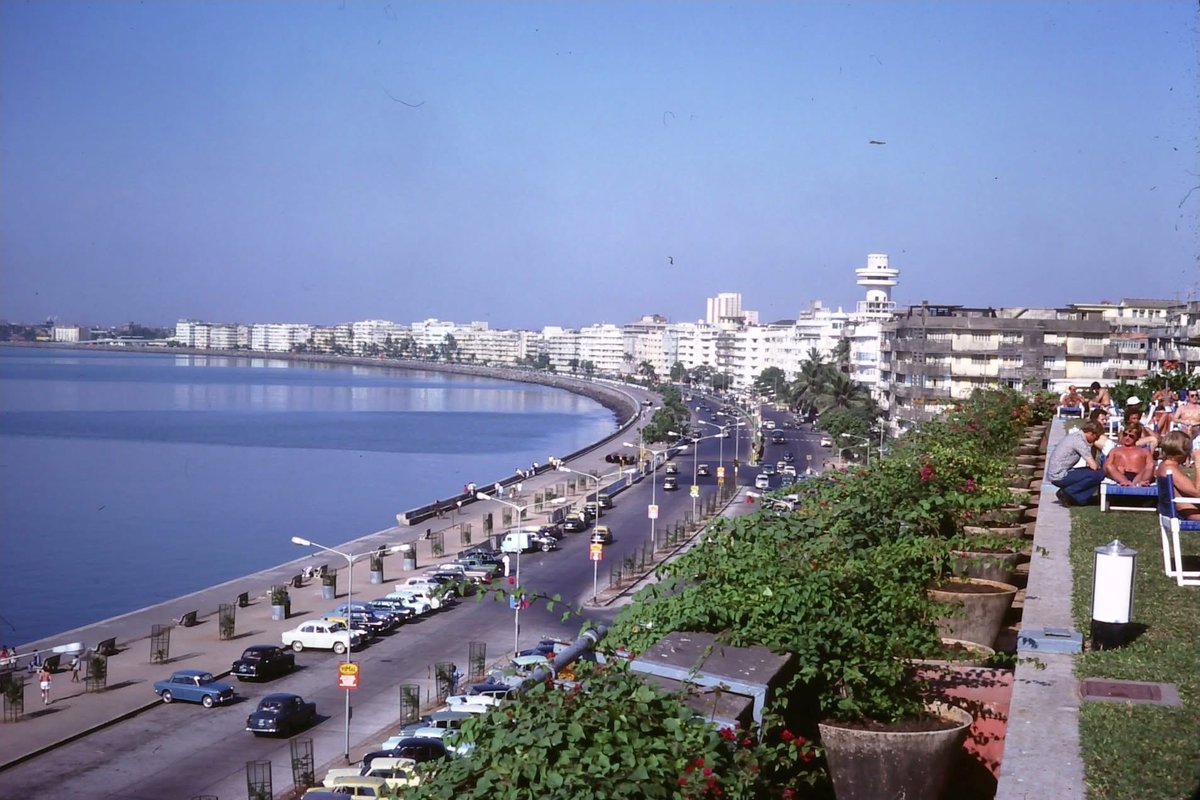
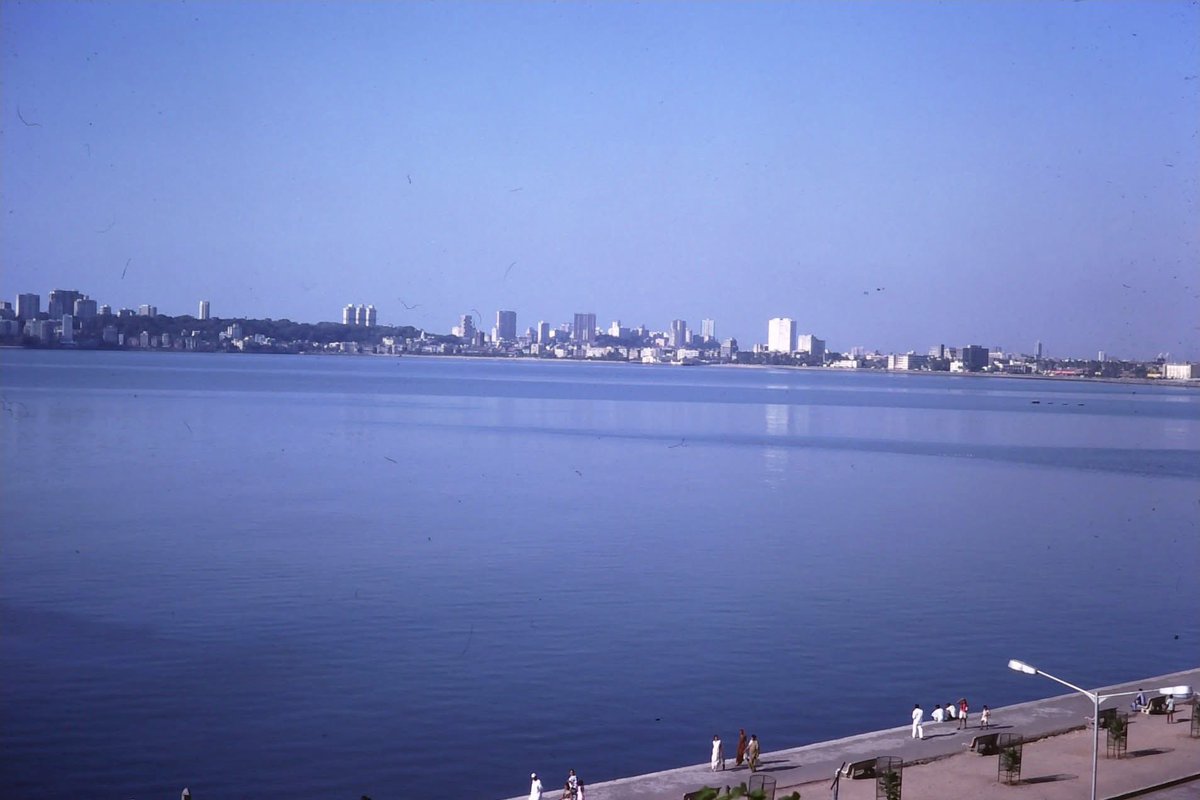
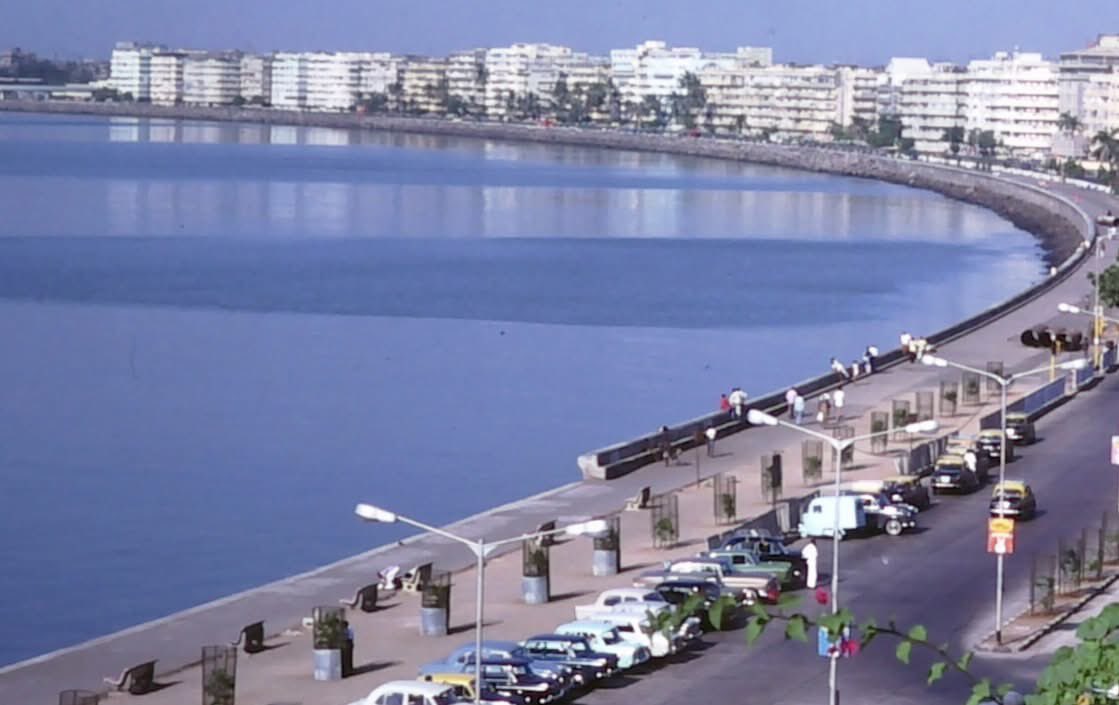
Sharing rare views of Nariman Point & Marine Drive clicked from Oberoi Sheraton in January 1978.
I had to do a double take on the first photo, no parapet wall! It seems it was still under construction then.
Also sharing two zoomed-in frames, notice the clear blue hues of the water. The parapet wall those days existed only till the Air India building and was extended later.
#OldMumbai
Buckley Court, Colaba: Timeless.
Irrespective of the future of certain micro-markets, some buildings will always hold their own. This is one of those in Mumbai.
Builders often do Location Deception to sell homes.
One category highlights an inaccurate but existing location.
The other category highlights an inaccurate as well as non-existing location.
It must be banned.