PART-1 (Stock Name in Part-2 Don't miss)
✈️ **INDIA'S AEROSPACE BOOM: THE NEXT MULTI-DECADE MEGATREND?**
Airbus & Boeing have a combined order backlog of **14,850+ aircraft**, offering 10–12 years of demand visibility.
🇮🇳 India could become a major global aerospace manufacturing hub.
🔍 Key companies to track:
PTC Industries | Azad Engineering | MTAR Technologies | Aequs | Dynamatic Technologies | Cyient DLM | Rossell Techsys | Unimech Aerospace
**The real opportunity lies in precision components, engine parts, titanium & advanced manufacturing.**
⚠️ Great businesses can still be bad investments at excessive valuations.
Which company could emerge as India's aerospace champion?
#Aerospace #MakeInIndia #IndianStocks #ChartGuruji
*Educational purpose only. Not a buy/sell recommendation.*
Auto ancillary stocks venturing into Precision Engineering, Aerospace & Defense tend to get re-rated.
Best example is probably Sansera Engineering.
Belrise industries is kind of trying to follow a similar path -
Consumer Electronics Entry: Entered the ecosystem of a major American smartphone manufacturer with an order for high-precision CNC fixtures. This is seen as a high-margin, recurring business opportunity.
Expansion funnel: already in discussions for additional fixture categories including “MLB… main logic board fixtures” and “FATP… final assembly, testing, and packaging fixtures.
Initial order value is small but potential is big.
Aerospace Order Win: Secured the first order win post-acquisition at Kestrel Hall (UK) for manufacturing 'track beams' for a leading global aircraft OEM.
Management reiterated prior view: within 12–18 months, “>10% of our manufacturing revenues” from aerospace & defense.
Operating model: management outlined a hub-and-spoke approach—UK/Europe as R&D + marketing hub, India as “best cost base”
............................
This is not an investment advise or recommendation.
Please do your own due diligence before investing
Looks like for the #FIIs / #FPIs , #Indian#Markets have turned into a risk-off trade, while #Dxy & US 10-Yr bonds are soaring! And once #USD starts getting weaker and 10-yr yields softening, the risk-on #AI trade will resume! Which I believe is around the corner!
KOSPI has another 11-12% to fall before it can complete its correction
I am sorry, I only warned about this in July and provided the support levels then too.
Proud to have covered this company.
Huge tailwinds in the sector.
Great margins...
Lot of expectations...
Underrated stock💥
Link in Bio & 1st comment👇
Big Investors, Small Prices: 15 Penny Stocks Under ₹100!📊🎯
1- Vodafone Idea
Investors: Government of India + Vodafone Group
2- Yes Bank
Investor: Sumitomo Mitsui Banking Corporation (SMBC)
3- Bajaj Housing Finance
Investors: Bajaj Finance / Bajaj Group
4- IDBI Bank
Investors: LIC + Government of India
5- Tata Teleservices (Maharashtra)
Investors: Tata Group + FII/DII
6- GMR Airports
Investors: GMR Group + Groupe ADP
7- Morepen Laboratories
Investor: FII Investors
8- NIIT Ltd
Investors: Nippon India Small Cap Fund / Massachusetts Institute of Technology (MIT)
9- Patel Engineering
Investor: Vijay Kedia
10- Allcargo Logistics
Investor: Mukul Agrawal
11- JTL Industries
Investor: Zenith Multi Trading DMCC
12- Websol Energy System
Investors: FII + DII
13- Paramount Communications
Investor: FII Investors
14- GK Energy
Investors: HSBC Flexi Cap Fund / 360 ONE Flexicap Fund
15- Om Infra
Investor: Vijay Kedia
माँ की किताब Belonging: A Journey of Love के लॉन्च पर अचानक बचपन से अब तक की कितनी ही यादें ताज़ा हो गईं।
सोनिया गांधी को जानना हो, तो एक बार उन्हें मेरी नज़रों से देखिए। उनका हौसला, उनकी संवेदनशीलता और तमाम मुश्किलों के बावजूद ज़िंदगी को प्यार से गले लगाने की उनकी खूबसूरत क्षमता - यही है मेरी माँ।
आज माँ की किताब को इतना प्यार और अपनापन देने के लिए आप सभी का दिल से शुक्रिया। ये मोहब्बत यादगार है। ❤️
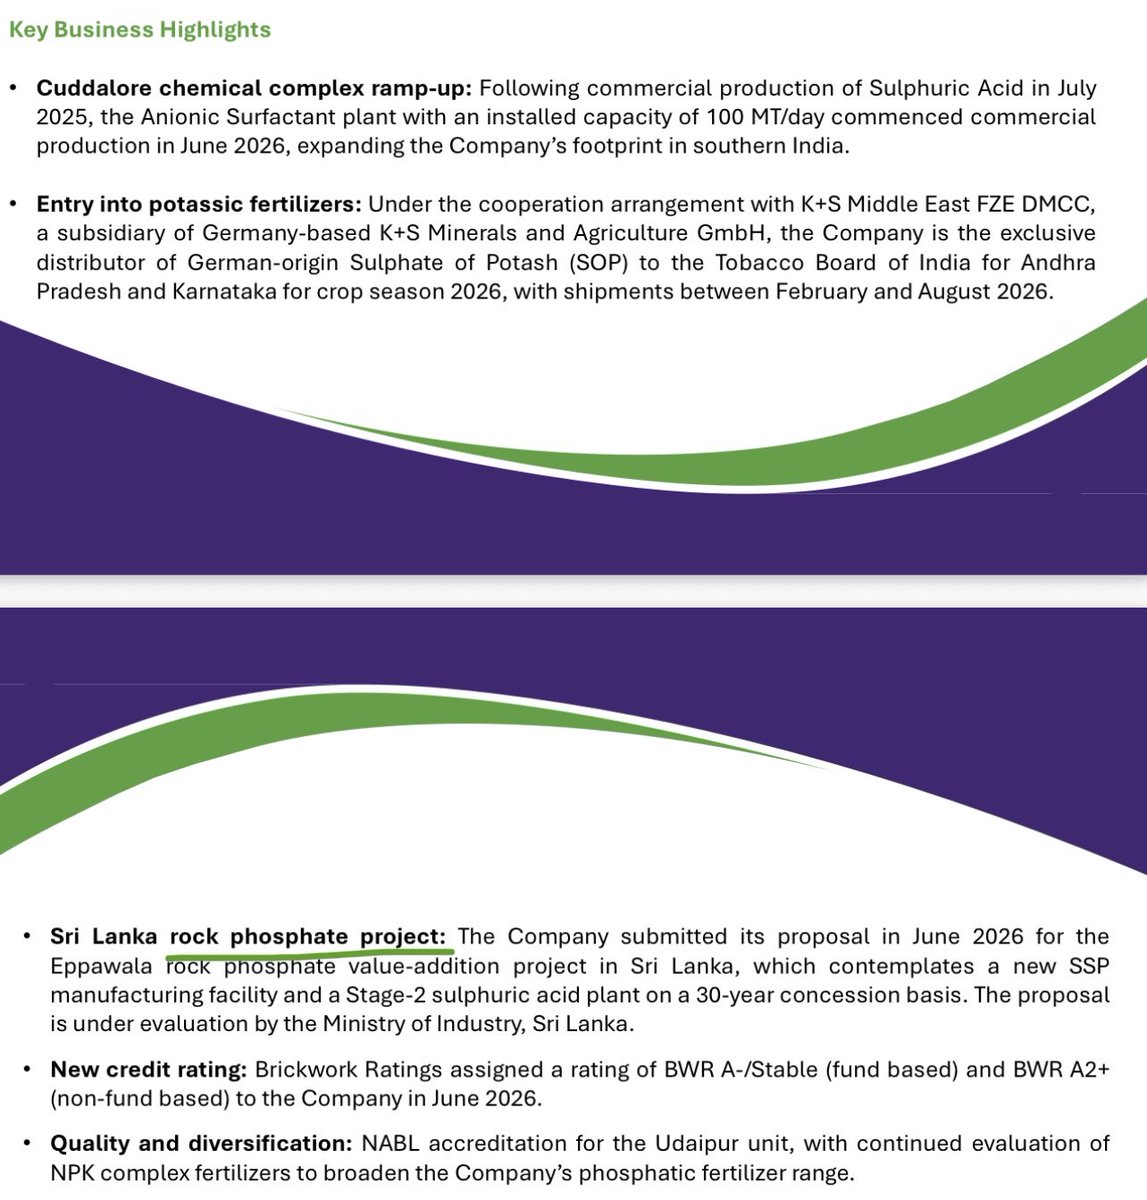
He called Copper (beneficiary Hind Copper, etc) perfectly last year at inflection point.
Now, he recently called for Rock Phosphate/SSP fertiliser in view of self sufficiency.
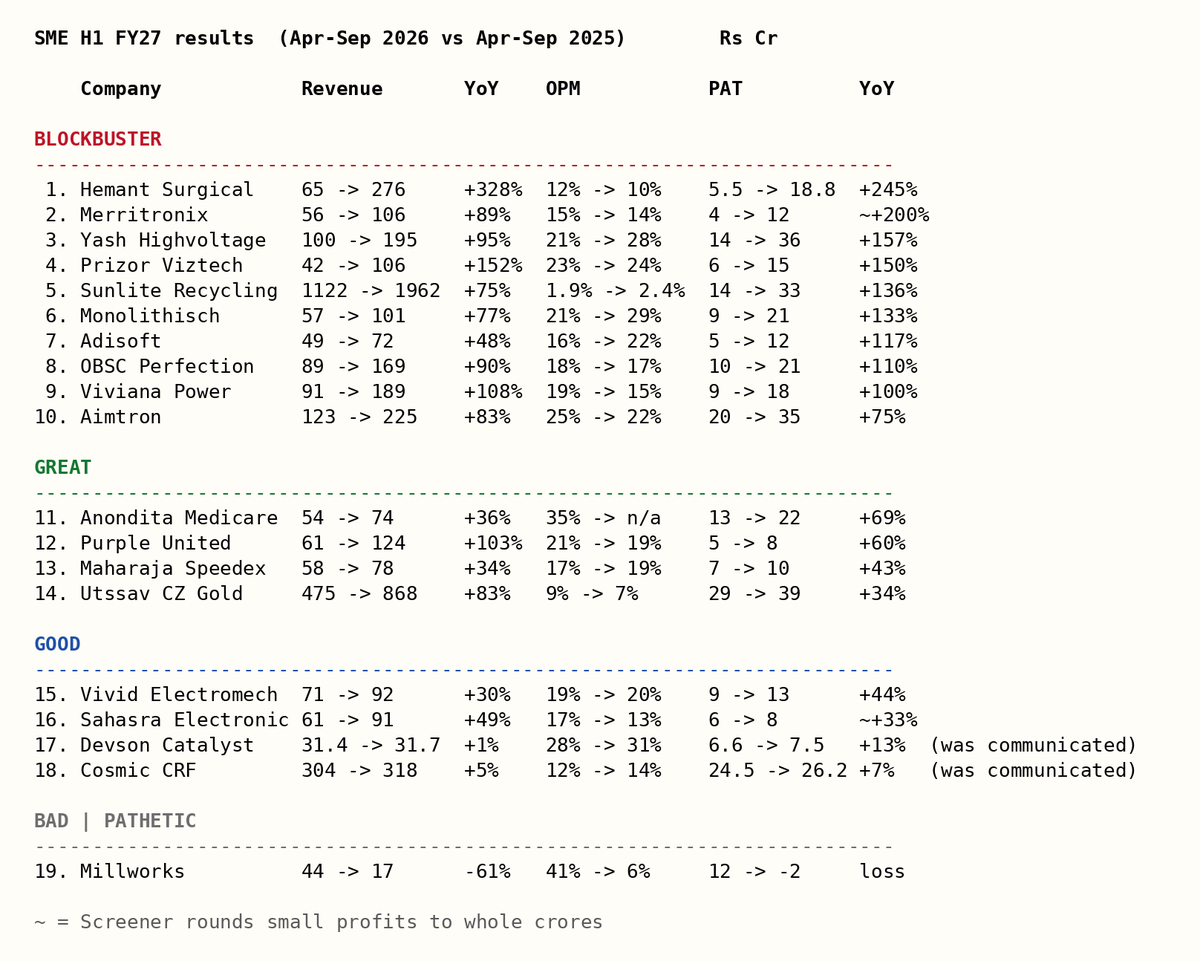
One SME fits perfectly here after stellar H1.
CMP - 78
EPS - 11.92
P/E - 6.5
IPO at 99, listing at 197.
Technically perfect ROUNDING BOTTOM.
Probable re-rating candidate.
#AxisCades Sep’26 results reminds me of Laurus Sep’24 results.
Going through business transformation, all costs front loaded, margins at the trough, capacities and capabilities getting built and investors were skeptical whether Dr chava can deliver !!
Q2 has been remarkable in fact, with core segments, Defense and XIDA delivering solid growth. Aerospace vertical is taking off with cloud wave acquisition. Space is getting ready to deliver in FY28 with new JVs
Corporate costs weighing on the margins which will get normalized as revenue base grows.
With management guidance of 30% growth QoQ for Q3 and Q4, things should move up from here.
I keep the faith and remain invested
Disc. Sahasrar capital private limited, PMS - SEBI REGN No INP000007386. We are invested.
Morgan Stanley recommended going “max overweight” in global stocks for next year, saying it will be the year to “embrace risk” as spending on the AI boom continues. They particularly like US equities, and upgraded their view on Japanese and European stocks.