@QuantStrategist It’s how the controlling family roll. They dividend ~35% earnings and plow the rest into bonds/deposits plus whatever capex the business needs (very minimal). It is what it is. The business is so good that they can still do high ROE even with the significant cash drag.
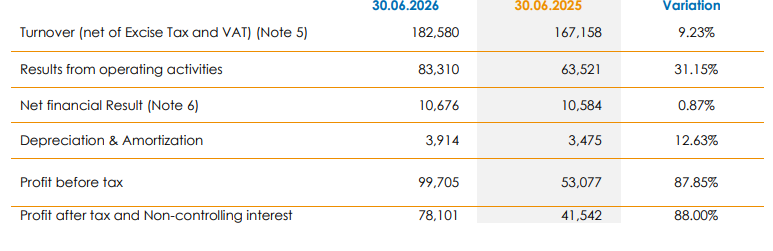
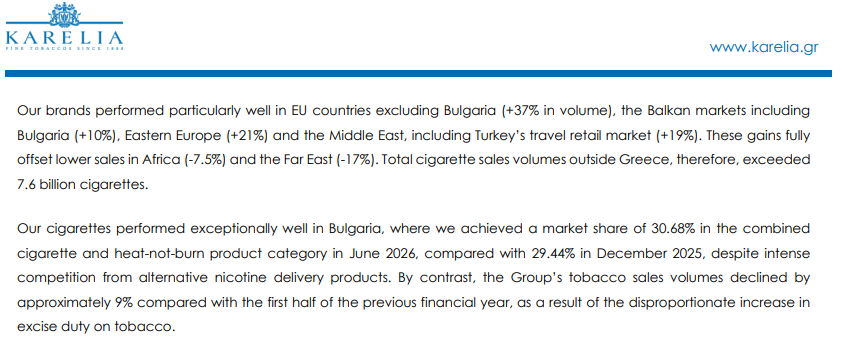
Karelia Tobacco posting some incredible results today. EPS +88% (closer to +40% stripping out FX gains). Significant gross margin expansion (46% to 53%). Somehow increasing cigaratte volumes (38% volume increase in EU exports). $KARE.AT
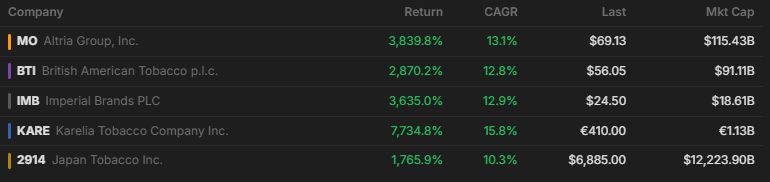
Despite a valuation discount and reinvesting the majority of their earnings in low yield debt, Karelia has outperformed all of the major tobacco companies over the last 30 years (total returns).
Semi-serious take, but the second best way to play the AI infra trade has been to identify stocks that have gone up 100% and buy the top 2-3 names in that industry (better still if you get a pullback).
Sure, you can't front run the semianalyses and the citrinis, but as long as supply is still bottlenecked, business has a lot of growth left. Has worked out okay so far for photonics, memory, and to a lesser extent power and CPU.
@BobGrayson15@TripleNetInvest@BillAckman Except he actually started his investment vehicle in 1992 (Gotham Partners) which blew up in 2003.
https://t.co/woPVpuggk4
@CapitalObserver@Reignots Agree - ultimately CIAM’s case is very weak and the original court decision was poor. They potentially could come up with some new argument for de-facto control and have threatened going to ECHR (but very low probability of success). But will still delay things for VB.
@mxschumacher VB completely nailed it selling the logistics businesses at the top of the market. Has fallen out of favour for sitting on ~€6b of cash since, but was a master stroke in hindsight.
@mxschumacher VB completely nailed it selling the logistics businesses at the top of the market. Has fallen out of favour for sitting on ~€6b of cash since, but was a master stroke in hindsight.