🛢️Time Technoplast - Well positioned for growth
People think it's pretty standard plastic business, but there is more to it
Company operates in
- Industrial Packaging
- IBC's
- Cyllinder
- PE Pipes
Growth triggers
- Continued growth in Industrial packaging, steel to polymer conversion
- higher margin value added products
- increasing CNG infra
- Higher utilization, moderating capex, deleveraging working capital requirement
Value added products - 28% of total revenue, will continue to improve further
VAP's 👇👇
🔰IBC's - GNX Bulktainers - More of industrial usages, replaces several drums with one big container
🔰Composite cyllinder
- CNG
- LPG
- Hydrogen & Oxygen
🔰MOX films - speciality films for industrial packaging, laminates, protective layers
SME News You Might’ve Missed 🚨
Shree Refrigerations Bags ₹7.86 Cr Indian Navy order for 2 Magnetic Bearing Compressor-based AC Plants; execution by Oct 2027.
JD Cables Secures ~₹30.43 Cr order for manufacturing, testing, supply & delivery of cables and conductors; ex in 3M
Hey @grok, out of these 20 MOAT companies, which 5 do you believe have the potential to become 5X–10X over the next 5 years to study? 👀🔥
Pick only 5 - and tell us why ✏️
Anondita Medicare
Yash Highvoltage
Shree Refrigerations
Merritronix
Millworks Technologies
Danish Power
Afcom Holdings
Aimtron Electronics
L. T. Elevator
CFF Fluid Control
OBSC Perfection
Prizor Viztech
Sacheerome
Concord Control
Accent Microcell
Unihealth Hospitals
Digilogic Systems
Airfloa Rail
Taurian MPS
Remus Pharmaceuticals
My view 👇
Study their business quality, growth runway, order book, margins, capacity expansion, management quality, valuation and technical structure and identify which businesses can potentially create substantial wealth over the long term.
Three pharma CRDMOs have caught our attention for a deeper dive:
• Sai Life Sciences
• Cohance Lifesciences
• Laurus Labs
Our team will spend the coming 2 months dissecting their value chains, capabilities, customer relationships and competitive advantages.
Once the work is done, we’ll publish our Company X-Ray & Moat Reports.
No surface-level analysis. We’re going deep.
One of my friend made 4 cr from 20 lakh in 5 years just by doing trading in cash segments , his portfolio was down from 4 cr to 3 cr in this correction but still in recovery reached at same level .
He never did any F&o trade.
He disclosed his secret, he just buy a stock which are above all moving averages with RSI 60 around.
Most importantly he just allocate all money in 2/3 stocks.
Except this he always buy after quarterly results and book profit before upcoming results.
His next target is to make portfolio 10cr till 2028
He doesn’t want to be disclosed his identity because of some personal reason.
#stockmarket
#investing
Supreme Engineering Ltd
CMP: ₹4.32 | Market cap: ₹108 cr
Speciality steels and superalloys with exposure to defence, aerospace and nuclear applications.
1. New orders: ₹2.84 cr defence order and ₹5.29 cr PSU superalloy order; both executable within six months.
2. Ashish Kacholia entry: Proposed investment of ₹8.32 cr through 3.2 cr preferential shares at ₹2.60 each.
3. Promoter participation: Sanjay Chowdhri’s proposed commitment is ₹32.50 cr through equity and warrants; other promoters are also participating.
4. Fundraise: The ₹110.75 cr equity-and-warrant proposal includes these investments, supporting debt settlement, working capital and business requirements.
5. Debt settlement: Bank of India OTS agreed at ₹60.32 cr against a ₹117.5 cr claim; ₹6.03 cr deposited.
6. Insolvency exit: CIRP withdrawn in August 2026, returning control to the existing management.
7. Improving results: FY26 operating revenue reached ₹24.77 cr; net loss narrowed to ₹0.60 cr.
🚩 Red flags: A small business undergoing major financial restructuring, with negative net worth, a default rating, audit concerns, tax disputes, overdue statutory dues and substantial dilution. Funding and full debt settlement remain pending. The ₹2.60 preferential price is also significantly below the quoted market price.
View: Investor and promoter participation adds interest to this high-risk turnaround story. Completed funding, debt settlement and sustained operating recovery are the key developments to watch.
Educational study based on supplied information. No buy/sell recommendation. Study independently.
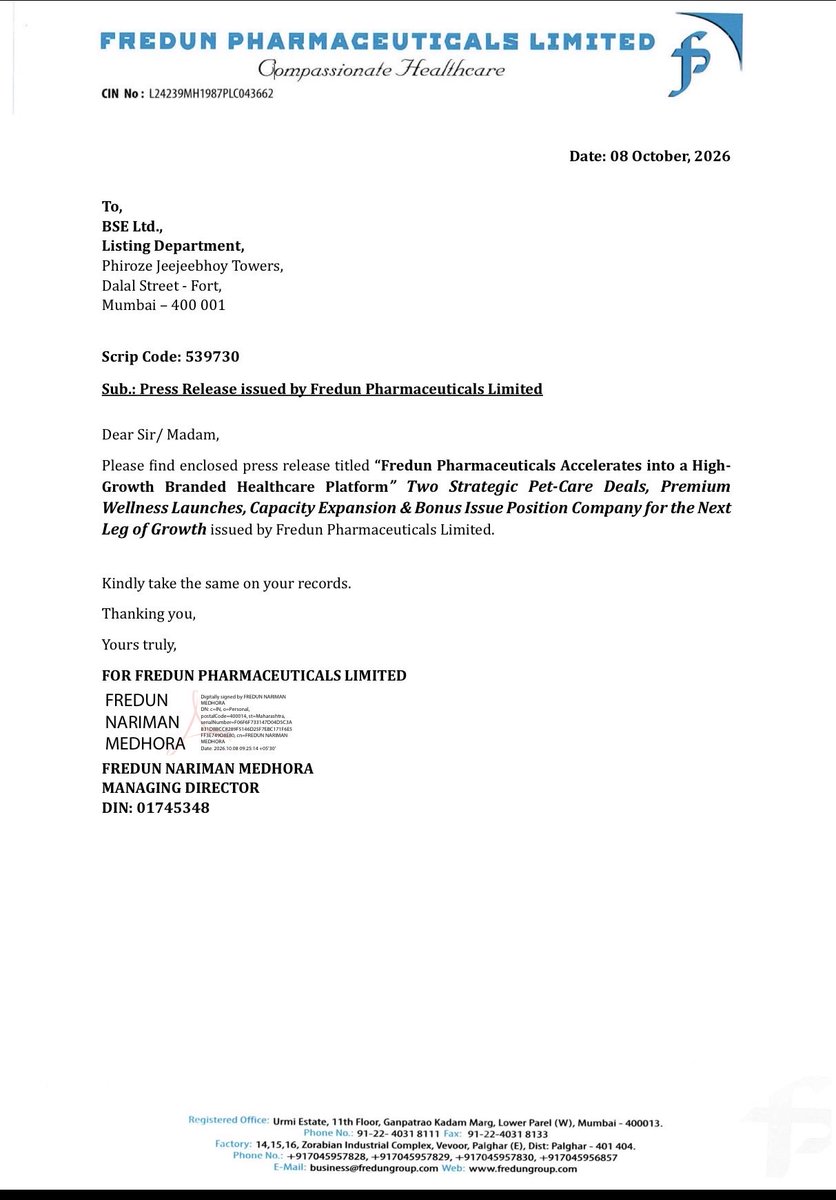
Imagine telling your board you’ll go from an OEM-led business to 100% own brands by 2029. Fredun Pharma just said it out loud.
Revenue and profit doubling in 3-4 years is the target. Here’s what’s already in motion:
→ 26% of Goodman Vetcare at a ₹300 cr valuation. It runs 3 pet pharmacies today, with at least 8 more planned and ~₹100 cr revenue targeted by FY31.
→ Furlicks, bought from USV. It goes from 6 SKUs to 22 over the next 6-9 months.
→ WAGR, the platform meant to tie pet brands, pharmacies and services together.
→ Palghar: a ~40,000 sq ft block goes live this month, with 50,000 more planned.
→ Fredun Gx is going after 500+ SKUs in Tier 2-4 cities, and the export base already covers 53 countries.
→ The share count went from 55.13 lakh to 1.65 crore after the 1.10 crore bonus shares.
Pivoting from OEM to brands is the right idea. It’s also the hardest one in pharma to pull off.
Three stores aren’t an ecosystem yet, and brands burn cash before they earn it.
The next few quarters will tell us whether this is a re-rating or just a well-written press release.
At Zenflow Finance, we track what actually moves markets.
India’s #HVDCBoom: A New Power-Transmission Supercycle
India is entering a major HVDC build-out. The CEA’s transmission plan adds around 33.25 GW of new HVDC capacity by 2032, almost doubling the existing fleet. The reason is simple: India’s best renewable-energy resources are often far away from its biggest power-consuming regions. HVDC acts like an electricity expressway, allowing large amounts of power to travel long distances efficiently.
HVDC = High Voltage Direct Current. Electricity is converted from AC to DC, transmitted over hundreds or even thousands of kilometres, and then converted back to AC at the destination. It becomes especially attractive for long-distance transmission, where it can use fewer conductors, require less land and provide precise control of power flows. India’s upcoming corridors are largely in the 600–1,200 km range.
The important part for investors is that this is not simply a story about building more transmission towers. The industry itself is changing. HVDC is moving from occasional projects to a serial pipeline, from nominated projects to competitive auctions, from traditional LCC/thyristor technology toward greater use of VSC/IGBT power electronics, and from imported equipment toward increasing local manufacturing. The government’s local-content requirement is scheduled to rise from up to 30% until March 2028 to 60% from April 2032 for LCC HVDC converter stations.
Another major structural change is that the market is becoming a seller’s market. Global HVDC manufacturing capacity is heavily booked through roughly 2028–2030, while complete ±800 kV converter stations require specialised technology, testing, engineering capability and proven references. This creates a qualification barrier, meaning only a small number of companies can compete for the highest-value parts of the project.
This is where the HVDC value chain becomes interesting. At the lower end are raw materials, towers and line EPC. Then come specialised components such as CTC, bushings, insulators, reactors and other high-voltage parts. Above them are converter transformers, thyristor/IGBT valves, cooling systems and filters. At the top sits system integration, control & protection and power-electronics expertise. The document’s key message is that the largest economic value is concentrated around the technology-heavy layers rather than commodity-like construction work.
The most interesting long-term opportunity may be lifetime service. India’s older HVDC fleet is ageing, so equipment such as valves, controls, reactors and insulation systems will eventually require refurbishment and upgrades. As the installed base expands, original equipment manufacturers can potentially earn recurring revenue from the same assets for decades. This gives companies with a large installed base a stronger “toll-bridge” advantage than companies whose benefit comes mainly from today’s project shortage.
Among Indian listed companies, the clearest direct beneficiaries are:
#HitachiEnergyIndia, #GEVernovaTDIndia and #SiemensEnergyIndia, with #BHEL acting as the major Indian manufacturing and consortium partner.
#QualityPower and #KSHInternational are interesting niche beneficiaries through HVDC-class reactors and specialised winding conductors.
On the AC side, #CGPower and #TransformersRectifiers can benefit because every HVDC converter station still needs a substantial 765/400 kV AC network around it.
Line contractors such as #KECInternational, #KalpataruProjects, #Transrail and #JyotiStructures can benefit from the large transmission build-out, but their economics are generally more execution- and commodity-sensitive.
For investors, the biggest lesson is simple: don’t just ask who gets the biggest HVDC order. Ask who controls the bottleneck. Technology, qualification, proprietary control systems, specialised manufacturing capacity and installed-base service can create much stronger pricing power than simply supplying towers and wires.
The real HVDC story is therefore: renewable-energy growth → long-distance transmission → converter stations → power electronics → local manufacturing → lifetime service.
That is where the structural opportunity lies.
🚨 US Visa Crackdown Hits IT Giants!
Microsoft, Infosys, TCS, Wipro & Cognizant reportedly suspended from a US green card programme over alleged H-1B misuse.
A fresh immigration headache for Indian IT giants. Could this add pressure to the sector?
#H1B#Infosys#TCS#ITStocks
Tempsens : What I would look out for 👉
1) Top line growth moving over 30%+ and improving further
2) Margjns improvement and moving up the value chain with more value added products
3) Exports growth
No Recommendations.
PNGS Reva gave a 70% topline growth guidance for FY27 in Q1FY27.
After seeing 46% revenue growth in Q2 and 76% growth in H1, I think the company can beat its FY27 guidance comfortably.
Guidance of 40% topline CAGR till FY30.
As gold prices remain elevated, diamond jewellery could become increasingly attractive, especially for consumers looking for lower-ticket alternatives while still participating in jewellery consumption.
PNGS Reva is currently one of the most interesting plays in the diamond jewellery segment.
Not a recommendation to Buy/Sell.
KANOHAR ELECTRICALS: CO. TARGETS APPROXIMATELY INR950 CRORES IN REVENUE FOR FY '27, WITH AN EBITDA MARGIN PROFILE BROADLY SIMILAR TO FY '26. || GROWTH IN FY '27 WILL BE DRIVEN BY INCREASED MANUFACTURING VOLUMES AND AN IMPROVED PRODUCT MIX, PARTICULARLY FROM THE 400 KV SEGMENT
Buy on Dips Stocks
Invested & Biased.
Some more stocks on my radar for buying on dips:
• Kanohar Electricals
• Q Power
• Morepen Laboratories
• Rentomojo
• Anlon Healthcare
My Money. My Decision.