Excerpt from @binance VIP Private Event on the afternoon of July 30, featuring market analysis by renowned economist Hao Hong on the current technology stock correction. bitcoin:native
Flash News 1
Hao Hong: Tech stock adjustment window may last until late August, but likely double-digit short-term rebounds
On July 30, during today's Binance Private Event, renowned economist Hao Hong stated that the major adjustment window previously forecasted by his team has opened and is expected to last until around the end of August. While there may be double-digit rebounds in the short term, the market remains in a deleveraging phase, and investors can afford to be more patient.
Hong pointed out that the South Korean KOSPI index has pulled back significantly from its highs, and the market is entering a phase where "bulls buy the dips while bears cut losses and exit." Because index weightings are highly concentrated in a few tech giants, their fundamental performance will remain the key factor in determining whether the market has truly bottomed out.
Regarding whether to position in tech stocks immediately, Hong indicated that bottoming signals are expected to become clearer over the next two to three weeks, making patience crucial in the interim. He cautioned that typical asset bubble bursts often undergo adjustments of two-thirds or even more; although the market has already dropped by about 50%, further downside cannot be ruled out.
At the same time, Hong noted that beyond price action, investors need to monitor factors such as South Korean regulatory policy, the deleveraging process, and foreign leveraged ETFs. He added that if this round of adjustment completes relatively quickly, it will offer long-term investors more attractive entry opportunities for these assets.
For other news coverage of yesterday’s event, please use the @binance platform. @heyibinance
The Market Is Breaking The Hedge Fund Playbook
This chart is showing how badly the traditional hedge fund long short book is getting squeezed. The Goldman hedge fund VIP basket represents the stocks hedge funds tend to crowd into on the long side. The most shorted basket represents the names they are betting against. When this spread falls, it means the crowded hedge fund longs are underperforming the stocks they are short.
That is a brutal setup for long short managers because the model depends on the opposite happening. You want your longs to outperform and your shorts to underperform. Here, the short book is not helping. It is hurting. The market is rewarding the exact names many funds are positioned against while their favored longs are failing to separate.
Why It Matters
This is less about one bad trade and more about market structure. It suggests the market is not rewarding clean fundamental selection right now. It is rewarding liquidity, momentum, forced positioning, short squeezes, index flows, and whatever trade has the most mechanical buying behind it.
That creates a nasty trap for professional money. If hedge funds chase the same momentum names everyone else owns, they survive until the reversal hits. If they stay disciplined and run the classic long good companies, short weak companies playbook, they risk getting steamrolled by short squeezes and factor reversals.
That is why the mood is bad. They are not just losing money. They are losing confidence in the rules of the game.
The Historical Pattern
We have seen versions of this before. In the late 1990s, fundamentals stopped mattering for a while as speculative momentum overwhelmed valuation discipline. In 2007, the quant quake showed what happens when too many funds are crowded into the same factors and are forced to unwind together. In 2020 and 2021, heavily shorted junk and meme names ripped so violently that being right on business quality did not matter if the positioning was wrong.
These environments punish intelligence in the short run because the pain is not driven by fundamentals. It is driven by crowding, liquidity, and forced flows.
My Take
This chart is showing a late cycle, liquidity distorted market where the index can still look fine while the professional money underneath is struggling. Crowded longs are no longer carrying the book, crowded shorts are not breaking down, and managers are being forced into bad choices.
Either chase momentum and risk getting caught in the reversal, or stay disciplined and underperform while clients get impatient. That is the kind of market where positioning matters more than valuation until suddenly valuation matters again all at once. 🍄
העולם לא באמת גווע ללא נפט...אבל אל תבנו על טיסה זולה לפריז בקיץ הקרוב.
אנאס אל האג'י, המומחה מס אחד בעולם בתחום האנרגיה, מציג תמונה הפוכה לחלוטין ומנפץ את נרטיב המחסור בנפט הגולמי. אל-האג'י מצביע על כך שהשוק סובל מחוסר הבנה מבני של הנתונים, ומסביר את המציאות הפיזית באמצעות שלושה כשלים מרכזיים בנרטיב הקיים.
הטיעון המרכזי של אל-האג'י חושף כי הירידה המדוברת במלאים היא אשליה אופטית בלבד. על פי הנתונים, 98% מהצניחה במלאי העולמי מגיעה ממשיכות מתוך המאגרים האסט��טגיים הממשלתיים ולא מהמלאי המסחרי.
יתרה מכך, כמעט כל המשיכות הללו מוגבלות לשתי מדינות בלבד: ארצות הברית ויפן. בעוד שיפן מושכת נפט בשל אילוצים מקומיים, ארצות הברית משחררת נפט מתוך עמדת שפע ומגדילה את היצוא שלה. המלאי המסחרי הרגיל בעולם נותר יציב לחלוטין, ומכאן שהשוק החופשי אינו חווה מחסור פיזי בנפט גולמי.
ההבחנה החשובה ביותר של אל האג'י היא ההפרדה בין נפט גולמי למוצרים מזוקקים כגון בנזין, סולר ודלק סילוני. הלחץ הממשי בשוק נמצא אך ורק בצד המוצרים ולא בצד חומר הגלם.
חוסר היציבות הגיאופוליטי הוביל להשבתת שלושה בתי זיקוק ענקיים במפרץ הפרסי בסעודיה, כווית ובאיחוד האמירויות, לשיבושים ברוסיה ולהטלת מגבלות יצוא פוליטיות על ידי מדינות כמו סין והודו. כתוצאה מכך, בתי הזיקוק הפעילים במערב כבר פועלים בניצולת ש��א של כ-94.5%.
כאשר בתי הזיקוק נמצאים בקצה קיבולת הייצור הפיזית שלהם, הם אינם מסוגלים לקלוט ולעבד חביות נפט נוספות, גם אם הביקוש לדלק בתחנות בשיא הקיץ יהיה גבוה במיוחד. מכיוון שבתי הזיקוק אינם יכולים להגדיל את הביקוש שלהם לנפט גולמי, אין כל סיבה לעלייה חדה במחיר החבית.
אל האג'י מדגיש כי נפט אינו מוצר אחיד. המשבר הגיאופוליטי במזרח התיכון גרע מהשוק בעיקר נפט בינוני-גופרתי, החיוני לייצור סולר. זו הסיבה לדרישה הגבוהה לחביות מתוך המאגר האסטרטגי האמריקאי, המספק את האיכות הספציפית הזו. תפוקת הנפט החדשה של ארה"ב מורכבת מנפט קל ומתוק, שאינו יכול להוות תחליף ישיר לאיכות שאבדה.
הלחץ הנוכחי בשוק ממוקד כולו בצווארי הבקבוק של הזיקוק ובמחסור אזורי במוצרים סופיים, כגון דלק סילוני באירופה או גז בישול באסיה. תמחור הנפט הגולמי הנוכחי מונע מחששות גיאופוליטיים ומפסיכולוגיה של משקיעים, ולא מגירעון פיזי אמיתי באספקת החביות העולמית.
As Carl Jung put it, "Man needs difficulties. They are necessary for health." Yet most people instinctually avoid pain. This is true whether we are talking about building the body (e.g., weight lifting) or the mind (e.g., frustration, mental struggle, embarrassment, shame)--and especially true when people confront the harsh reality of their own imperfections. #principleoftheday
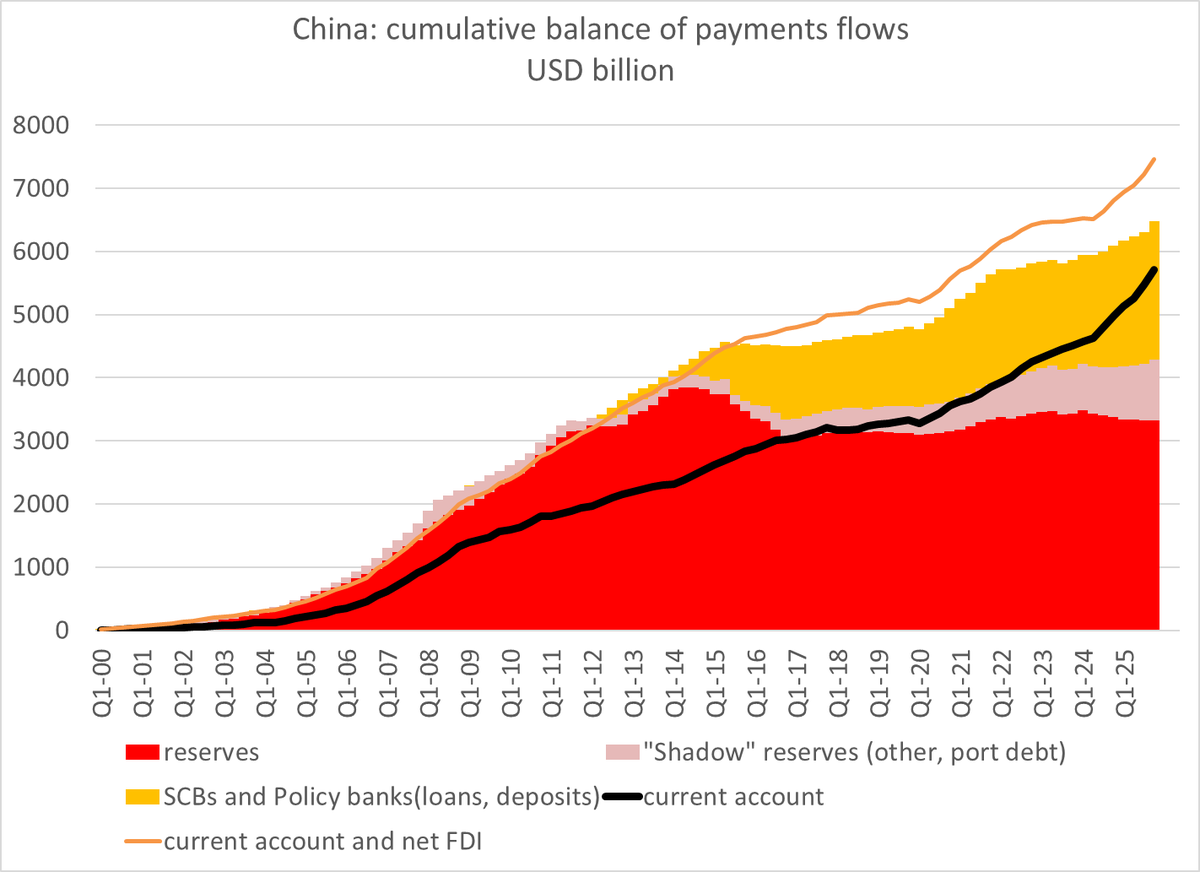
As I mentioned on Wednesday, there is a $3 trillion gap between China's accumulated current account surplus since the pandemic and China's unchanged reserves (and a corresponding gap in visible flows into the US)
Bank flows make up most of the difference
1/
Trump is NOT escalating this into a major ground war. Let me spell this out with crayons.
I’m a US Merchant Marine Captain, O6 (not O3) equivalent. We are a tiny forgotten service with one MF overarching specialty: moving escalatory armies overseas.
It’s true a general like McChrystal has far more knowledge about what to do AFTER his tanks roll off our ships.
But BEFORE those tanks roll off? They are OUR cargo.
We are the specialists. We climb all around those tanks. We secure them, move them, deliver them. Our Commandant, who I talk to every single week, is in charge of that lift. Not whatever general is waiting on the pier.
Right now we are in the BEFORE stage.
I absolutely 💯 know more about this than any general because I have spent decades training and living the life for THIS MOMENT.
When generals want to move escalatory army divisions overseas, they call us.
We don’t specialize in every branch.
Naval, Air Force, USMC, Special Forces movements have their own lift pipelines. We can help, but that’s not our core mission.
But if you want to escalate a war with heavy ground forces? I get a call.
The Air Force has already called us to move more bombs into theater. So yes, the air campaign can escalate.
But there are ZERO plans to escalate this into a large scale ground invasion.
ZERO.
This cannot be done by airlift. The USAF can’t even get their own bombs overseas right now, let alone divisions of army units.
And if I do get the call, it will be months before we are landing tanks.
So I repeat… this CAN NOT turn into a major war without my phone ringing.
You can send Marines and air assault units without tanks to do raids but a major landing force like McChrystal is talking about just is not happening. Not yet. Not for months, if ever.
And when it does happen I will tell you because you can’t move Army divisions in secret. Not since the Army, in a moment of idiocy, sold off its Merchant Marine preposition fleet last year.
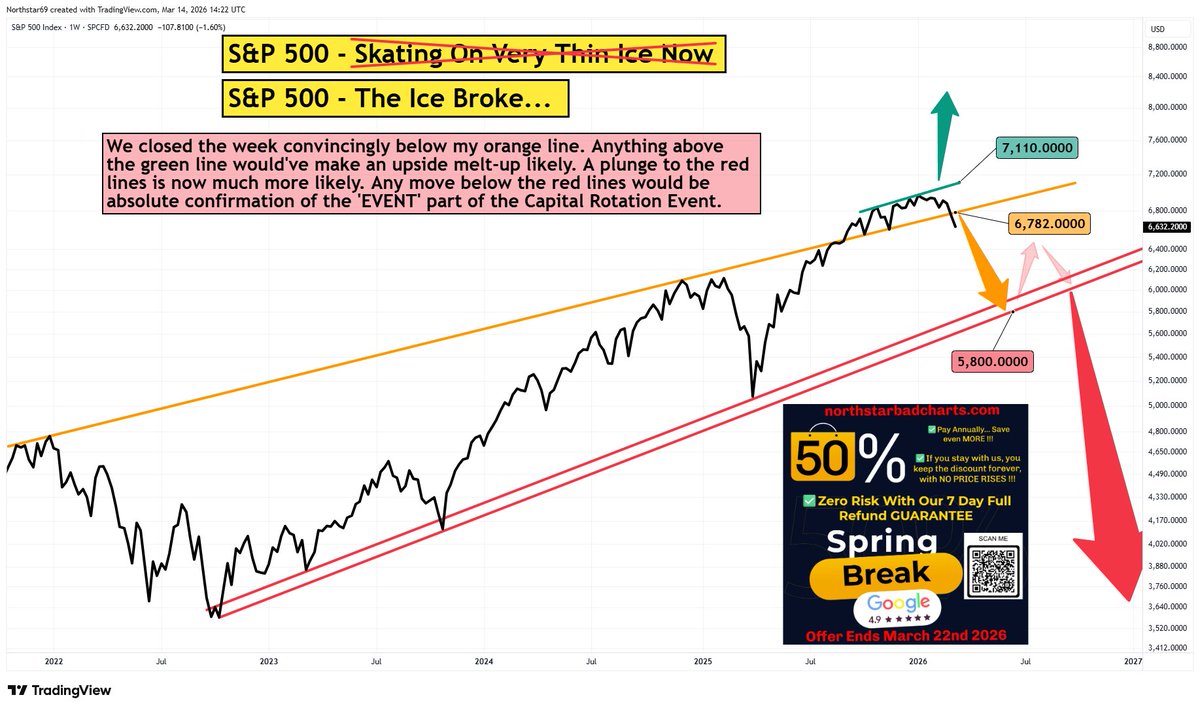
STOCK MARKET ALERT: If you like this type of analysis and the results in the attached post, why not take advantage of our current 50% discount before prices go up 🙂
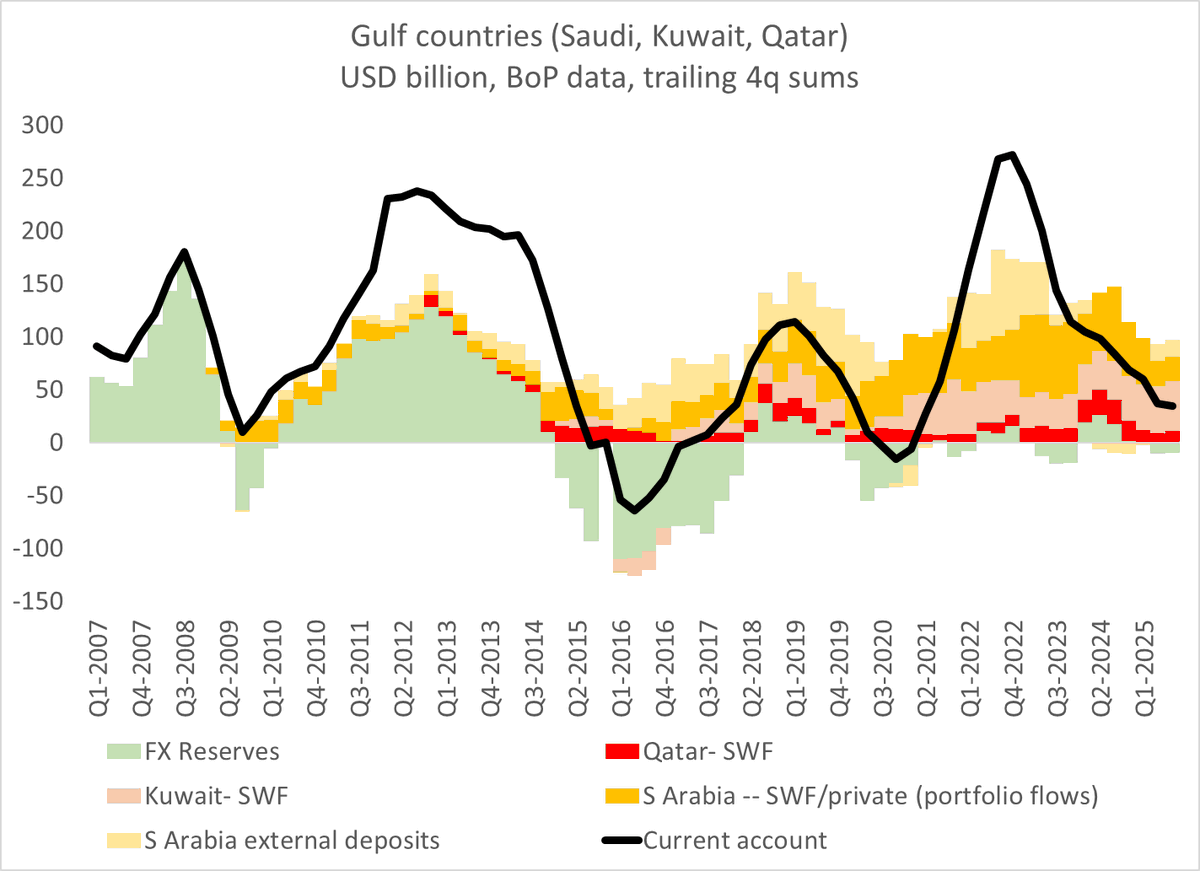
But the bottom line is that going into this shock, the big surpluses were in Asia not the oil exporters ... and there wasn't a big flow into liquid offshore dollar markets from the oil exporters (there was a modest flow into equities & "AI" investments)
12/