Intuit paid $12B for Mailchimp in 2021 and is selling it to Bending Spoons for $3.68B (2.9x revenue).
Run Mailchimp at Bending Spoons' 54% margin and that's ~5x operating profit. Intuit is also putting $368M of the proceeds back into Bending Spoons stock.
Upgraded to the latest iOS and was excited to try the new Siri. Asked it the car wash test: wash is 40m away, walk or drive?
The car stays at home, apparently…
#AppleIntelligence
Upgraded to the latest iOS and was excited to try the new Siri. Asked it the car wash test: wash is 40m away, walk or drive?
The car stays at home, apparently…
#AppleIntelligence
Gross margins have always been an indication of the efficiency of someone’s product.
Good margins = efficient to run.
Hence for years SaaS companies were considered superior on unit economics to services and on-prem deployments.
Many might be biased now and kick the can down the road but I agree. They are wrong.
Wow! Berkshire Hathaway is going big on Bending Spoons.
Luca Ferrari called them “amongst the finest and most respected capital allocators in the world”
Bending Spoons is up 41% today.
Berkshire agreed to invest an additional $330 million in Bending Spoons, bringing its stake in the Italian technology company to 4% just three months after backing its initial public offering. https://t.co/dMpezHmYyM
I’m intrigued by how salesforce structures deals and makes the maths work.
A series C VC already underwrites a steep growth (say 2x a year for the next 2-3 years on ~30m ARR).
Salesforce comes in at 33% premium on that C valuation, paying 65-70x revenue while they trade at 5x, assuming they underwrite a faster growth + cashflows.
Surely they pay in cash - why would the founders or sequoia take a stock that’s ~12% down YTD.
They have to do the latest 2-3 integrations in parallel and enable their sales and customer success teams to deliver revenue synergies.
I just can’t see it…
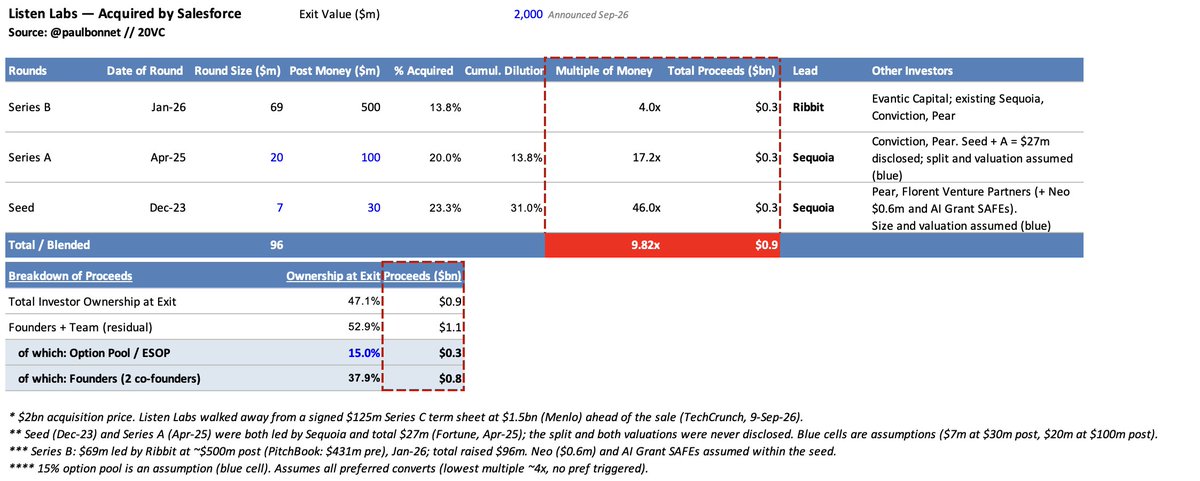
Salesforce acquires Listen Labs for ~$2b. But who gets the 💰? My usual breakdown below 👇
The company was founded in Sep-23 and had raised less than $100m. Investors will share ~$850m of profits on $96m invested, a ~10x blended.
From a huge pivot to a unicorn valuation term sheet they refused, this is truly a wild story ✍️. In the end an incredible outcome for all involved.
So let's dive in!
1) The boldest move: walking away from $1.5b 🎲
Listen Labs had a signed $125m Series C term sheet from Menlo at a $1.5b valuation... and walked away from it to sell to Salesforce at ~$2b.
This takes a huge amount of courage: few founders turn down a signed unicorn-plus round. @itsalfredw and @florian_jue did it 2.5 years after founding.
Huge congratulations are in order for the discipline and execution of the founders here.
2) Founders and team: a life-changing outcome in under 3 years 🥳
By my best estimates, founders and team still own over half the company.
At $2b, that's ~$1.1b for them to share. Specifically, assuming a 15% option pool, that is ~$300m for the team and ~$750m for the two co-founders.
And, as was the case with Hugging Face, this is all from a pivot. They originally built an AI customer-interview tool to understand why their viral app BeFake was growing, then realised the tool was the business!
3) Sequoia's Bryan Schreier did it again 👑
What few people know is that Bryan was an early backer of Qualtrics... the category Listen Labs is disrupting.
Now he led both the seed and the Series A here. By my estimates, those two rounds will return ~$670m combined, or ~25x on ~$27m invested, in under three years.
Pattern recognition and industry knowledge have their perks, it would seem!
4) Ribbit: 4x in 8 months ⚡
Ribbit led the $69m Series B in Jan-26 at ~$500m. At $2b, that's ~4x in 8 months. Unbelievable IRR and a great return on a meaningful cheque.
5) Neo does it again, congrats @apartovi 🎯
Listen Labs went through the Neo accelerator early on, which came with a $600k SAFE. On my estimates, that cheque is worth ~$25m+ today.
This comes just three months after Cursor's acquisition (a cool >1,000x for Neo). What a hit rate!
This one is very straightforward: it is a massive win for everyone. And so congratulations to all involved: Sequoia, Ribbit, Conviction, Pear, Neo and the team!
Unpopular opinion: AI model companies in the mature modalities (text, voice, speech) consolidate faster over the next 12 months
1/ valuations outrun revenue
2/ the OpenAI and Anthropic oligopoly is set
3/ Enterprise AI adoption is slow
@HarryStebbings It’s pretty funny how managed services companies attract >100x ARR multiples just because they have some “forward deployed” engineers implementing some sort of agents.
I also expect SaaS companies that managed to transform get a valuation premium.
A Nu/ Monzo combination makes sense.
Monzo struggled to expand to the US but a banking license in Ireland this year and wants to passport to Europe.
Nu is building a US bank following the recent charter approval.
Cross border between USD/GBP/EUR becomes cheap!
EXCLUSIVE: Monzo, the digital lender which has become one of Britain's biggest consumer banks, is in talks about a sale to Brazil's Nu Holdings which could value it at between £8bn and £10bn, ending the prospect of a near-term IPO of a UK fintech champion. https://t.co/V1IVOIJsLc
@garrytan Insurance premiums present a value pool that could have secondary benefit because of AI.
Think car/ travel insurance from autonomous vehicles.
Home insurance from robotics in manufacturing and maintenance management.
Business insurance etc.