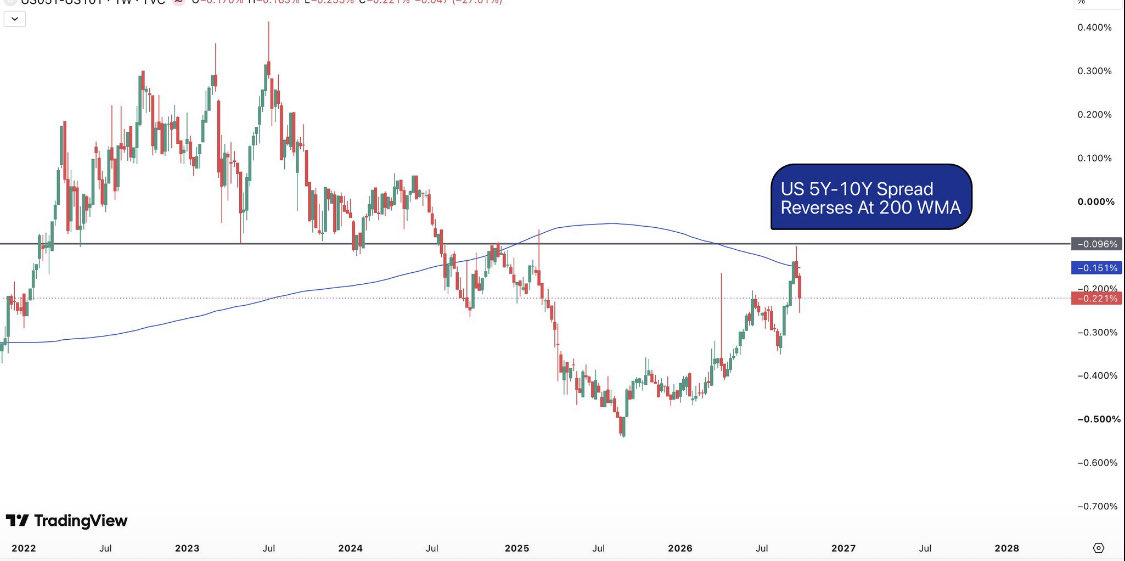
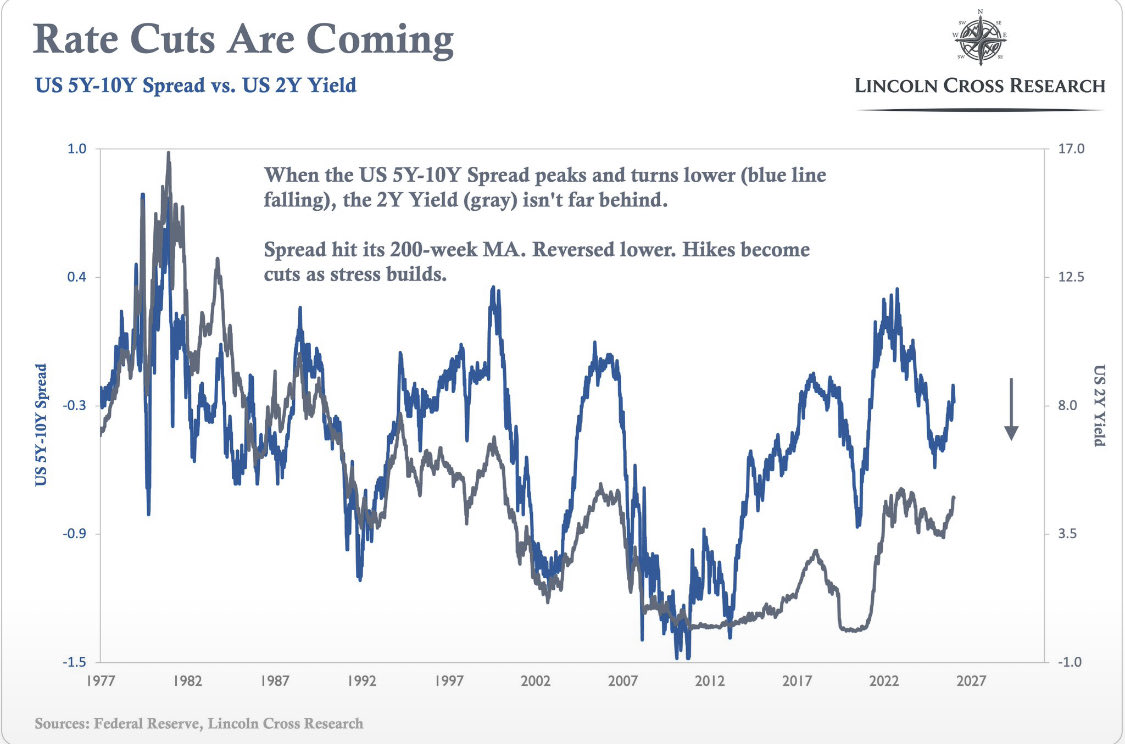
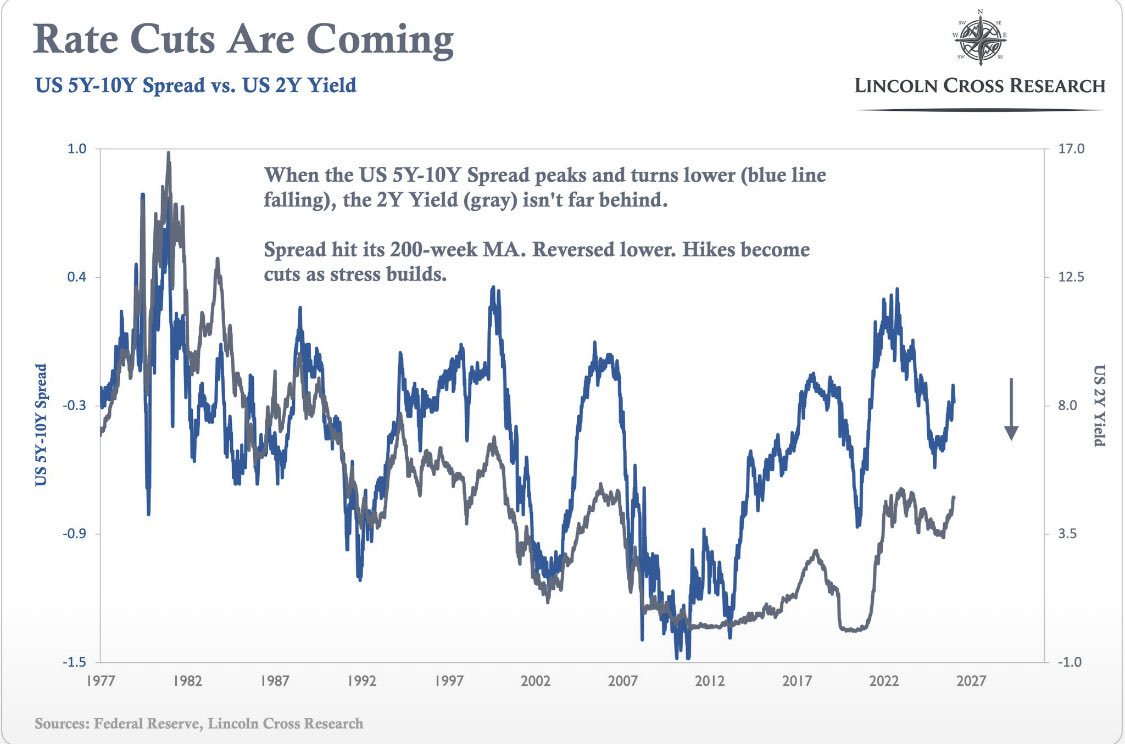
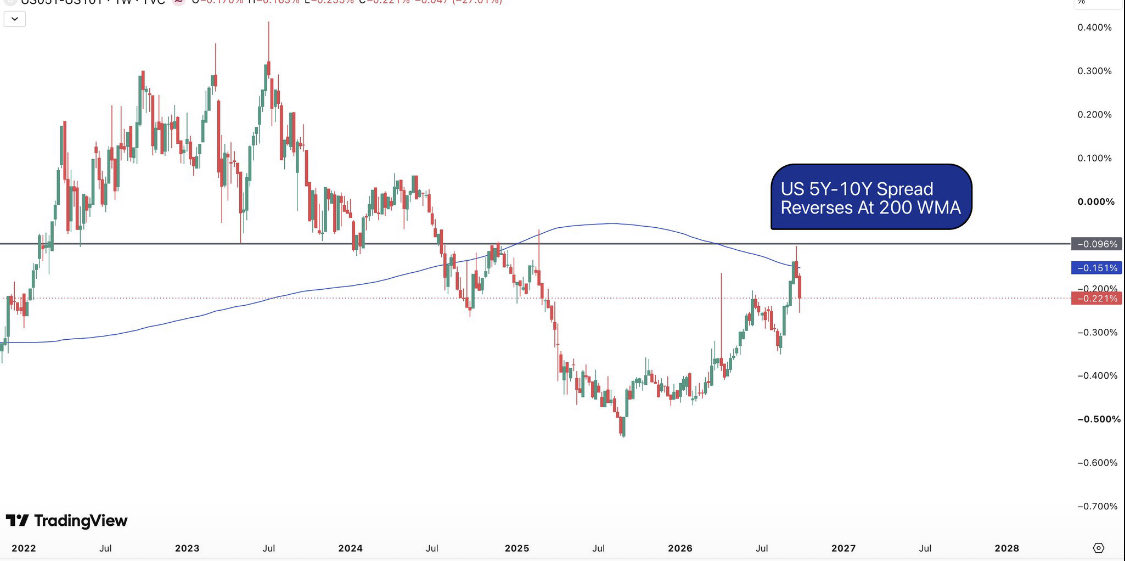
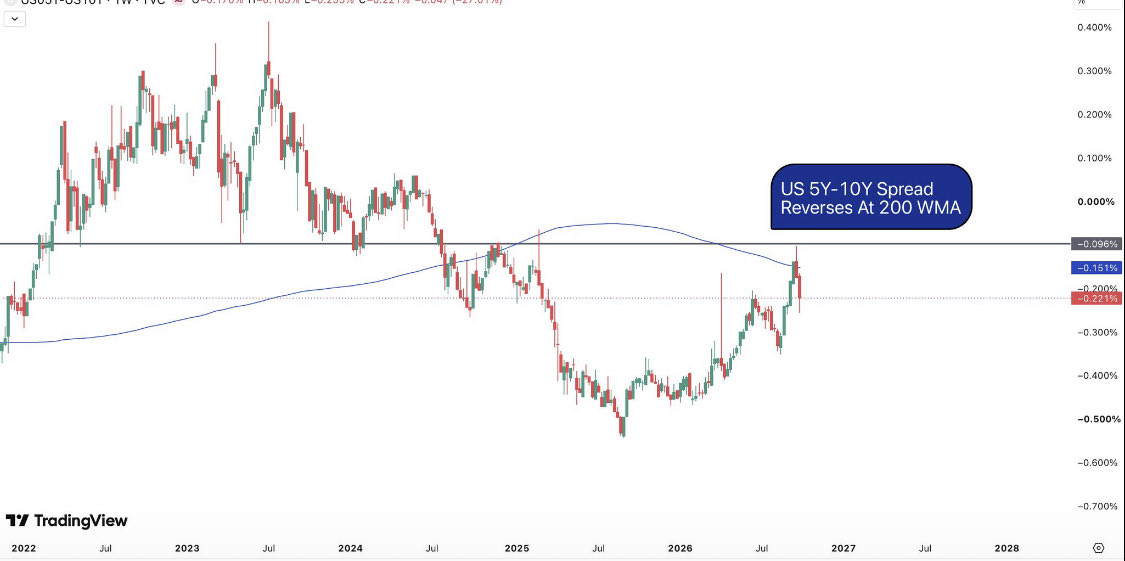
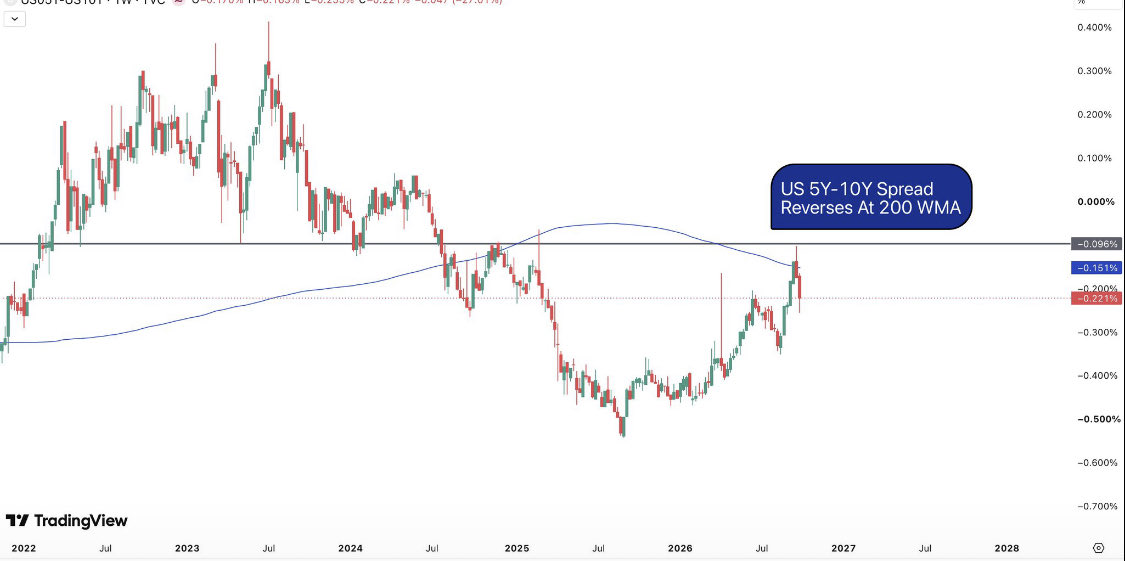
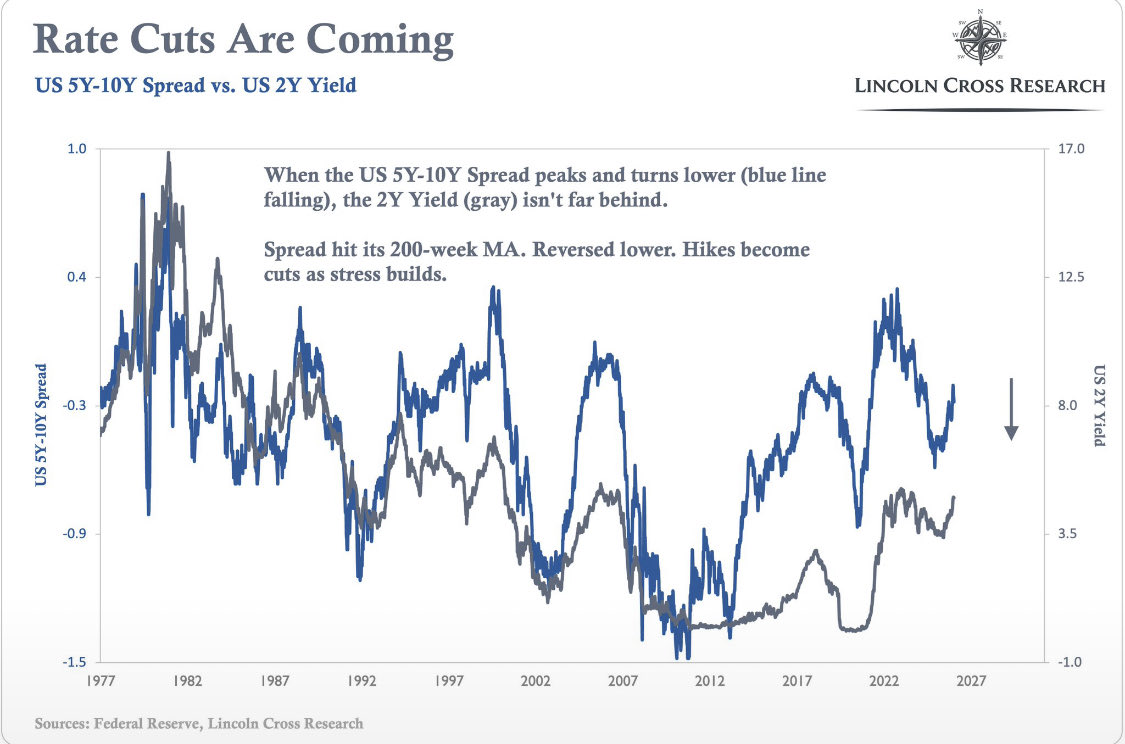
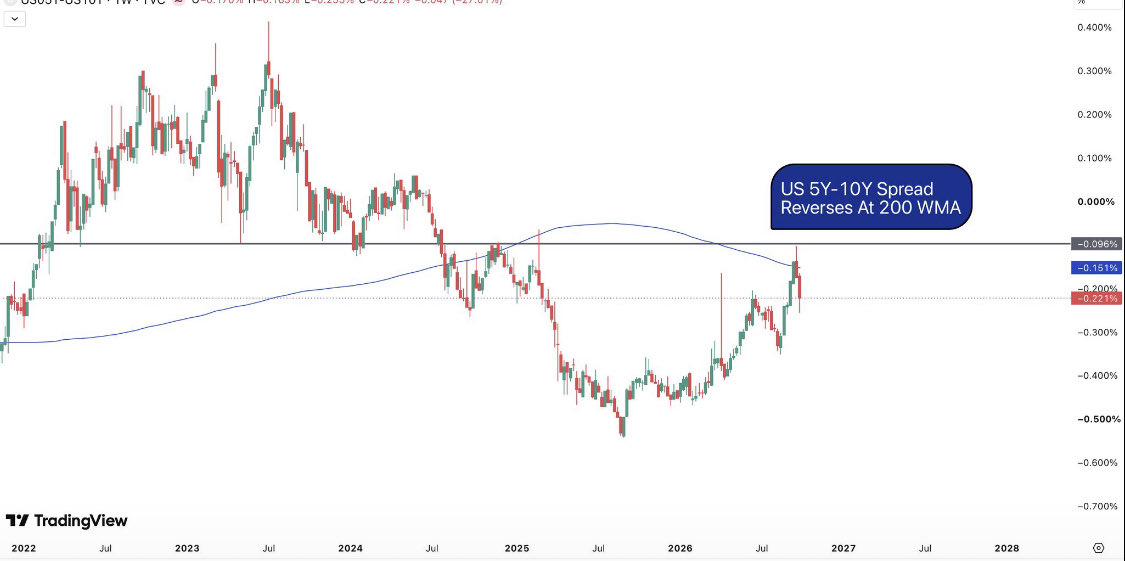
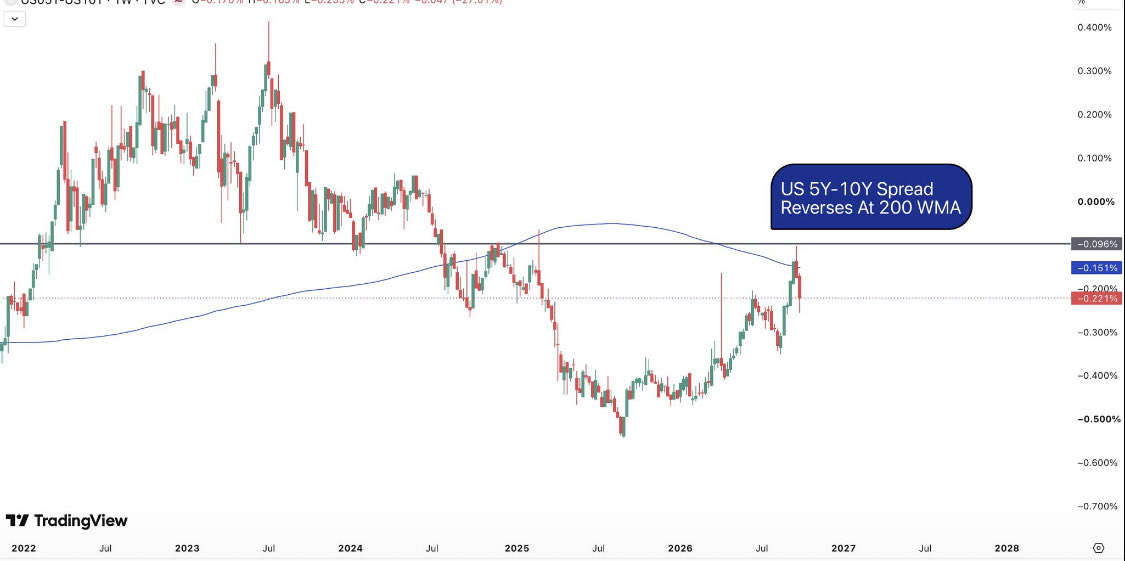
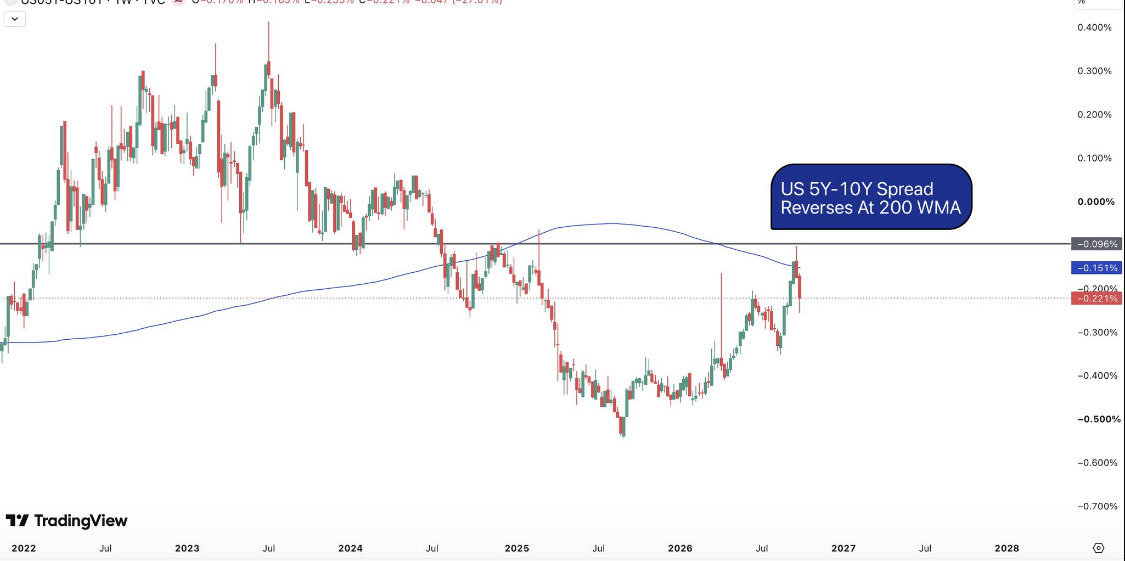
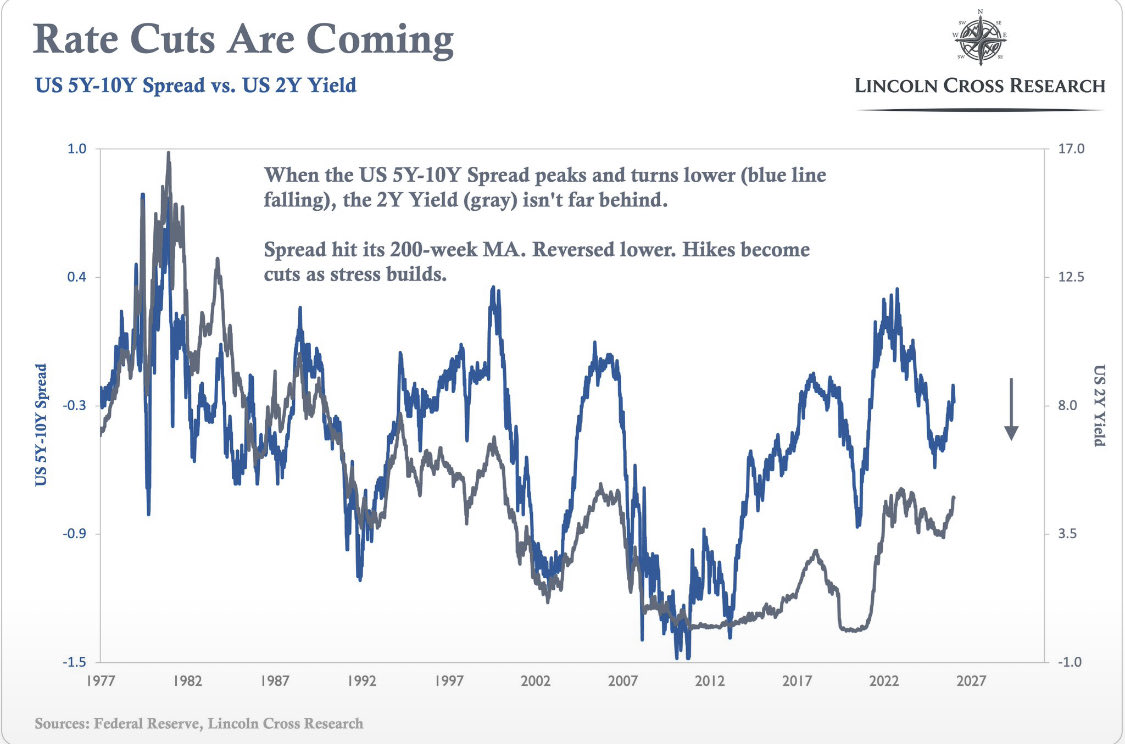
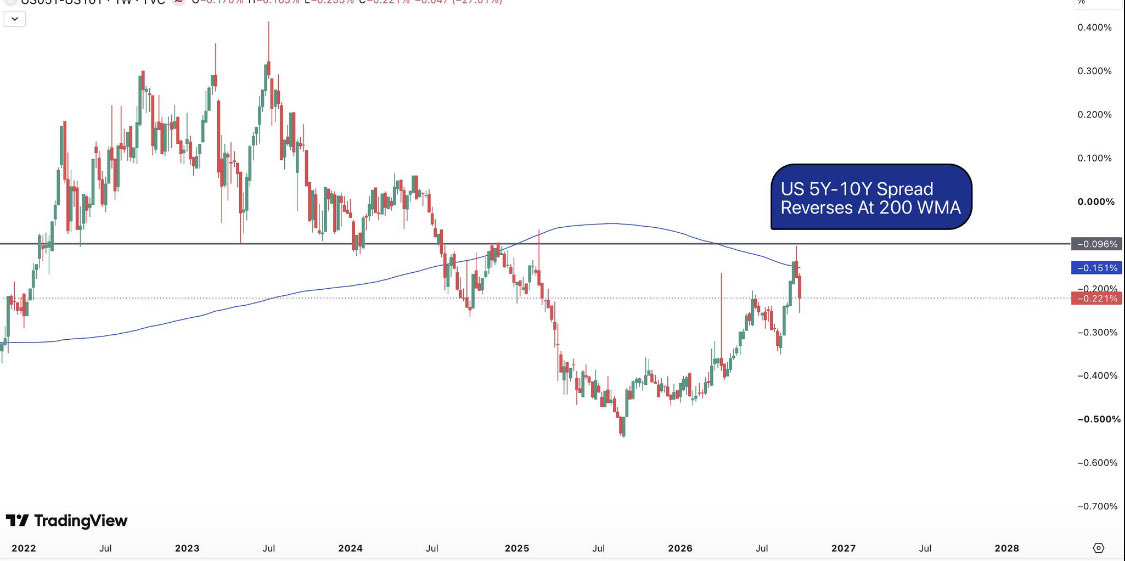
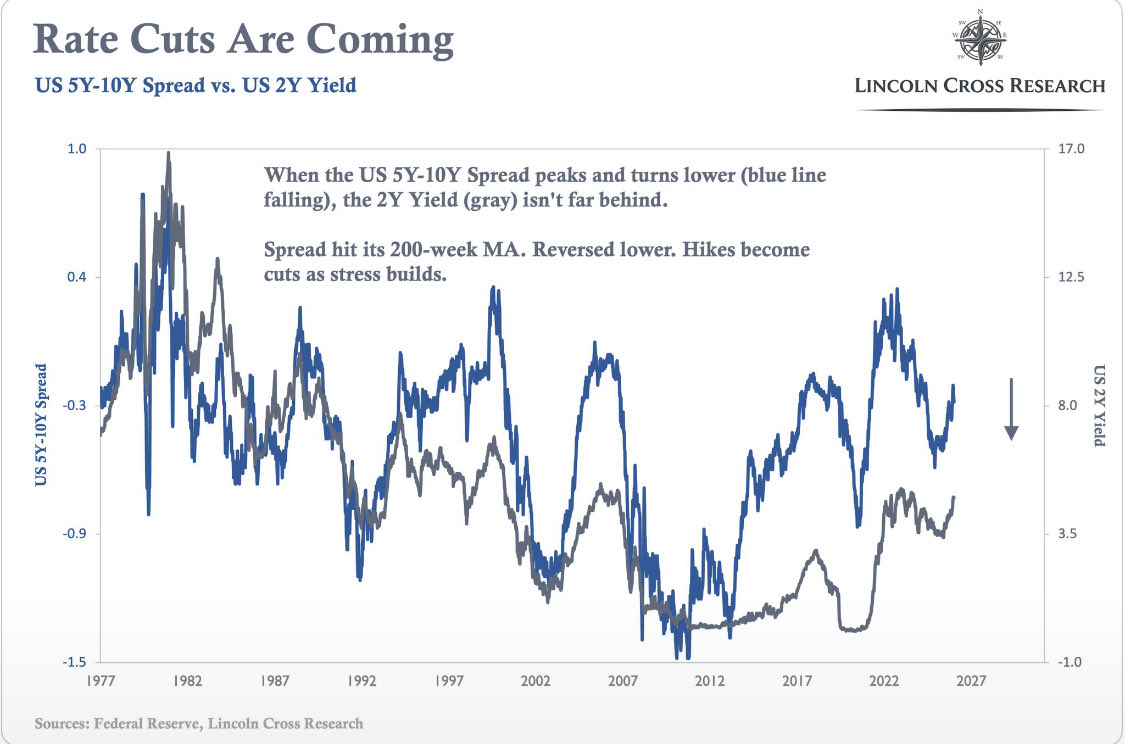
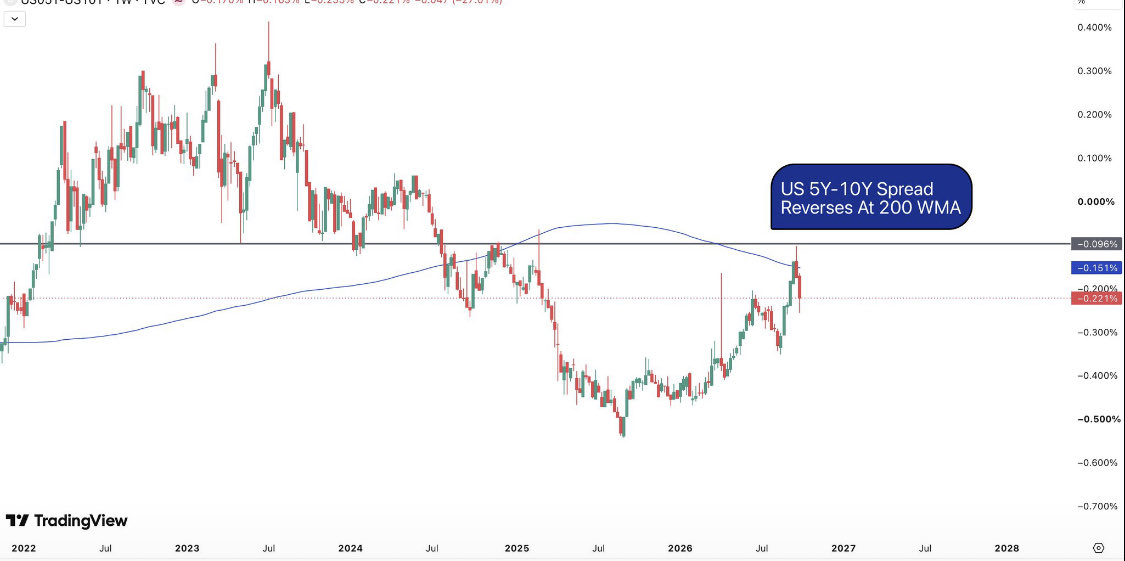
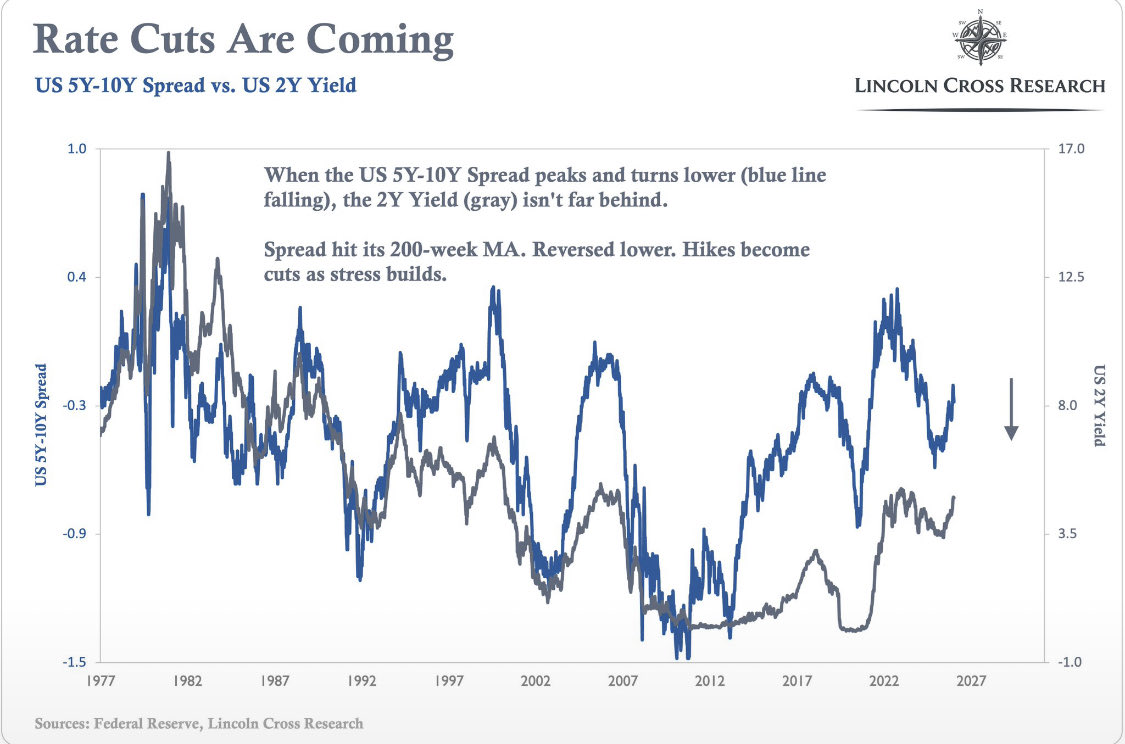
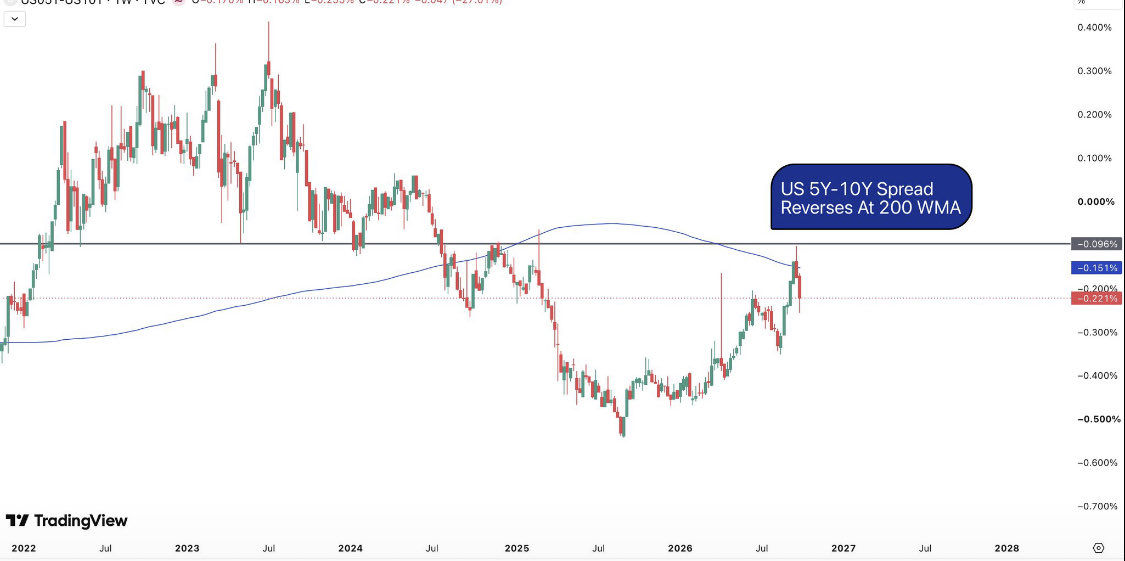
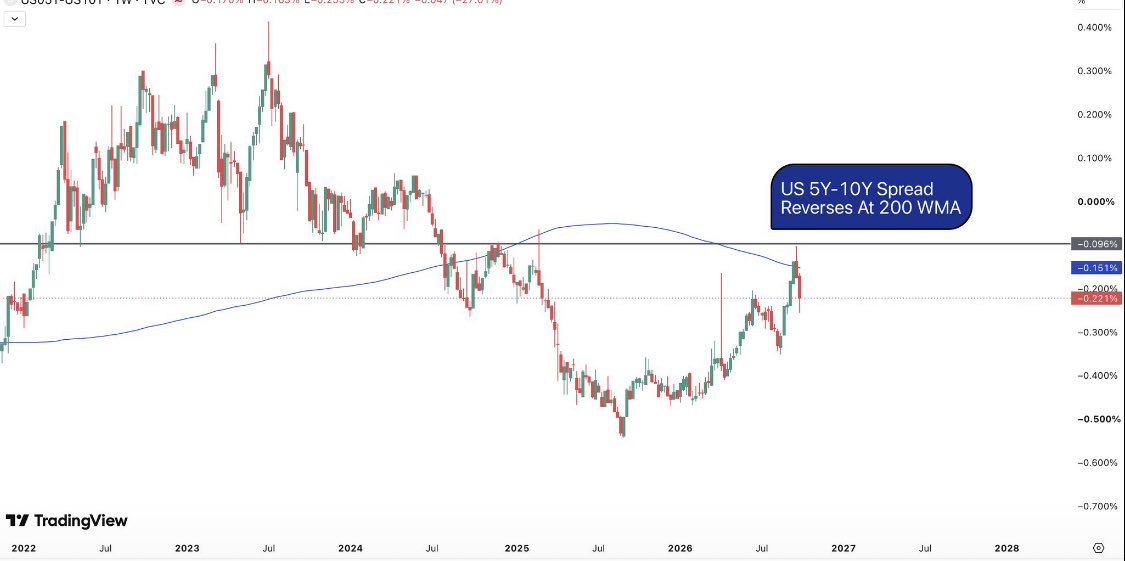
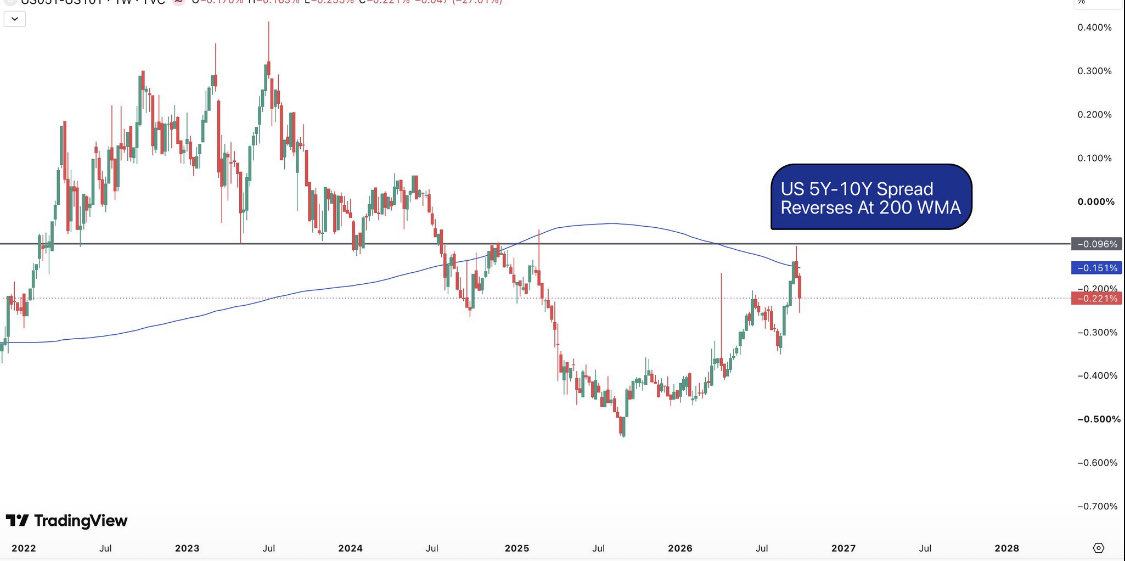
The value being offered in the bond market right now relative to the fundamentals is unrivalled by any other asset class.
People are afraid to buy bonds because they’re worried about headlines, negative momentum, and short-term losses.
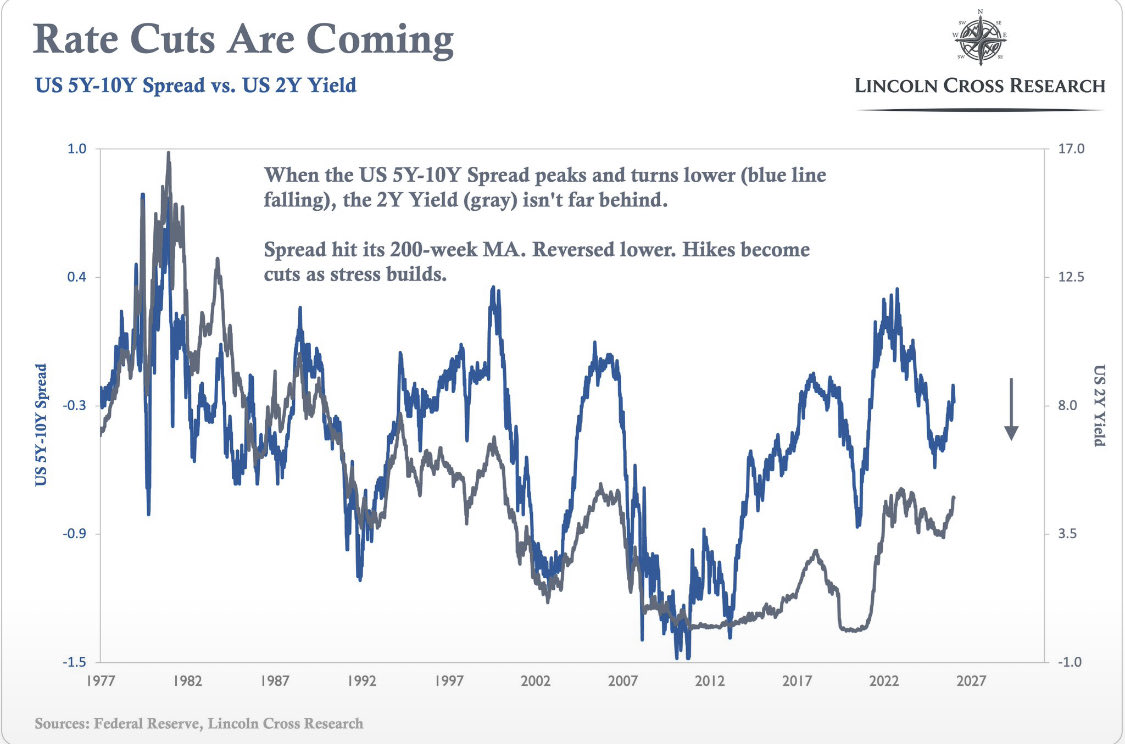
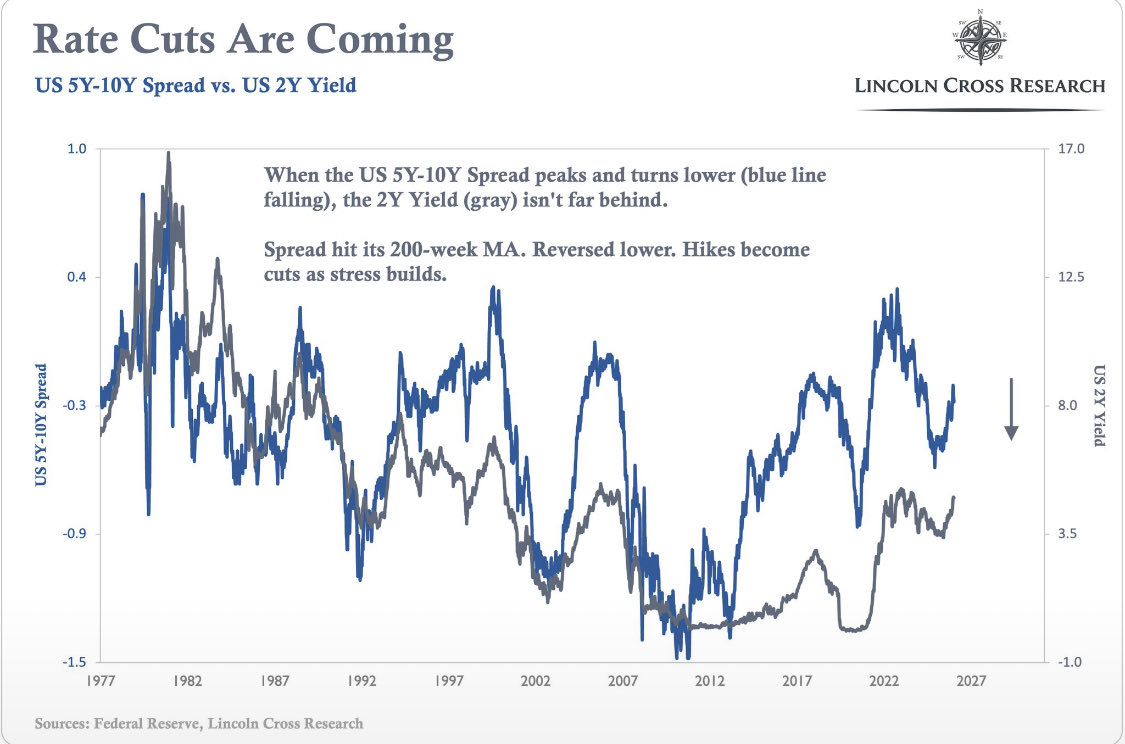
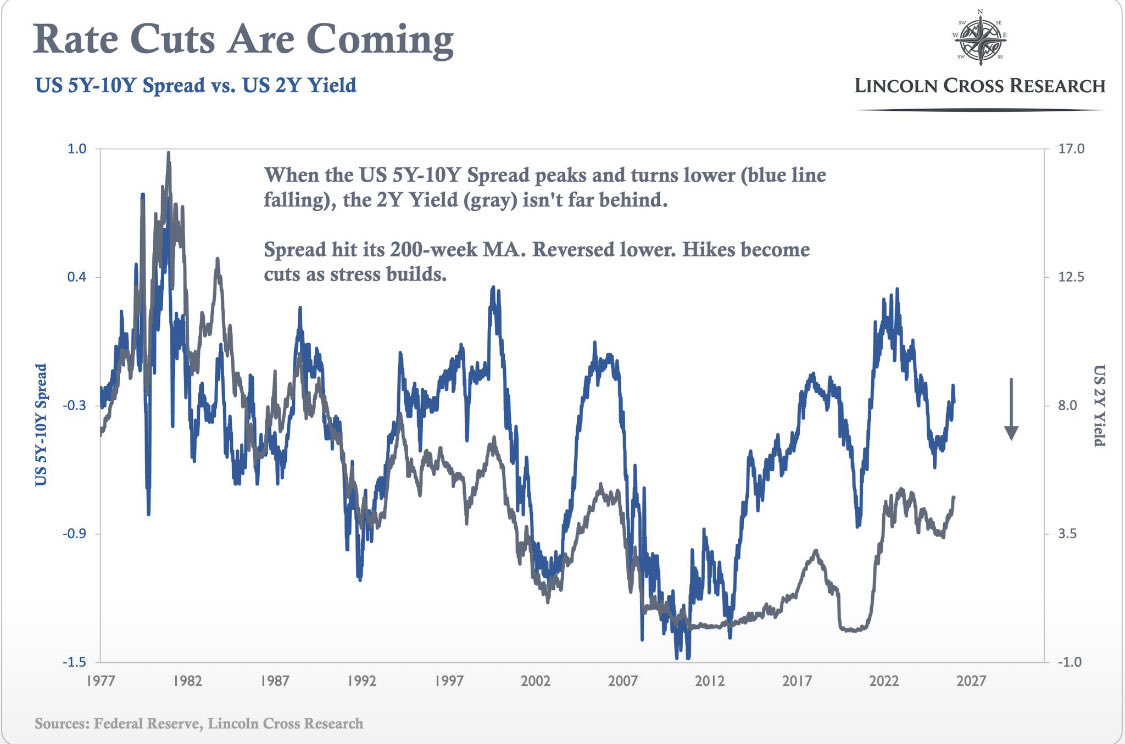
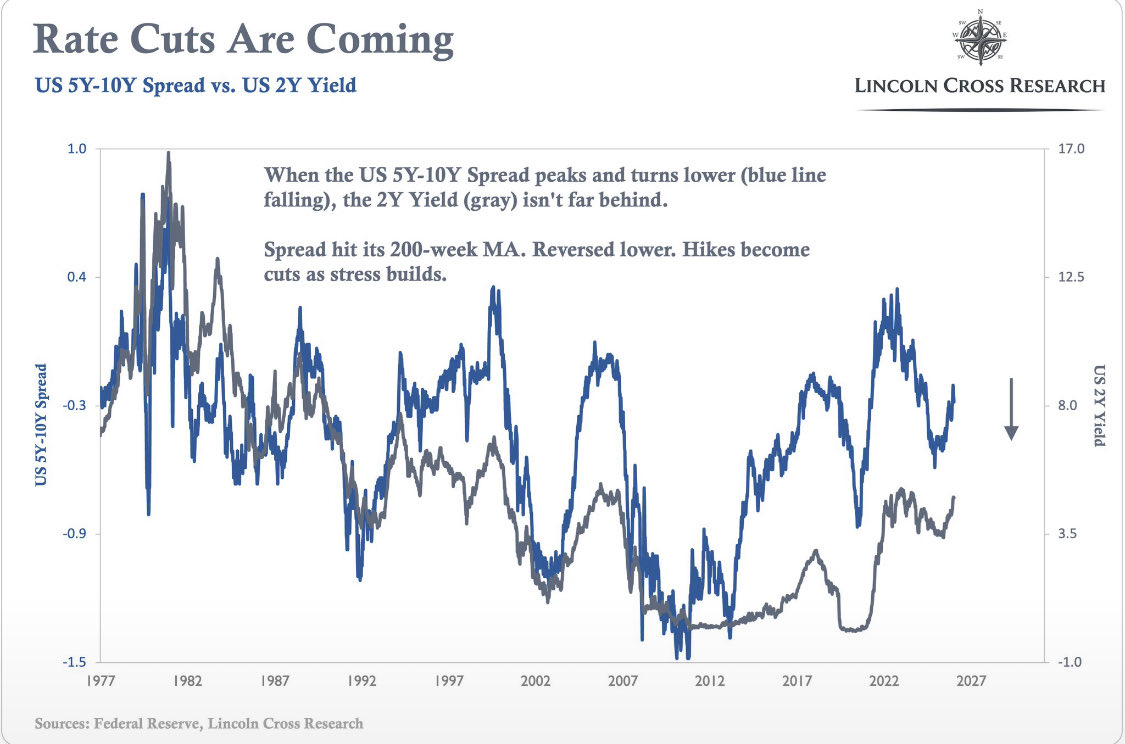
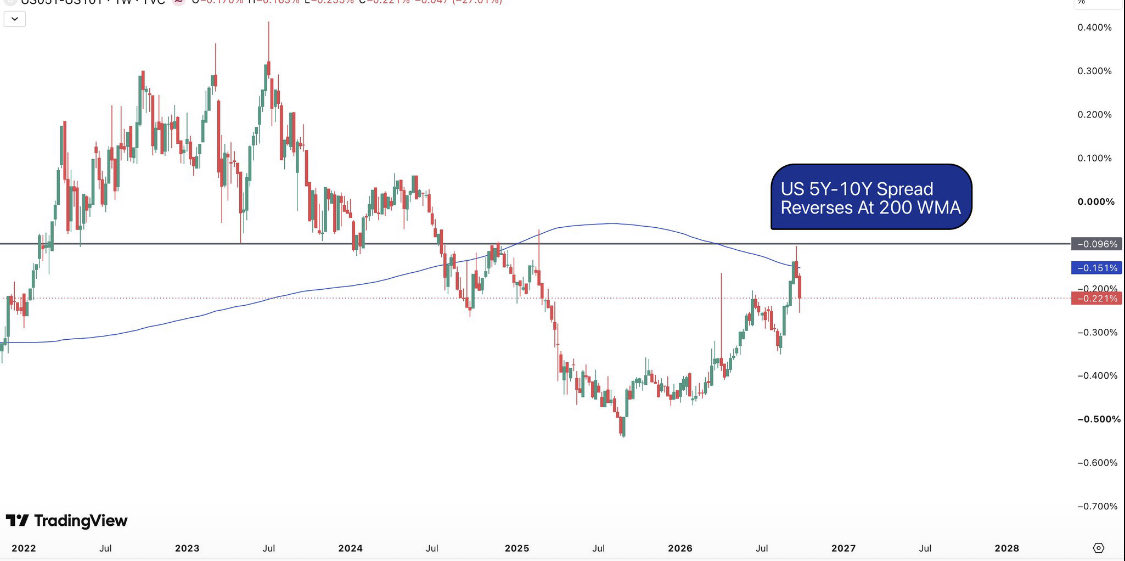
But, if you look out 6-12 months, you’ll realize in hindsight that bonds offered deep value at these levels and provide positive carry (yield) while awaiting a rally.
Remember the gold and silver longs that wouldn’t sell at ever-higher prices? What about semiconductors?
They’re now the bond bears who won’t buy at ever-lower prices.
When the momentum turns and the rubber band snaps, the upward correction will be just as violent.
Been there. Done that.
Bookmark it.
Market liquidity is falling RAPIDLY:
The G10 Excess Liquidity Indicator has dropped to its lowest level since early 2024.
This measures the gap between real M1 money supply growth and economic growth, and historically leads risk assets by around 3-6 months.
The move increasingly resembles the setup seen ahead of the 2022 bear market, when excess liquidity collapsed, and the S&P 500 subsequently followed with an over-20 % decline.
Today, the indicator is again rolling over aggressively, suggesting that liquidity conditions could become a significant headwind for equities over the coming months.
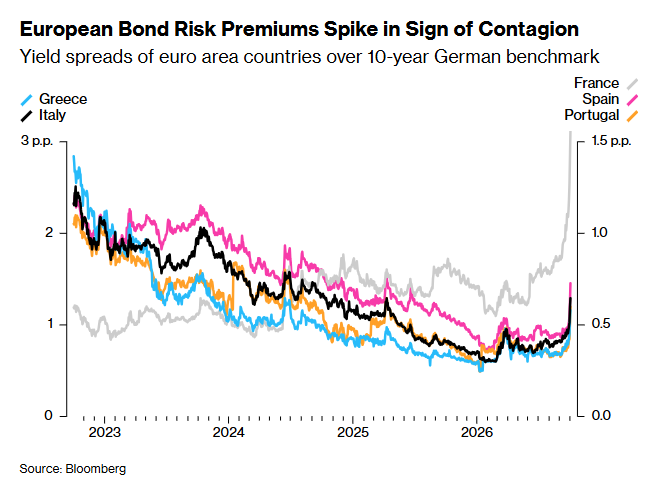
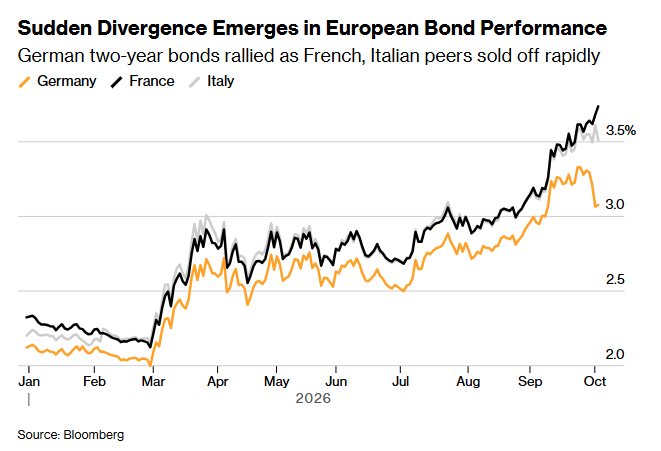
This is especially important as major central banks are now hiking rates, including the Fed, while global government bond yields are surging to levels not seen in decades.
If the historical relationship holds, the current decline in excess liquidity could leave equities increasingly vulnerable to any unfavorable news.
The 2022 liquidity playbook may be repeating.
People focus so much on US fundamentals, but I’ve said it many times, this is a global story.
Treasuries and $CHF will be the dominant safe havens when the chickens come home to roost.
BofA notes that "the biggest CTA story remains the persistent short Treasury position."
They say following NFP the initial declines in yields brought them close to cover levels, but the reversal left shorts intact.
"CTA Treasury shorts remain near maximum levels and are notably larger than they were during 2022, due to lower bond vol today."