Subscribe for 2 to 3 analyses of global SMID equities every week. Discover overlooked ideas and rethink familiar names. Published by Andrew Wong, ACA, CFA
💎 MY FAVORITE STOCK PITCH FROM THE LAST 24H
$MAB1.L pitched by @AndersonAn93989
Mortgage Advice Bureau is the UK's top mortgage network. Advisers plug into it for the software, the access to lenders and the regulatory cover. When a mortgage pays out, the lender's commission goes to MAB, which passes the adviser's cut along.
Revenue grew 20% in 2025. Then in early September management cut profit guidance because mortgage approvals came in lower than expected, and the stock lost 20% in one session, 490.5p to 392p on Sep 9.
Market trades it like a housebuilder, its total return moves with Persimmon. But before 2026 MAB always had the higher P/E of the two (P/E is the price you pay for each £1 of profit). Today it is 7.65x the next 12 months' earnings against Persimmon's 13.2x. Its own average since 2015 is 20.2x.
And it is the better business. 9% return on assets against Persimmon's 5%, with no houses, receivables or equipment to fund. Working capital is negative, so the cash arrives before it has to go out.
THE PART I LIKED
The author went through the succession trail. Founder and CEO Peter Brodnicki owns ~18% and is 64. Yaiza Luengo, the COO once seen as successor, left in May and the role was never filled. In July MAB hired a new CFO, Jo Stent, who years ago was an M&A Lead Advisor at Deloitte.
"With a high enough premium, the CEO/founder may be inclined to sell and enjoy his retirement."
Add the rest. Top player with only ~8.4% of a fragmented market, ~10% free cash flow yield, net debt immaterial so there is room to borrow.
£208m market cap at 361p when it was written. 332.5p at Friday's close.
Author owns the stock. Subtitle: "9% ROA, 10% FCF yield & a Prime Takeover Target"
So you’re telling me if I invest $1,000,000 into the 30-Year Treasury at 5.60%
I will get $56,000 every year for 30 years for literally doing nothing
You could easily retire off that income.
Why aren’t more people doing this?
At the time of publication, Siltronic ($WAF GR) trades at EUR 68. This is well below its previous takeover offer of €145.
Siltronic offers a strong risk/reward setup as FabNext scales and quarterly earnings surprise to the upside.
Full analysis:
Siltronic: Reaching an inflection point
https://t.co/ZpouPlodsr
(5/5)
Is Siltronic AG ($WAF GR) an overlooked turnaround in the semiconductor sector?
As the world’s 4th largest semiconductor wafer maker, the market views it as a struggling business because it has been loss-making while AI giants soar.
However, semiconductor shortages travel upstream—and raw wafer suppliers are reaching a cyclical inflection point.
(1/5)
Siltronic's ($WAF GR) recent net losses aren't due to structural decay.
Top-line pressure came from USD/EUR exchange rate headwinds and closing a legacy small-wafer division, while net losses stem from accounting depreciation on its new FabNext facility in Singapore.
As production ramps, unit costs will drop and profitability will return.
(4/5)
With a capital-light business model, depressed 8x P/E valuation, clear M&A catalysts, and a strong regulatory moat against tech disruption, MAB1 LN stands out as a compelling opportunity.
Full analysis:
8x PE for the UK's Top Mortgage Network
https://t.co/wjpGoxev06
(5/5)
Mortgage Advice Bureau ($MAB1 LN) trades at just 8x NTM P/E despite generating a 9% ROA and a 10% FCF yield with immaterial net debt.
The market recently dumped the stock following a short-term guidance cut, grouping it with cyclical homebuilders.
However, its high-quality, capital-light network model suggests this cyclical weakness is over-extrapolated.
(1/5)
Is AI a threat to mortgage advisers?
The risk is minimal.
Advisers deal with complex cases (self-employed applicants, poor credit history) where generative models frequently struggle.
Furthermore, the industry is heavily regulated by the FCA, and consumer trust remains paramount—surveys reveal only 5% of homebuyers are willing to rely on an AI chatbot for their mortgage.
(4/5)
Mortgage Advice Bureau ($MAB1 LN) shares are down more than -50%.
The market sees it as a lousy cyclical housing business.
However, my preliminary research suggests the market is underestimating the quality of its business and over-extrapolating the headwinds.
I will publish my full analysis today.
Sign up to get it for free. Link in comments.
Is there an opportunity in UK's top mortgage network?
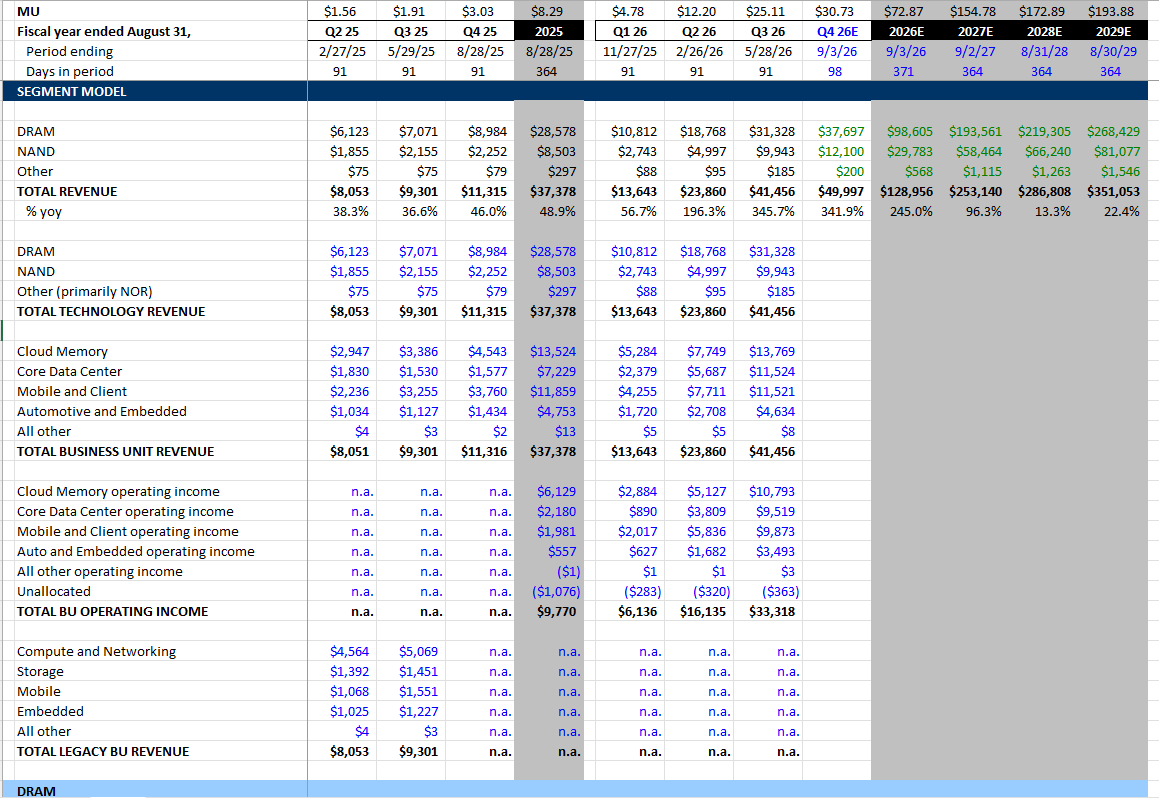
Today is the day that AI passed the "financial modeling Turing test" for me.
A "push button" build from scratch Skill that one-shotted a model on $MU that is indistinguishable (to me) from a model that a junior analyst would build from scratch. With full, impeccable adherence to all aspects of who i like to format, design & build models (took a few turns to dial it in).
Opus 5.5 is unbelievable.
From China’s leading sportswear brand trading at 9x P/E to an iconic UK footwear brand yielding ~10% FCF, deep-value opportunities often hide behind temporary market noise.
Want to unpack the full breakdown, inventory metrics, and valuation models?
Click on the link to read the full analysis:
Yet Another 2 Attractive Ideas
https://t.co/m9Ki1izK3S
(5/5)
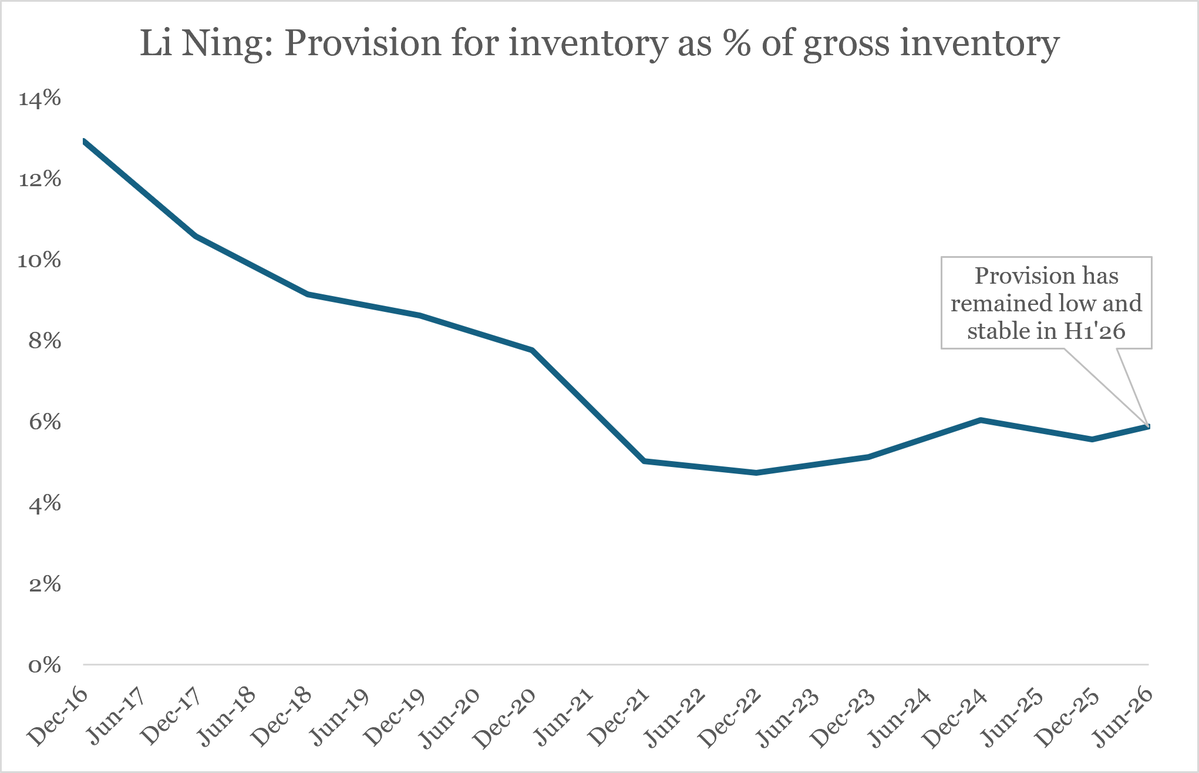
The market is pricing Li Ning ($2331.HK) like it’s facing another 2011–2017 inventory crisis, but the balance sheet tells a completely different story:
• Inventory write-down provisions remain low and stable at 5.9% (vs. 12.9% a decade ago).
• 77% of inventory is new product (up from 56% in 2016).
At ~9x NTM P/E, markets are pricing in a prolonged slump while business health is significantly better than expected.
(1/5)
The setup for an M&A or turnaround catalyst at Dr. Martens ($DOCS LN) is intensifying:
• Primary PE shareholder Permira holds ~38% via a 10-year-old fund nearing the end of its life cycle.
• Activist investors Marathon Partners and Sparta Capital are sitting on unrealized losses with heavy incentives to push for operational fixes or a company sale.
(4/5)