"@anthpb
ranks in roughly the 96th–99th percentile on a composite of originality, objectivity, and accuracy among all X users." –@grok
https://t.co/TOsye86B6Z
Again, burden of evidence:
aside from the fact that we already knew hyperscalers/large buyers were reported to be taking early deliveries in volume to secure their GB300 capacity, if renters were systematically deferring from GB300 (or even B200) because they cannot reliably power or cool them, and shifting to more operational Hopper or earlier Blackwell systems, we would expect absolute pressure on the newer SKUs as demand migrates – but there's no clear public evidence of a decline or deceleration in GB300 sales/shipments and available data points instead indicate continued strong (and in several estimates, accelerating) demand and deliveries...
unless, are you expecting an inflection downward in GB300 sales...? otherwise, these pricing signals suggest the narrative "shadow glut" in question here is semantic fearmongering...
$crwv theoretically profitable on net margin basis in 2028 with ~$1B net profit (after -$7.8B interest expense) on -$20B D&A...
EBITDA margins pretty steady 60~63%¹ and EBIT margins 16~18%², so really a bet on useful life of GPUs – lotta operating leverage on residual revenue after current 6-year accounting depreciation schedule³ (e.g. second-cycle contracts, inference workloads, etc)…
__
¹consensus higher on 2028FYe EBITDA ~67%/$29B
²consensus higher on 2028FYe EBIT margins ~20%/$8.5B
³management loves example of A100s contracted into 2029, but past is prologue and that's where markets get made
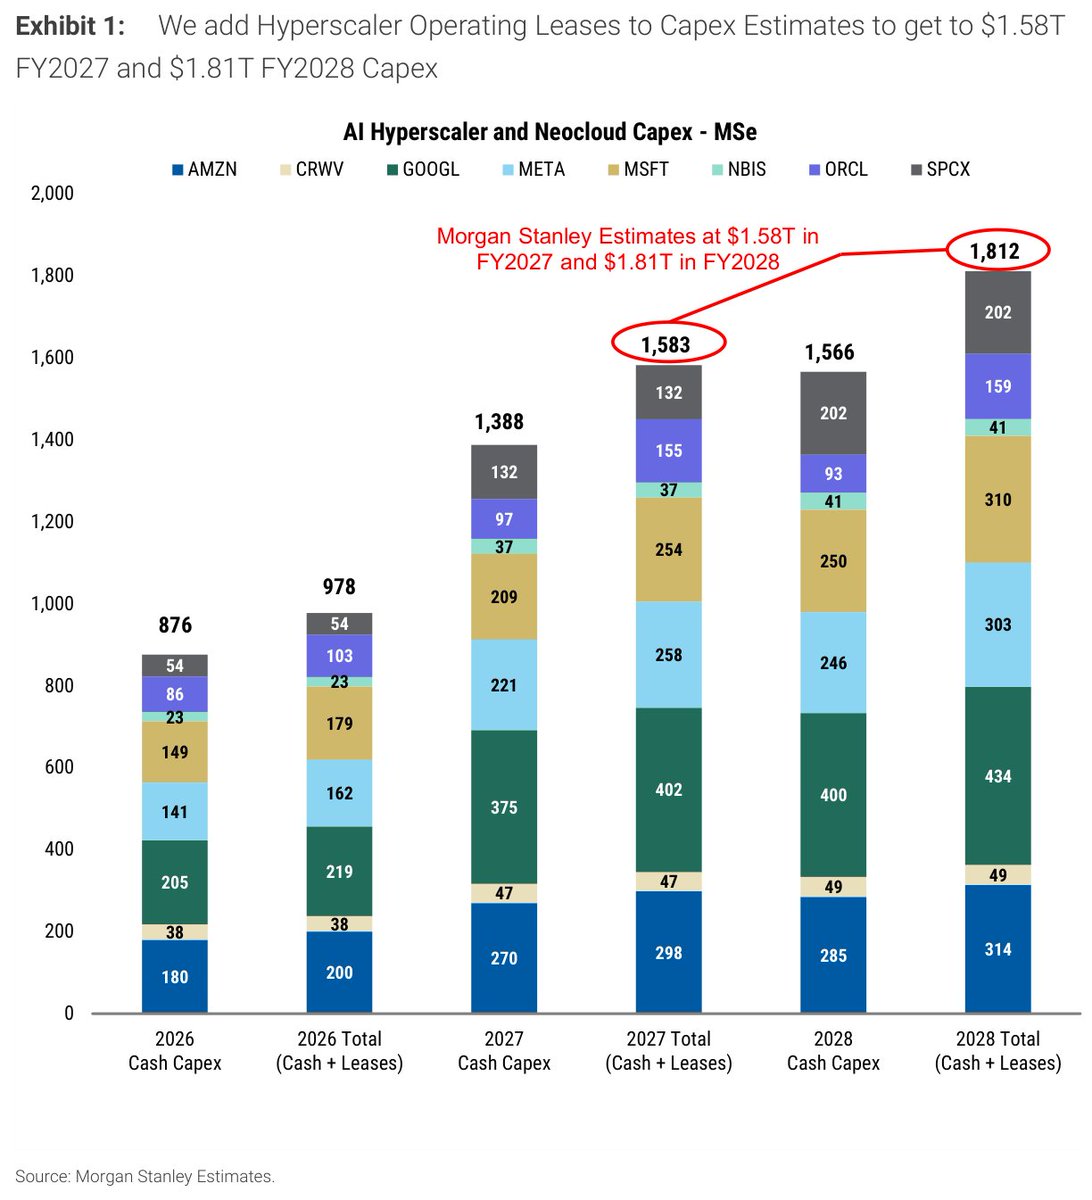
fwiw, Morgan Stanley's AI capex forecasts have been (and remain) higher than most other comps¹ because:
1️⃣ less deduplicating of neocloud spend (e.g. double counting more HCP/lab spend through neoclouds than other sell-side estimates²)
2️⃣ just higher cost/spend estimates 🙌
__
¹e.g. https://t.co/O2OYj6v4C8
²MS's HCPs = Microsoft/Amazon/Google/Meta, whereas most estimates include Oracle, so deduplication apples-to-apples is hairy
/6
...AI GAP PROPOSAL > MACRO POLICY > https://t.co/qSrQzKjXSY:
I.5️⃣ TAX REFORM:
"the tax reform package below systematically levels-the-playing field between capital inputs and human labor, ensuring that market forces, rather than tax arbitrage, dictate the optimal allocation of work, including...
a. HARMONIZING CAPITAL VS LABOR (CAPITAL GAINS VS INCOME TAXES)
b. ELIMINATE STEPPED-UP COST BASIS³ FOR INHERITED ASSETS
c. REGRESSIVE PAYROLL TAX REFORM
d. LAND VALUE TAXES (LVTs)
––
³https://t.co/NeiTSpK0ET
hattip @EconomPic
/5
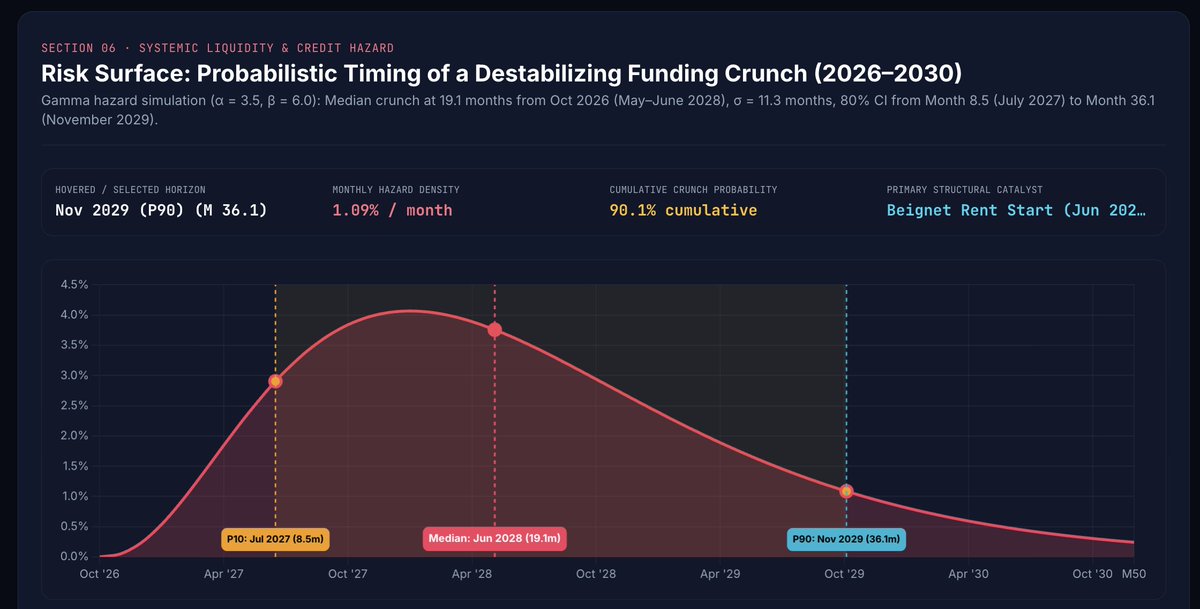
RISKS (HYPOTHETICAL CRUNCH SCENARIOS) – assuming a 100% total probability that a systemic liquidity or credit crunch occurs across the entire 2026–2030 forecast timeline, then there's an x% probability that the crunch occurs specifically within that modal timing window:
⚠️ Modal median:
45% conditional probability
+19.1 months (May–June 2028)
σ ±11.3 months = 80% CI July 2027 to November 2029
/4
IRR OUTLOOK (2026-30):
🔵 Datacenters:
+13.83% median IRR
(σ ±4.12% = 80% CI +8.54% to +19.11%)
🟣 AI Lab equity:
+11.29% median IRR
(σ ±28.26% = 80% CI -21.29% to +45.22%)
/3
FINANCIERS FUNDING FUTURE CAPEX – the following $3.15T "unfunded" future funding breakdown can be compared to $nvda (Nvidia ~$134B OCF TTM and $850B cumulative 2027-30e) and HCPs (hyperscalers ~$650B OCF 2026CYe and $5.2T cum 2027-30e)⁴ ⁵, nvm future debt and equity issuance:
• $1.85T from HCP⁴ direct capex (59%)
• $660B HCP off-balance sheet leases (21%)
• $320B Stargate JV⁶ (10%)
• $300B private equity/RE (10%)
• $250B private credit and bank loans (8%)
__
⁴HCPs include Amazon, Microsoft, Google, Meta, and Oracle
⁵again, "secured" includes current Nvidia + HCP cash flows, but not their future OCF growth, hench that future growth funding the "unfunded" bucket
⁶Stargate joint venture among OpenAI, Softbank, Oracle, and MGX
$amzn $msft $googl $meta $orcle $sftby #OBS #PE
/2
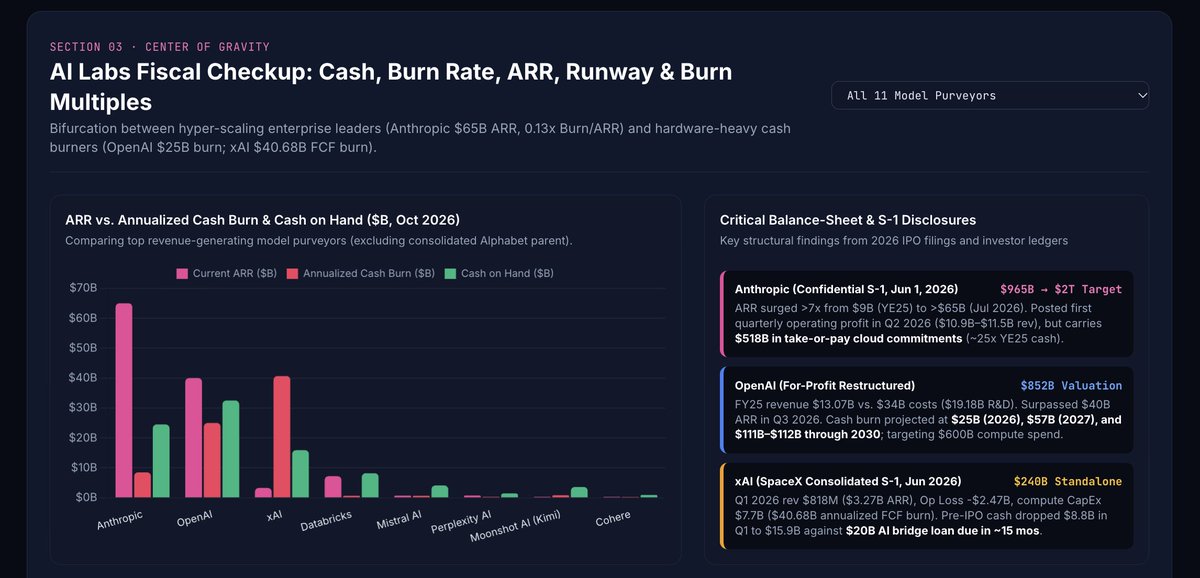
AL LABS FISCAL CHECKUP – both leading and also-ran labs seem to have secure R&D/lease pipelines, while $SPCX xAI remains the one dependent on capital markets in the short term:
• Anthropic:
34.6 month runway
0.13x burn/ARR ($65B ARR + $24.5B cash - $8.5B burn rate)
• OpenAI:
15.6 mo runway
0.63x burn/ARR ($40B ARR + $32.5B cash - $25B burn)
• xAI:
4.7 mo runway
12.4x burn/ARR ($3.3B ARR + $15.9B cash - $40.7B burn)
#xSI #leases
/0
...latest in my series on AI LAB AND DATACENTER FUNDING (previously https://t.co/3kaSYOkDmf) – chapters for the 10/2025 update that follows:
1️⃣ Datacenter Commitments (2023–2030)
2️⃣ Datacenter Funding by Status (Remitted vs Secured vs Unfunded)
3️⃣ AI Labs Fiscal Checkup
4️⃣ Financiers
5️⃣ IRR Outlook (Labs vs Datacenters 2026–2030)
6️⃣ Risks (Crunch Scenario Analyses)
/5
RISKS (HYPOTHETICAL CRUNCH SCENARIOS) – assuming a 100% total probability that a systemic liquidity or credit crunch occurs across the entire 2026–2030 forecast timeline, then there's an x% probability that the crunch occurs specifically within that modal timing window:
⚠️ Modal median:
45% conditional probability
+19.1 months (May–June 2028)
σ ±11.3 months = 80% CI July 2027 to November 2029
/4
IRR OUTLOOK (2026-30):
🔵 Datacenters:
+13.83% median IRR
(σ ±4.12% = 80% CI +8.54% to +19.11%)
🟣 AI Lab equity:
+11.29% median IRR
(σ ±28.26% = 80% CI -21.29% to +45.22%)
/3
FINANCIERS FUNDING FUTURE CAPEX – the following $3.15T "unfunded" future funding breakdown can be compared to $nvda (Nvidia ~$134B OCF TTM and $850B cumulative 2027-30e) and HCPs (hyperscalers ~$650B OCF 2026CYe and $5.2T cum 2027-30e)⁴ ⁵, nvm future debt and equity issuance:
• $1.85T from HCP⁴ direct capex (59%)
• $660B HCP off-balance sheet leases (21%)
• $320B Stargate JV⁶ (10%)
• $300B private equity/RE (10%)
• $250B private credit and bank loans (8%)
__
⁴HCPs include Amazon, Microsoft, Google, Meta, and Oracle
⁵again, "secured" includes current Nvidia + HCP cash flows, but not their future OCF growth, hench that future growth funding the "unfunded" bucket
⁶Stargate joint venture among OpenAI, Softbank, Oracle, and MGX
$amzn $msft $googl $meta $orcle $sftby #OBS #PE
…re datacenter construction delays from supply chain shortages and bottlenecks:
🛠️ 30–50% of 2026CY datacenter pipeline unlikely to come online before 2026YE (vs 36%¹ in 2025CY)...
↳ 16GW announced for 2026CYe (140 projects total)
🟰 5GW currently under construction
➕ 11GW announced but not started
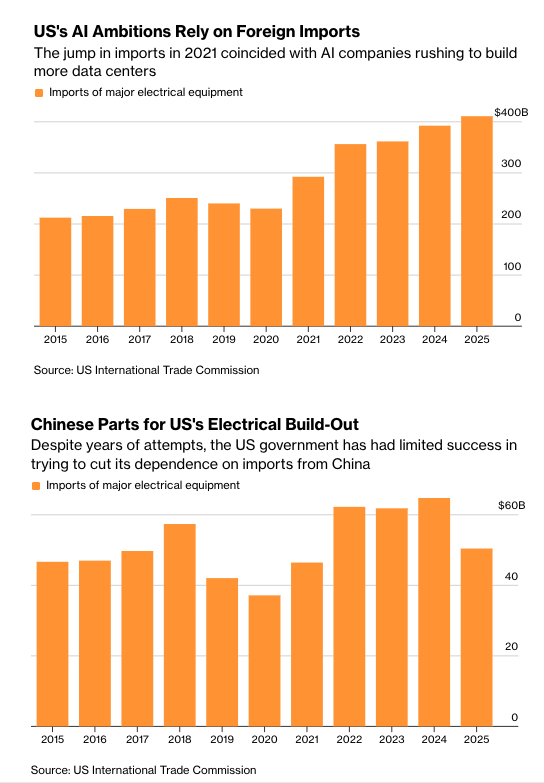
⚡️ "shortage of electrical equipment, such as transformers, switchgear and batteries… not enough domestic capacity to go around [so imports]… Electrical infrastructure adds up <10% of the total cost of the datacenter, but it’s impossible to build the operation without it"²
__
¹"in 2025, 26% of expected capacity slipped, and another 10% of projects pushed back their commercial operation dates without much notice" (https://t.co/Ct5Jr9JVcc)
²https://t.co/4Ir5Dw0Nx0
/2
AL LABS FISCAL CHECKUP – both leading and also-ran labs seem to have secure R&D/lease pipelines, while $SPCX xAI remains the one dependent on capital markets in the short term:
• Anthropic:
34.6 month runway
0.13x burn/ARR ($65B ARR + $24.5B cash - $8.5B burn rate)
• OpenAI:
15.6 mo runway
0.63x burn/ARR ($40B ARR + $32.5B cash - $25B burn)
• xAI:
4.7 mo runway
12.4x burn/ARR ($3.3B ARR + $15.9B cash - $40.7B burn)
#xSI #leases
/0
...latest in my series on AI LAB AND DATACENTER FUNDING (previously https://t.co/3kaSYOkDmf) – chapters for the 10/2025 update that follows:
1️⃣ Datacenter Commitments (2023–2030)
2️⃣ Datacenter Funding by Status (Remitted vs Secured vs Unfunded)
3️⃣ AI Labs Fiscal Checkup
4️⃣ Financiers
5️⃣ IRR Outlook (Labs vs Datacenters 2026–2030)
6️⃣ Risks (Crunch Scenario Analyses)
/5
…TLDR:
1️⃣ AI "center of gravity" R&D/startup funding runway is effectively secured through 2026h2⁸
2️⃣ AI "center of mass" datacenter capex is unfunded atm:
i. The "Power Wall" energy crunch
is already here⁹
ii. The "Funding Gap" cash crunch
escalates 2026-30
(+23% CAGR for cumulative $2.76T
funding requirement ex-$2.44T
self-funded from HCP cashflows)
⁸https://t.co/LZ8IBl3PJd
⁹https://t.co/yXmLvC8IIw
$MU $SNDK $WDC
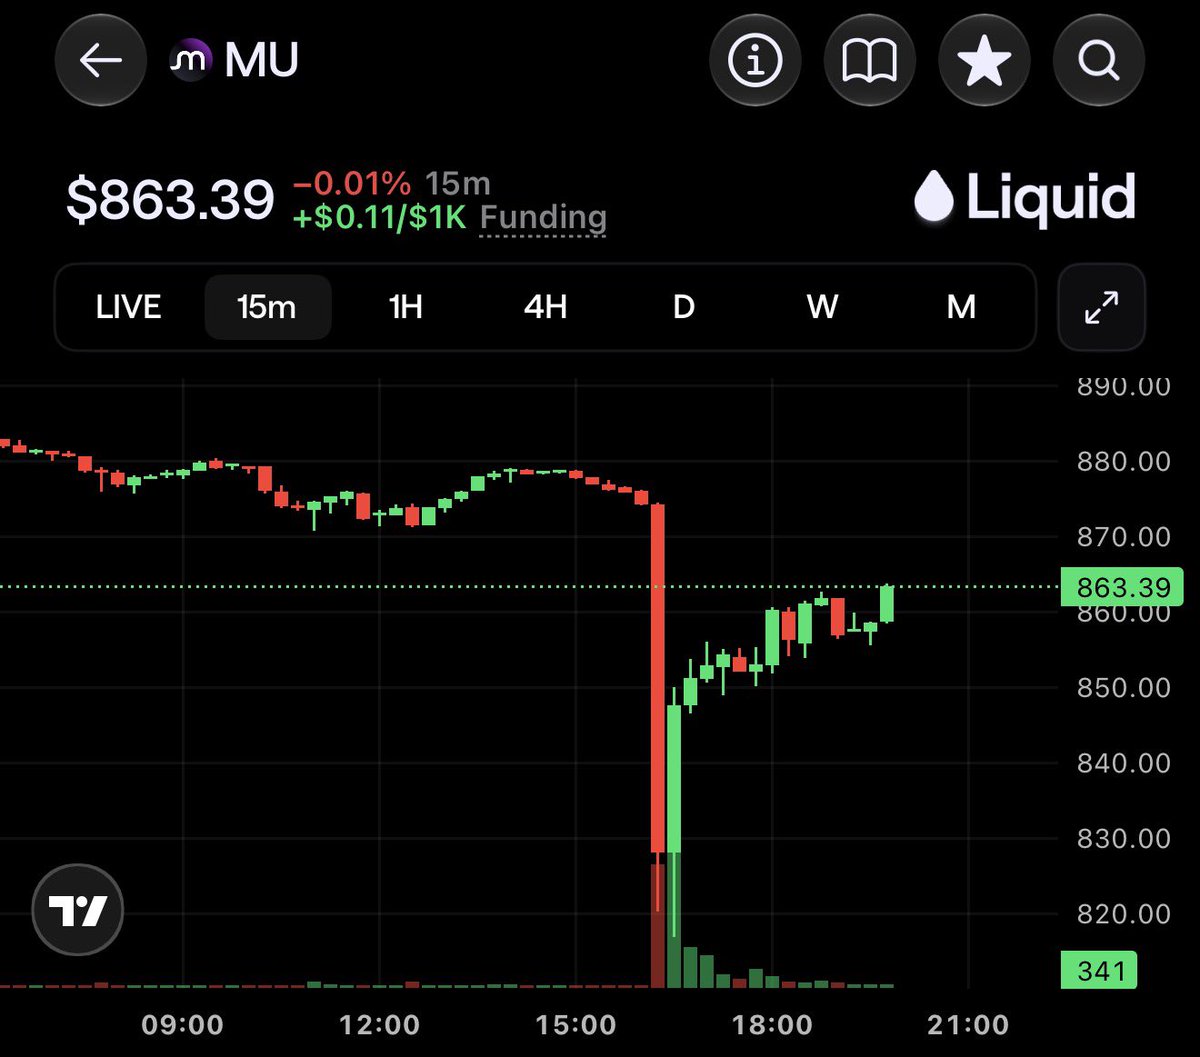
DeepSeek is back at it again.
Diving deeper, this happened on a Saturday, no less, so the markets haven't had time to react. Only the weekend perps have.
The headline driving it is DeepSeek's claim that the new model needs 4x less memory per token.
That reads like less memory demand, until you look at the rest of the release:
+ The model is still huge. It has 552B parameters, and all of them have to sit in memory to run, even though only a fraction is active at a time.
+ It handles 1M tokens of context. Longer context means more memory per user.
+ It's priced at about $1.20 per million output tokens. Cheaper tokens have always meant more tokens used.
+ DeepSeek ran out of compute this week. It had a five-hour outage that experts blamed on not having enough capacity. A company that keeps making its models leaner and still can't keep its service up is evidence that demand is ahead of supply.
The weekend market has mostly recovered so far, so expect some reaction at Monday's open, but I wouldn't be surprised if the market shrugs it off by 10am.
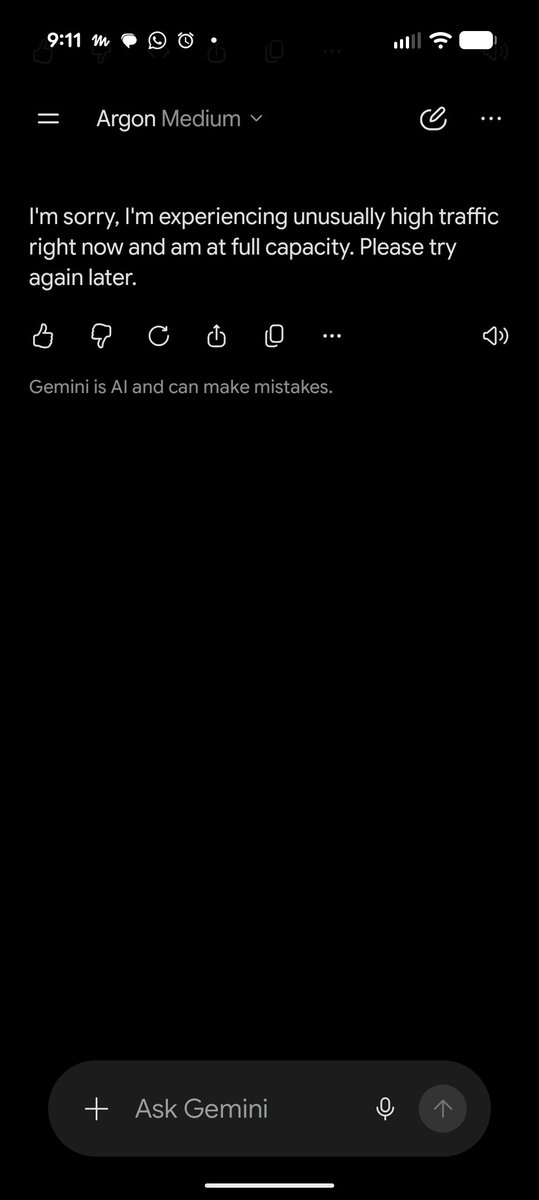
Good and bad for Gemini 4 Argon, I suppose...
> "I'm sorry, I'm experiencing unusually high traffic right now and am at full capacity. Please try again later."
$googl #ai
…updated status¹ of AI datacenter construction – another narrative violation² feeding populism and political opportunism into midterm elections:
😮 300 localities have enacted datacenter moratoriums³
🤏 3 datacenter projects⁴ actually affected by em
🤣 80% of jurisdictions with moratoriums don't even have DC project plans/capacity
📑 conditions for actually delaying a project are rare – at the crossection of…
1️⃣ DIRECT TERRITORIAL JURISDICTION:
county-level moratoriums almost universally govern only unincorporated territory, meaning any project annexed into or situated inside an incorporated municipality within that county is exempt
2️⃣ ACTIVE ENFORCEMENT STATUS:
Must be en force, not merely proposed, pending, or expired
3️⃣ STRICT TIMELINE OVERLAP (THE "GOLDILOCKS" PHASE):
The moratorium duration must intersect the exact phase when permitting/approvals are needed
4️⃣ NO ENGINEERING/CONFIGURATION WORKAROUNDS:
A lotta designs can be engineered around bans⁵ by reducing capacity below the regulated cutoff, reconfiguring the layout, or switching from a grid-interconnection design to behind-the-meter (BTM) on-site power
♾️
__
¹https://t.co/tkhIU8dN1Y
²https://t.co/bLLR9sHwCb
³across 17 states, led by 45 in MI and 40 in OH
⁴in terms of enacted legislative moratoriums materially disrupting fully capitalized, shovel-ready gigawatts – only 3 projects >20GW, including an AWS project in OH; North Point in PA; and a CoreSite expansion in CO
⁵e.g. Elon xAI $spcx deannexation of their own town
…putting a bookend on this "datacenter construction delays" narrative (https://t.co/1rRas4rWXP) for now – a cohort analysis by year:
DATACENTER CONSTRUCTION PROGRESS BY PROJECT AGE¹
📈 TREND:
28 months to 100% completion
▶️ 2026:
19 GW total starts
ahead of schedule
◀️ 2025:
37 GW total starts
tracking the estimated pace
__
¹https://t.co/mUaoxxsnYt