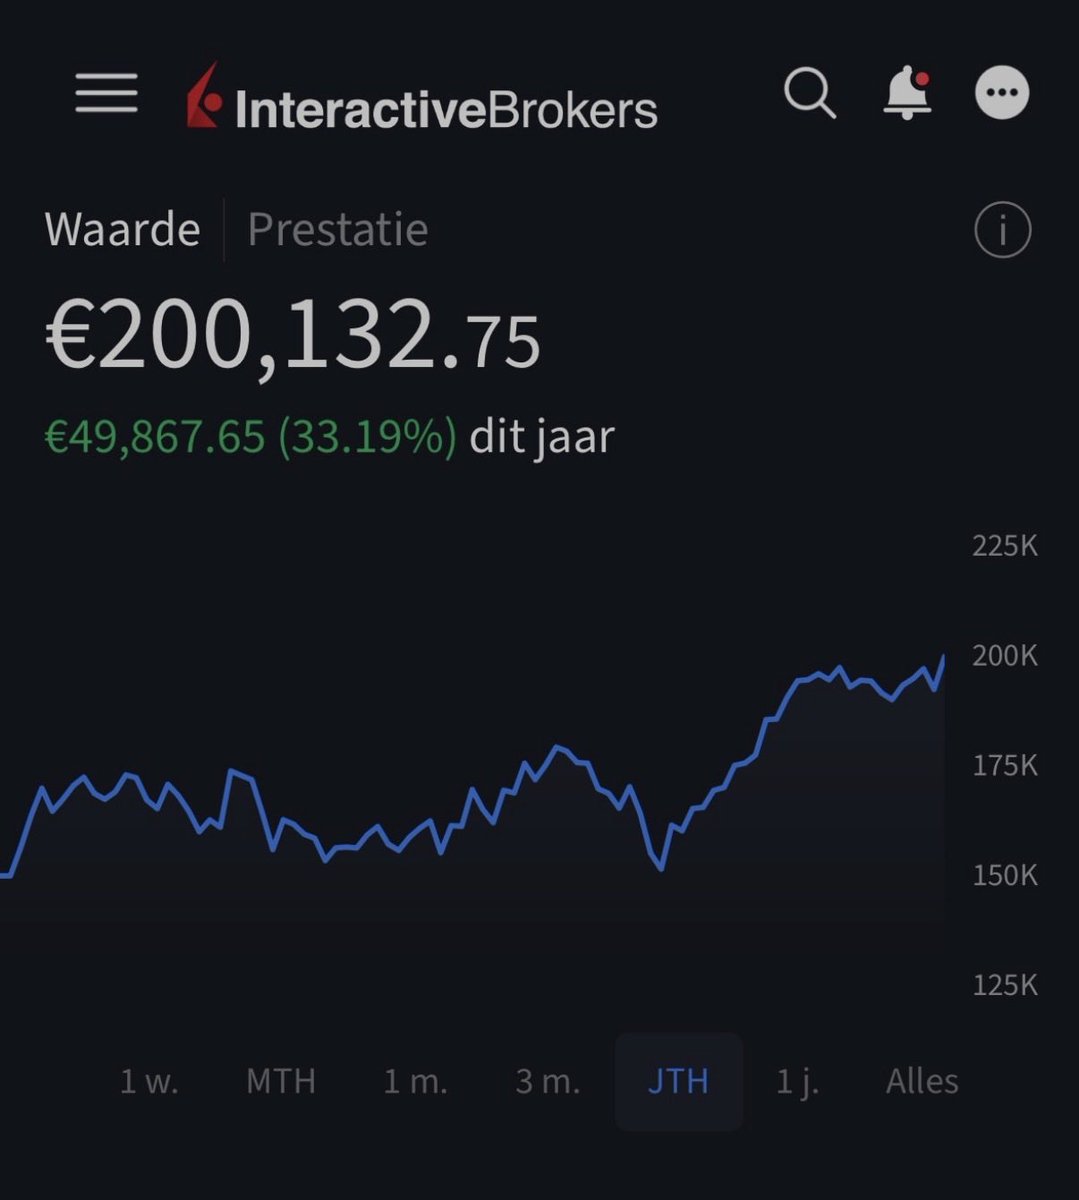
Earlier this year, my portfolio crossed €200,000.
I'm just a 21-year-old Econometrics student.
Reaching that number at this age felt surreal. It's an amount of money I never imagined I'd be managing this early in my life.
Since then, the portfolio has grown considerably beyond €200,000.
I'm incredibly proud of it. And above all, grateful.
But there's another side to it that I don't talk about as much.
Investing has become somewhat of an obsession.
🧵 1/4
IF something material is happening behind the scenes, it could potentially explain the unusually long period of silence from $ASTS management lately.
Again, pure speculation.But the timing of everything is certainly interesting.
Something interesting is happening with $ASTS.
What happened yesterday:
• AST disclosed adoption of a new Change of Control Severance Policy for senior executives.
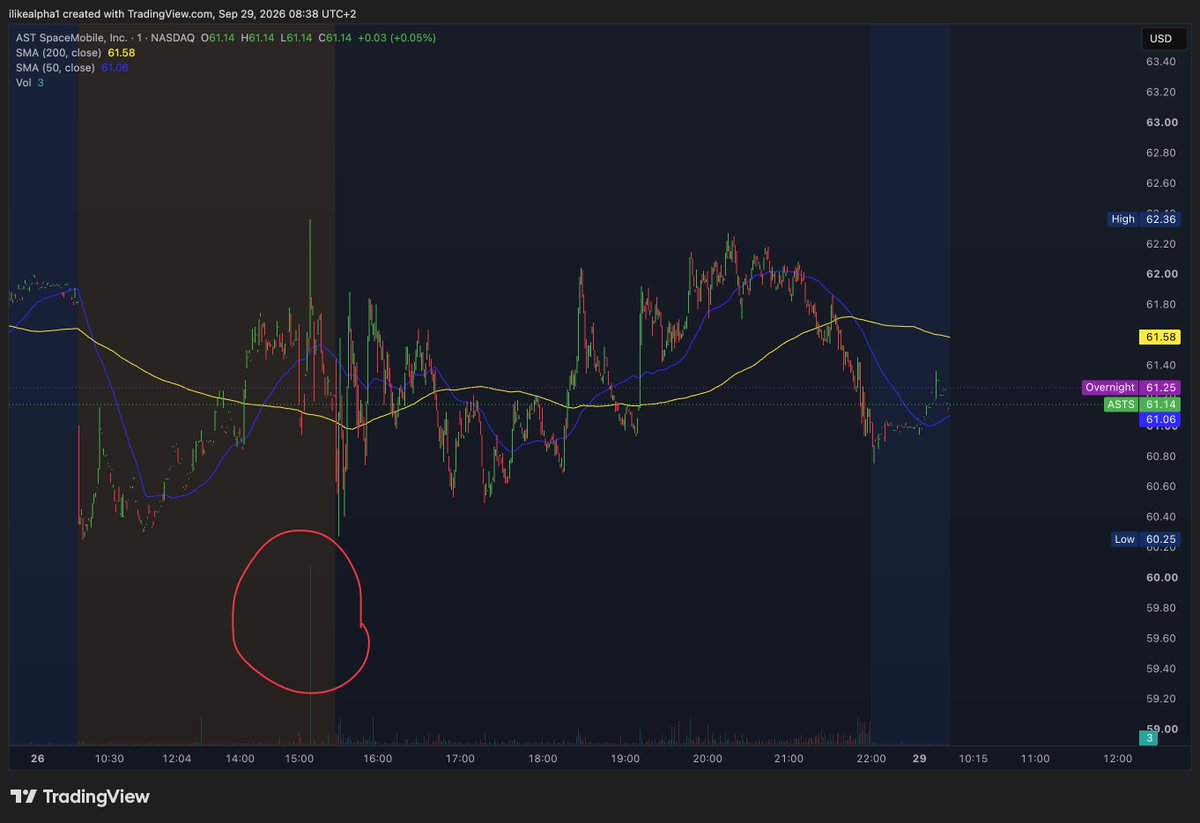
• Yesterday's premarket saw an absolutely ENORMOUS 1-minute volume spike, far beyond what we normally see (even during market hours)
• Bullish call flow has also been unusually strong lately.
None of these individually mean much.
But all three happening around the same time?
Coincidence, a volume glitch, or does someone know something?
$ASTS
$ASTS: Today’s 8K disclosed the adoption of a Change of Control Severance Policy for senior execs with double triggers. As a former M&A banker, this is very interesting timing and has potential implications of what might be going on in the background. I’ll try to do a space later to discuss.
Abel is not a seller, but the strategic importance and value of AST SpaceMobile grows by the day to many parties.
If you’re short, don’t be so dumb to find out.
The US10Y gained approximately +33% since Trump started the war against Iran on February 28th.
It is up +10% in September alone.
You would think it is only a matter of time now for the next TACO.
Midterms also coming up shortly.
Curious to see what Trump will do.
$APP is getting A LOT of attention on X right now.
Rightfully so.
I still believe AppLovin remains severely undervalued relative to the growth and cash generation of the underlying business.
And the recent acceleration in AXON Pixel installs (+11.7% week over week) makes the e-commerce opportunity increasingly difficult to ignore.
Adoption is moving in the right direction, and the potential for AXON beyond gaming is becoming increasingly visible.
Now we need to see that adoption translate into the numbers.
Holding a large position here.
$APP
Q4 2024 → Q2 2026:
Revenue: $1.37B → $1.92B
Revenue growth: +44% → +53%
Adjusted EBITDA: $848M → $1.61B
Adjusted EBITDA margin: 62% → 84%
Net income: $599M → $1.27B
Free cash flow: $695M → $863M
Shares outstanding: ~340M → ~335M
Note that Q2 FCF was temporarily suppressed by cash tax and interest timing. For reference, Q1’26 FCF was $1.29B
Reverse DCF suggests $APP is priced for ~15% CAGR.
Meanwhile, reported numbers and management forecasts are much higher.
And the opportunity has expanded considerably.
In late 2024, AppLovin's opportunity outside mobile gaming was still largely a thesis.
Current data shows AXON is increasingly proving that its advertising technology can extend beyond gaming into the much larger consumer/e-commerce advertising market.
The business is bigger, more profitable, more cash generative and has a substantially higher margin profile.
Yet the stock is back around December 2024 levels.
The risks should not be dismissed, but at current levels they already seem mostly priced in.
🧵 2/3
Curious how the market responds today to peace talks seemingly stalling again.
Also $ASTS just had a very large volume spike in the premarket. News coming up shortly?
X is the only social media platform where you can have €250,000 at 21 and somehow still feel behind.
The density of young, incredibly successful people on here is insane.
But I think that’s also one of X’s greatest sources of alpha.
Some of the stocks that have become my biggest winners are companies I first discovered right here on X, like $NBIS $HOOD $PLTR
I’d much rather surround myself with people who make me feel uncomfortable and behind than people who make me feel like I’m already ahead.
It’s a privilege to be surrounded by people who are doing better than you.
Study them.
Learn from them.
Let them challenge your perception of what’s possible.
Feeling behind can either make you insecure or make you better.
Choosing the latter will take you much further
Earlier this year, my portfolio crossed €200,000.
I'm just a 21-year-old Econometrics student.
Reaching that number at this age felt surreal. It's an amount of money I never imagined I'd be managing this early in my life.
Since then, the portfolio has grown considerably beyond €200,000.
I'm incredibly proud of it. And above all, grateful.
But there's another side to it that I don't talk about as much.
Investing has become somewhat of an obsession.
🧵 1/4
@moninvestor The earlier you make mistakes as an investor, the better
I’m glad I made all those mistakes when I had significantly less capital
Doubling from 100k to 200k in a month is crazy work tho 😮
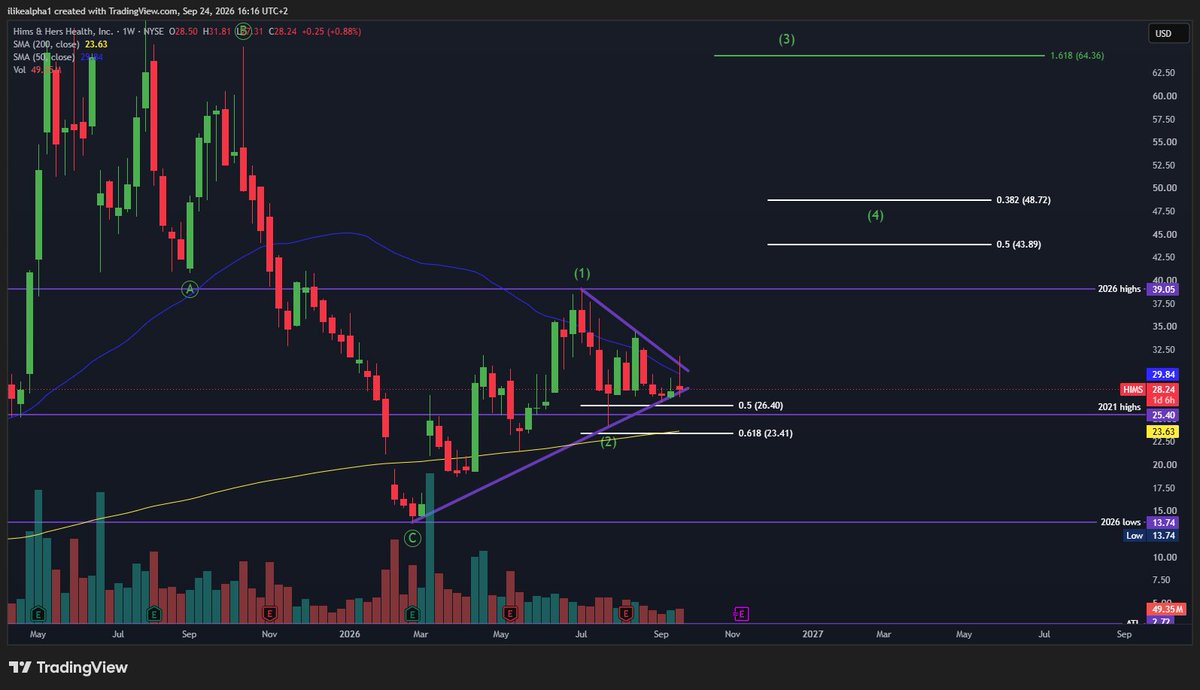
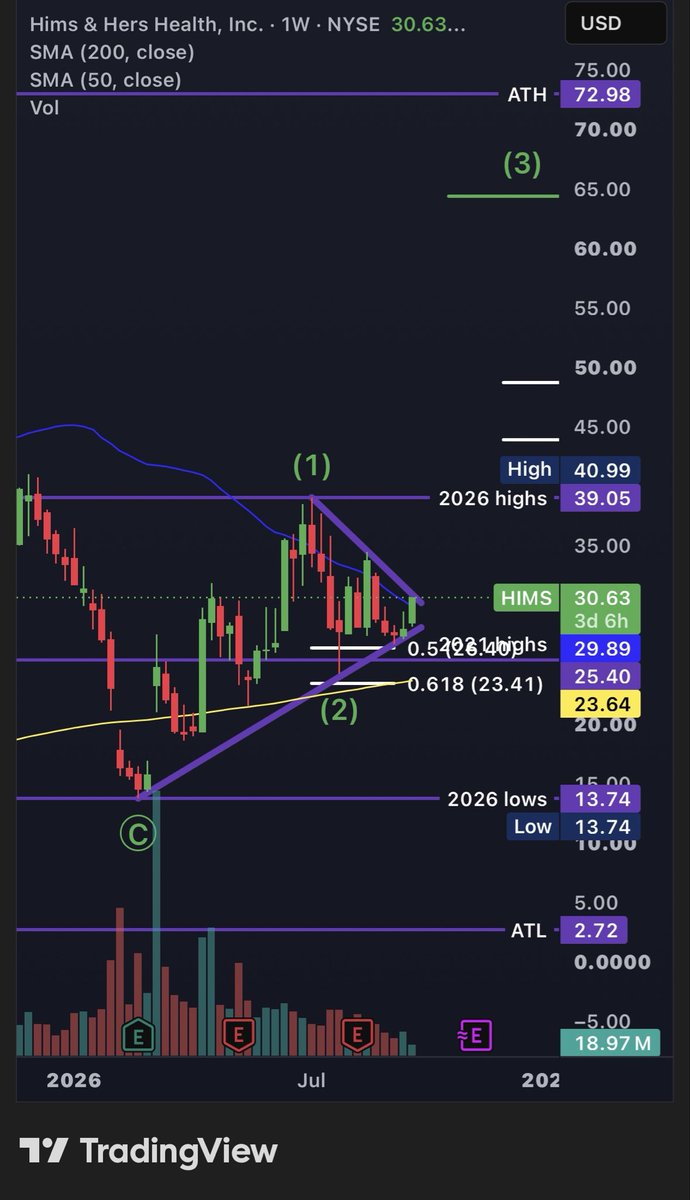
Nasty weekly candle by $HIMS as it continues to consolidate within the wedge.
Meanwhile, the underlying business continues to improve.
Today, Hims showcased its next evolution of the app, with AI increasingly embedded throughout the care journey rather than simply functioning as another chatbot.
Combine that with:
- A rapidly growing proprietary healthcare dataset
- Increasing personalization
- U.S. growth reaccelerating
- International expansion
- Peptide expansion
It's becoming a personalized healthcare ecosystem with AI and proprietary data at its core.
All while $HIMS still trades at roughly 1.1x management's 2030 Revenue target.
Disconnects create opportunity.
Are you adding $HIMS here? 👀
Quite the statistic:
The U.S. 10Y is posting its largest daily jump since April 7, 2025.
The date that marked the absolute bottom for $QQQ during the 2025 selloff.
From that low, $QQQ went on to rally roughly 58% in just 142 trading days.
Obviously, a spike in yields isn't inherently bullish, and today's macro backdrop is very different.
Today, the 10Y has pushed above 5%, as stronger-than-expected economic data, renewed inflation concerns and expectations for further Fed tightening hit bonds and equities.
But this is an interesting coincidence.
$QQQ $SPY $NVDA
Reminder that $HIMS:
- Grew Q2 revenue 38% YoY
- Has nearly 2.9M subscribers, +19% YoY
- Saw U.S. revenue reaccelerate to +16% YoY
- Increased revenue per subscriber 21% YoY
- Is rapidly building out its international footprint
- Raised FY2026 guidance
- Targets $6.5B+ revenue and $1.3B+ Adj. EBITDA by 2030
Yet the market is still valuing the company at roughly 1.1x management's 2030 revenue target.
Successful peptide expansion and sustained organic growth could lead to a significant re-rating.
One of my favorite risk/reward setups in the market right now.
Friendly reminder that $HIMS is still trading at roughly 1x management's 2030 revenue target.
Meanwhile, domestic growth is reaccelerating, while international expansion is adding another significant growth engine.
On the chart, we're seeing some nice and healthy consolidation within the wedge, just underneath the 50WMA.
Plenty of catalysts ahead:
Continued U.S. growth.
International expansion.
New categories (peptides).
Increasing personalization.
Improving operating leverage over time.
But management now has to show that the recent reacceleration in the U.S. can translate into sustained organic growth.
If they can prove that while successfully scaling the international business, I think confidence in the long-term growth trajectory can return quickly.
At roughly 1x management's 2030 revenue target, there is plenty of room for a rerating if execution follows.
Fundamentals first. Multiple expansion can follow.
$APP
Q4 2024 → Q2 2026:
Revenue: $1.37B → $1.92B
Revenue growth: +44% → +53%
Adjusted EBITDA: $848M → $1.61B
Adjusted EBITDA margin: 62% → 84%
Net income: $599M → $1.27B
Free cash flow: $695M → $863M
Shares outstanding: ~340M → ~335M
Note that Q2 FCF was temporarily suppressed by cash tax and interest timing. For reference, Q1’26 FCF was $1.29B
Reverse DCF suggests $APP is priced for ~15% CAGR.
Meanwhile, reported numbers and management forecasts are much higher.
And the opportunity has expanded considerably.
In late 2024, AppLovin's opportunity outside mobile gaming was still largely a thesis.
Current data shows AXON is increasingly proving that its advertising technology can extend beyond gaming into the much larger consumer/e-commerce advertising market.
The business is bigger, more profitable, more cash generative and has a substantially higher margin profile.
Yet the stock is back around December 2024 levels.
The risks should not be dismissed, but at current levels they already seem mostly priced in.
🧵 2/3
Friendly reminder that $HIMS is still trading at roughly 1x management's 2030 revenue target.
Meanwhile, domestic growth is reaccelerating, while international expansion is adding another significant growth engine.
On the chart, we're seeing some nice and healthy consolidation within the wedge, just underneath the 50WMA.
Plenty of catalysts ahead:
Continued U.S. growth.
International expansion.
New categories (peptides).
Increasing personalization.
Improving operating leverage over time.
But management now has to show that the recent reacceleration in the U.S. can translate into sustained organic growth.
If they can prove that while successfully scaling the international business, I think confidence in the long-term growth trajectory can return quickly.
At roughly 1x management's 2030 revenue target, there is plenty of room for a rerating if execution follows.
Fundamentals first. Multiple expansion can follow.