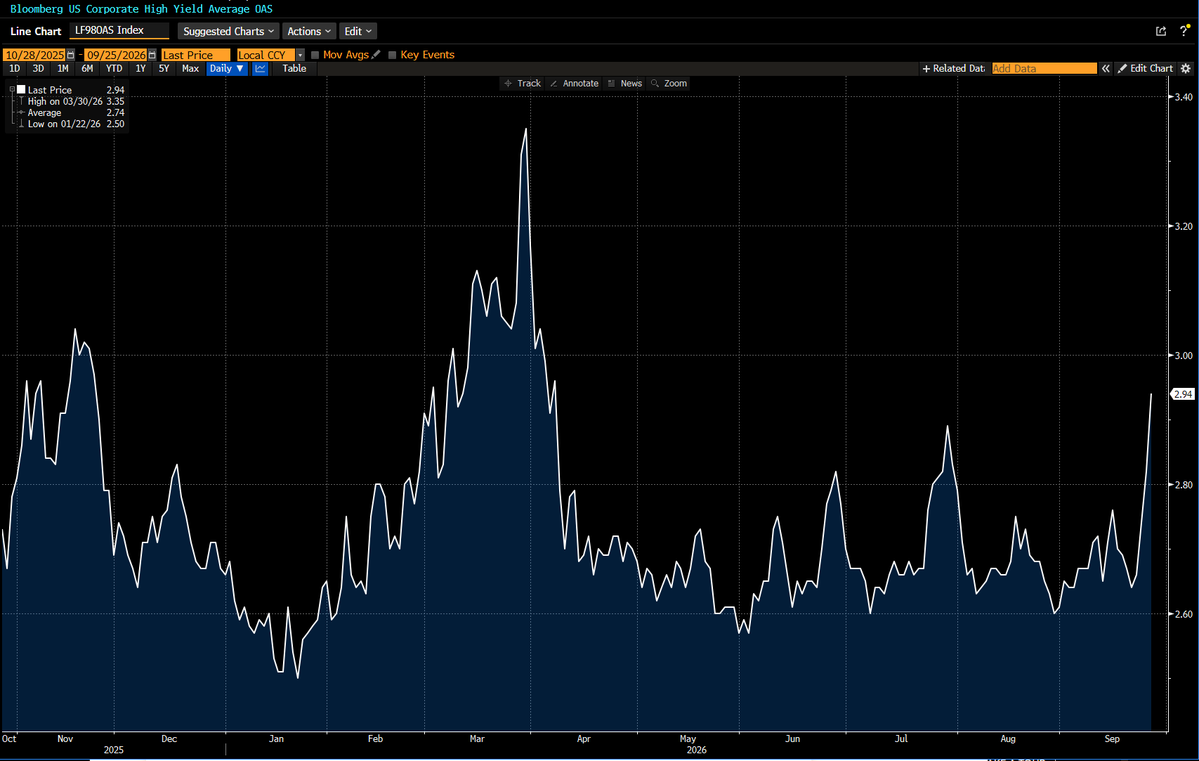
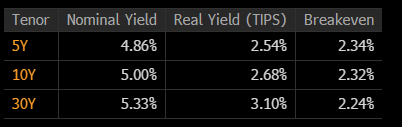
Surging benchmark rates are starting to bite corporate credit more significantly. Spreads on high-yield bonds have widened 28bp in the past three days, the most since October 2025. While spreads are still relatively low, they've been widening at an accelerating clip.
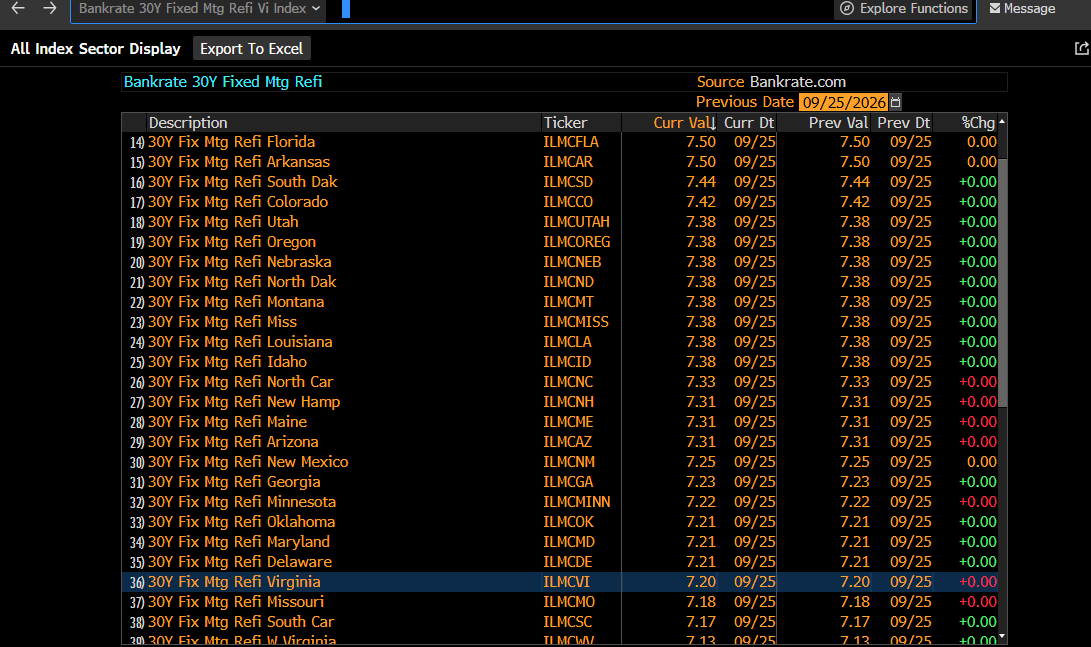
Mortgage rates have historically led to number of SP500 companies with negative earnings growth by about 2 years. With 30 year refinancing mortgage rates hitting above 7.20% on Friday. That’s something to keep an eye on.
The presumption that the Fed raising short-term rates reduces inflation is predicated on the belief that higher rates reduce demand and investment.
But what if higher rates don’t reduce demand and investment because the demand for intelligence and energy is unaffected by higher rates because winning the race for super intelligence has a near infinite ROI and the demand for compute will remain incalculable.
Why won’t higher rates at this unique moment in history therefore lead to more inflation as interest costs are embedded in everything?
And the problem is compounded as the more the Fed raises rates, the more inflation we will have and the more the Fed will need to raise rates further and so on.
But what if the old models don’t apply to the current paradigm and the Fed is wrong?
I think the Fed might have just made a mistake. Am I right or am I wrong?
The move we're seeing at the long-end isn't an inflation expectation story, but rather real-yield story, which can be reflective of growth expectations (hyperscalers' CAPEX) or fiscal and fed credibility - would give the latter more weight.
Some of the highest quality businesses in the world are trading at extremely cheap prices. Ignore the MSM. One of the most one-sided wars in history that will end well for the U.S. and the world. And we have the potential for a large peace dividend.
One of the best times in a long time to buy quality.
Ignore the bears.
Something is happening in bond markets. Yields on 10-year Treasuries have fallen to the lowest this year, while credit spreads are widening to the highest this year.
"The empire long divided must unite, the long united must divide; thus it has ever been." - Romance of Three Kingdoms.
This is one of the famous openings in Chinese literature. Under Xi, the markets should expect a more consolidated China.
“In the markets and life, to be successful one should bet on the upside that comes from a) evolution that leads to productivity improvements, but no so aggressively that b) cycles and bumps along the way knock you out of the game.” True testimony to the correction in the AI trade
On the other side, you're competing against GS, JPM, Citadel, Two Sigma, where they have PhDs in math, physics, CS, have Bloomberg terminals everywhere, massive data set with tremendous technology, and low-latency execution. If you're trying in day trade, well it's very unlikely.
Secretary of State Marco Rubio delivered another fantastic speech in Europe with this haymaker of a line: "We in America have no interest in being polite and orderly caretakers of the West’s managed decline." Bravo, Mr. Secretary, Bravo...