Pre-Market Thoughts - 6 Oct 26
AI money is getting bigger and still flowing to the top of the stack. Banks are syndicating a $60bn Broadcom-guaranteed loan to fund Anthropic's lease of Google chips (per the FT), Lisa Su says AMD will "substantially" increase supply in 2027 (per Reuters), and Google is reported to be near a $1bn-plus nuclear deal with Constellation (per Bloomberg). $CEG is up about 3% pre-market, Nvidia about 0.7% after Monday's record close and $AVGO about 0.4%.
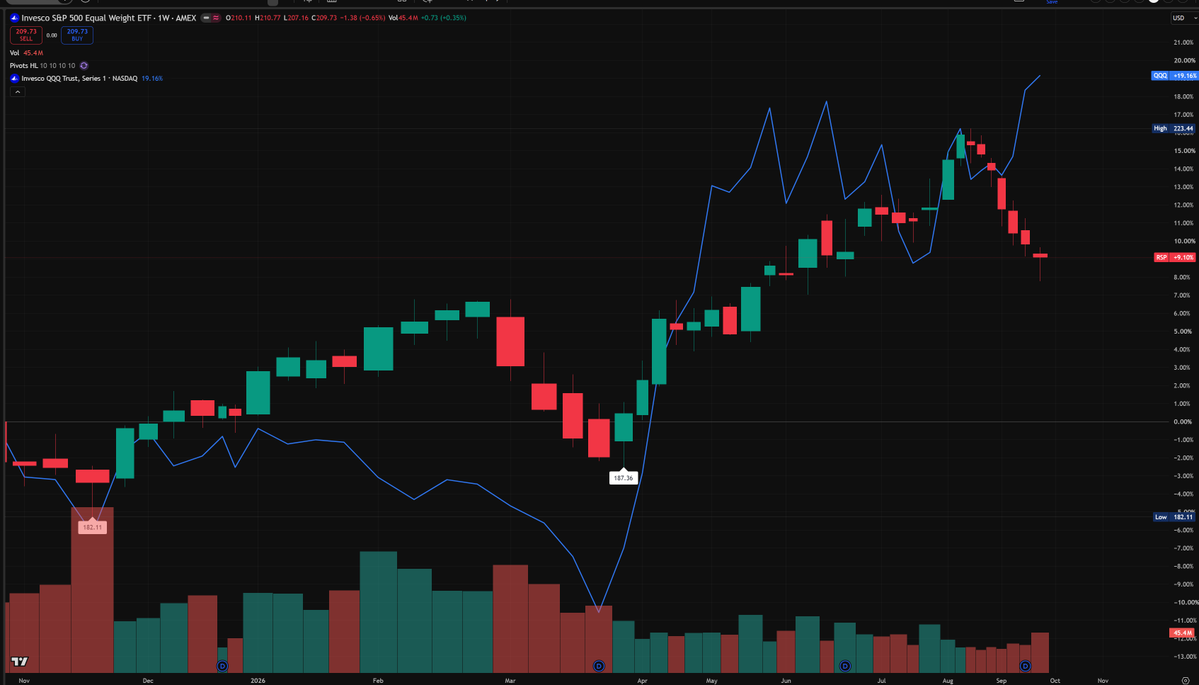
My read: the market pays whoever controls the scarce input (chips, equipment, power) and makes the more leveraged parts of the chain prove themselves. On Monday the neocloud group fell about 2% while Nvidia and Broadcom rose about 2%, and Asian memory makers sold off overnight ahead of Samsung's results on Thursday. Today's test for optics and custom silicon is the $MRVL investor day; optics gapped up and sold off on Monday, so the bar is high.
The constraint is still rates. The 10-year closed Monday at 5.31%, near its 52-week high, and Japan's 30-year yield hit a record overnight. Nasdaq futures are up about 0.3%. Williams speaks at 14:05 UK / 09:05 ET and Bowman at 15:45 UK / 10:45 ET; FOMC minutes are Wednesday at 19:00 UK / 14:00 ET, then $APLD reports after the close, the first hard read on neocloud demand. What changes my view: yields breaking higher after the Fed speakers, or a strong APLD print that pulls the laggards back in.
Not investment advice. I may hold positions in names mentioned.
Serious question, given the news today from @the_tpa, is the United Kingdom even salvageable at this point?
Trying not to be pessimistic but it feels like places like the UK and France are basically at a point of no return now
@afcjd_@realhansard Oh so thats per year right? Because someone on 37K isnt paying 4700 in tax every month, ppl on less then 50K hardly pay any tax in this country
Pre-Market Thoughts - 5 Oct 26
Asia ran Friday's AI rally again overnight, but the US has not followed. Taiwan's TAIEX closed at a record and Japan's chip names rallied, yet S&P and Nasdaq futures are indicated about 0.1% lower and $SMH is flat pre-market. The new fact Asia could not trade is Foxconn's Q3 revenue, up 47% y/y on AI servers (per Reuters), which landed after Taiwan's close. My read: it is the cleanest data point of the morning, and it points to the server and rack-assembly chain, where $DELL is flat pre-market, more than to further chip multiple expansion.
Storage is the second thing to watch. $WDC and $STX each fell about 10% on Friday after Toshiba said it plans to nearly double HDD capacity; this morning they are indicated up 1.6% and 1.9% after several brokers argued supply stays tight. Toshiba gaining share is real, but demand running ahead of supply matters more. If the bounce holds through the open, Friday was positioning, not a turn in the cycle.
The gate for all of it is rates. The 10Y closed Friday at 5.28%, near its highest since 2002 (per the FT), and VIX is up 6% at 16.2. ISM services at 15:00 UK / 10:00 ET is the event: a hot prices-paid reading lifts yields and hits the highest-beta AI names first. Tomorrow, $MRVL's investor day is the next read on custom silicon and optics.
Not investment advice. I may hold positions in names mentioned.