Independent Macro Investor- ex. Macro Hedge Fund Mgmt / SG PT & Strat / SAC capital / IMF + Blogger on Macrottt /// It's all about asking the right question.
Accumulated big short USD/CAD ov lst 2wks. D day tom - BOC speech.
Draghi spch with "temp" infla drop supports BOC's view.
Oil rbnd helps. https://t.co/8gzU1sqmiq
#Fed embedded assumptions and #AI
...Productivity visible "ANECDOTALLY"
ok where?... aren't we all individually more productive with AI?
Still unconvinced abt net MT aggregated impact - layoffs vs increased production...
https://t.co/wEUZYZzUra
5/5
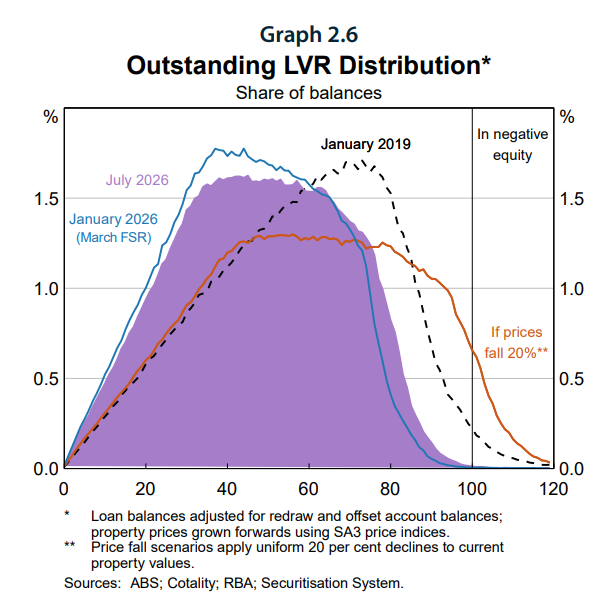
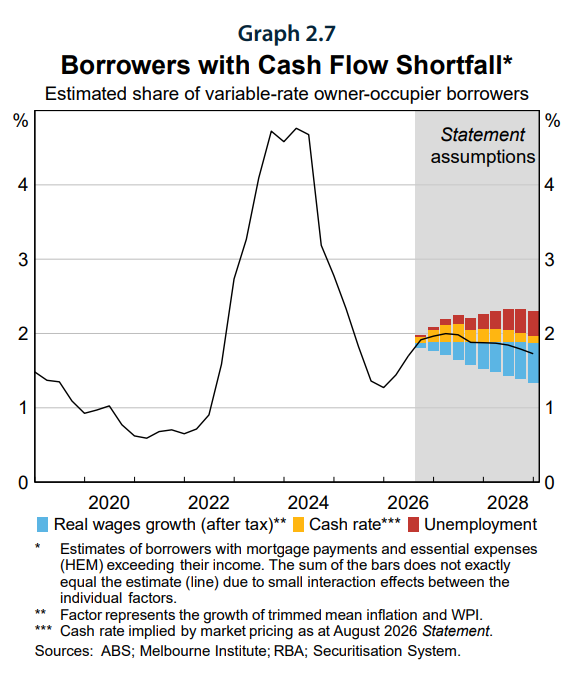
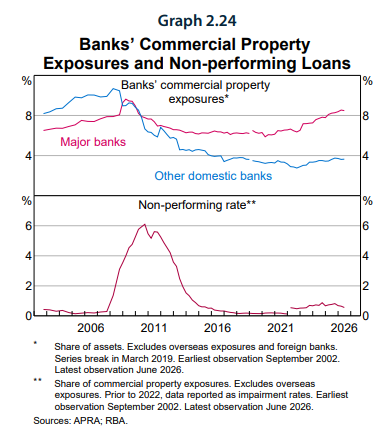
RBA is ready for impact!
But particularly interesting in their FSR is the discussion of SCENARIO ANALYSIS (4.2) for risks that have never happened before.
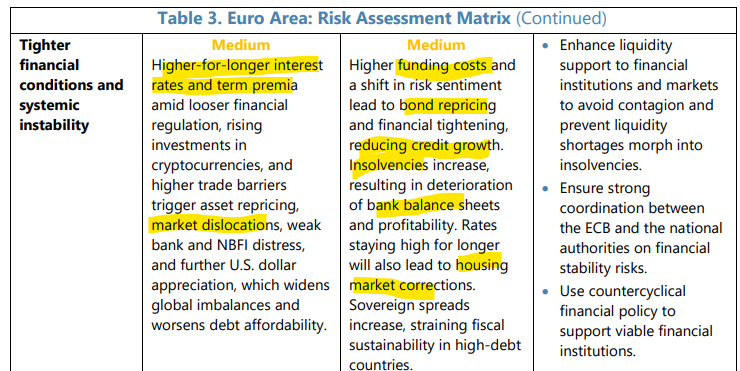
Takeaway is that in this regime all investors and risk managers should prepare for unforeseen shocks and policy shifts.
4/5
So CBs are getting ready for eventual shock… stress testing bks, checking Systemic Risks, searching weak contagion links.
RBA FSR last wk had very interesting scenarios and granular analysis … -20% correction coupled with eventual unemployment rise.
https://t.co/fojtXgh6SY
3/5
Real estate markets are an obvious candidate for adjustment.
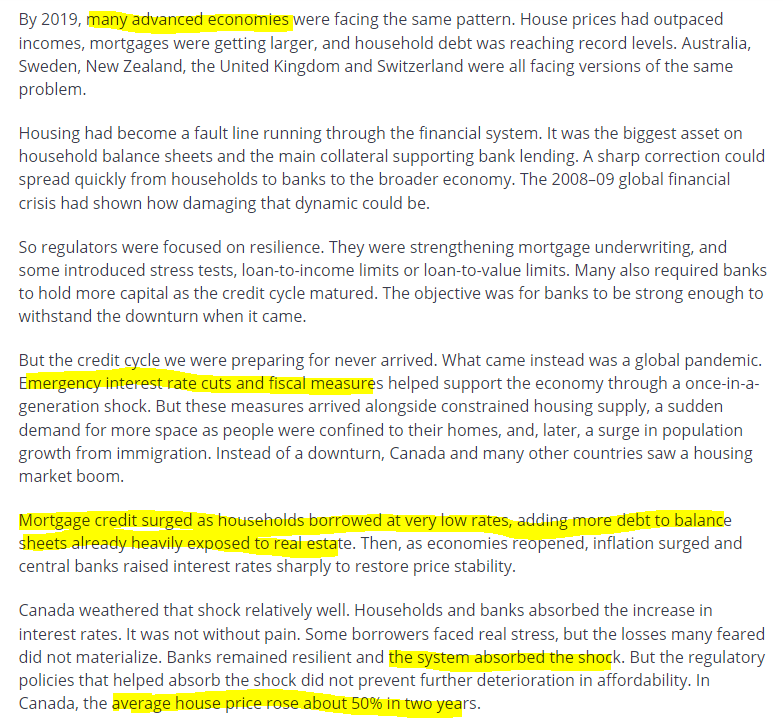
#BOC last week explained how all CBs expected stress before covid, just before seeing a new 50% 2y rise in house prices!
https://t.co/oWtalyDSzF
2/5
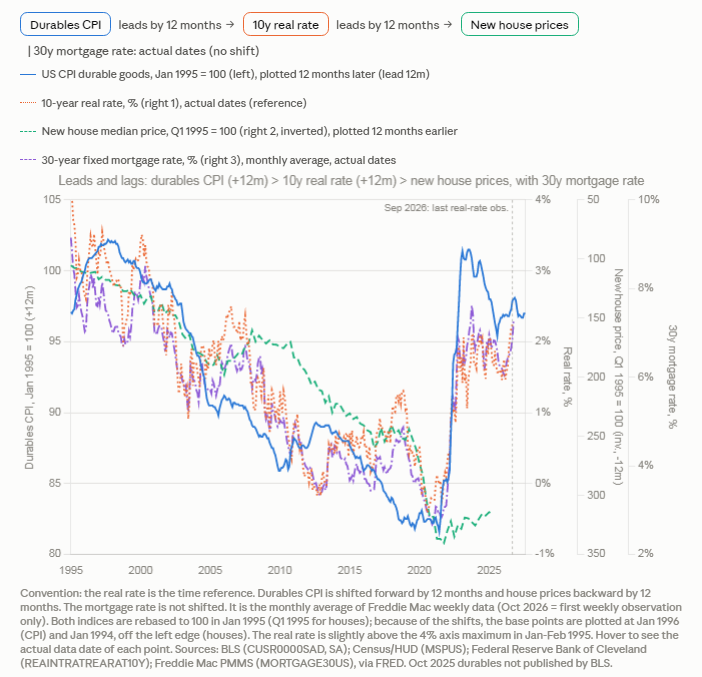
… Decline in durable goods #CPI was striking. Adding LT rates, #house prices, with 12m leads/lags and hand-picked axes [no causality claimed or tested here!!!].
But post-2022 divergence of rates and real estate stands out. Clearly illustrative of the new regime.
1/5
Coming back to the “New #macro regime” discussion [blw], the first obvious impact is fiscal repricing and differentiation, but again many other price / equilibrium will be tested.
While trying to visualize the “global disinflation” era in the US…
https://t.co/DnyFm0IsUL
4/x
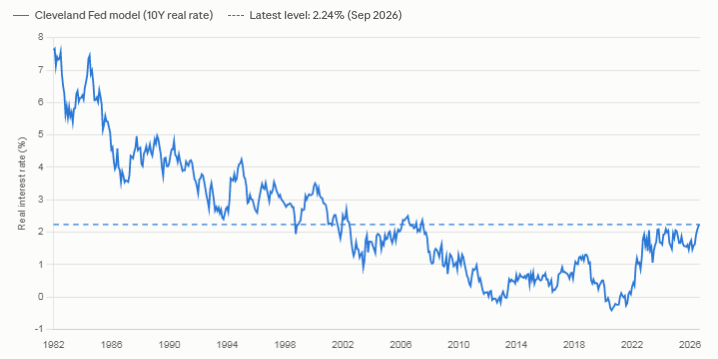
So yes we are in a new macro regime, with the most significant reflection being the level of rates, and hence with major csq starting to appear gradually… obviously fiscal, but also in financial terms - because US LT rates are the reference risk free prices for valuation.
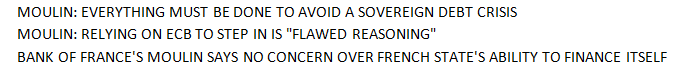
🇪🇺 🇫🇷 *BANK OF FRANCE CHIEF MOULIN SPEAKS ON FRANCE INTER RADIO - BBG
*MOULIN: SITUATION ON BOND MARKETS IS 'COMPLICATED'
*MOULIN: FRENCH SPREAD DUE TO DEFICIT, POLITICAL UNCERTAINTY
*MOULIN: ESSENTIAL TO REDUCE DEFICIT, STABILIZE DEBT TRAJECTORY
*MOULIN: 2027 FRANCE BUDGET IS VERY IMPORTANT TO REASSURE MARKET
*MOULIN: FRANCE IN 'ZONE OF RISK' ON BUDGET DEFICIT
*MOULIN: VITAL FOR FRANCE TO HAVE BUDGET BY YEAR END
*MOULIN: ECB DOESN'T HAVE SOLUTION FOR FRANCE
*MOULIN: CONDITIONS NOT MET FOR ECB INTERVENTION ON FRANCE
7/x
Eventually they could “tweak” the criterias … (but at a credibility cost) because stating that France’s debt problems are not due to fundamentals is hard to swallow. It is just that QE was supposed to provide time for reforms [as Draghi asked a million times] but was waisted
6/x
Of course, eventually there is the #TPI - but the #ECB certainly will prefer keeping it as a very last resort (given BOE/Liz Truss and Bessent failed attempts at capping LT yields) and would wait signs of “contagion”.
https://t.co/UCwZsvmmJ3
5/x
What is new – the causes - are contextual:
- rates level (global factor) = refinancing level suddenly very expensive,
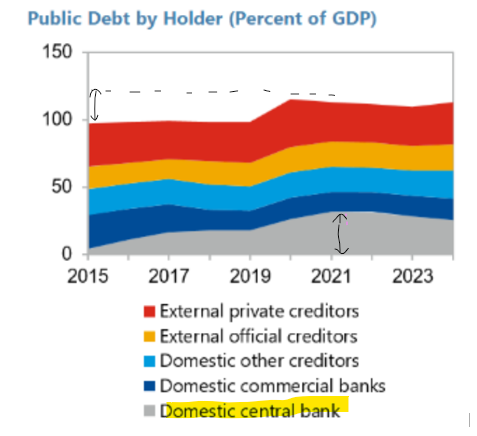
- inflation context = impossibility for ECB to use QE to buy EGB (“impossible trinity” apply to bond purchases). See OAT ECB purchases btw 15 & 21 (art 4)
4/x
It is abv all a pbm of public opinion & structural (but rational) unwillingness to accept welfare state reforms… [that’s why Milton Friedman explained that “a crisis” was a pre-condition for reforms]. Think “sick man of Europe”, Hartz IV reforms & Schröder losing reelection
3/x
On causality – confusion symptoms vs causes
I saw cmts on #Spread widening on “cancelling the debt debate” & “polarization”.
These are triggers- the fact that a political party can propose “cancelling the debt” and not lose all credibility shows depth of economic ignorance.
2/x
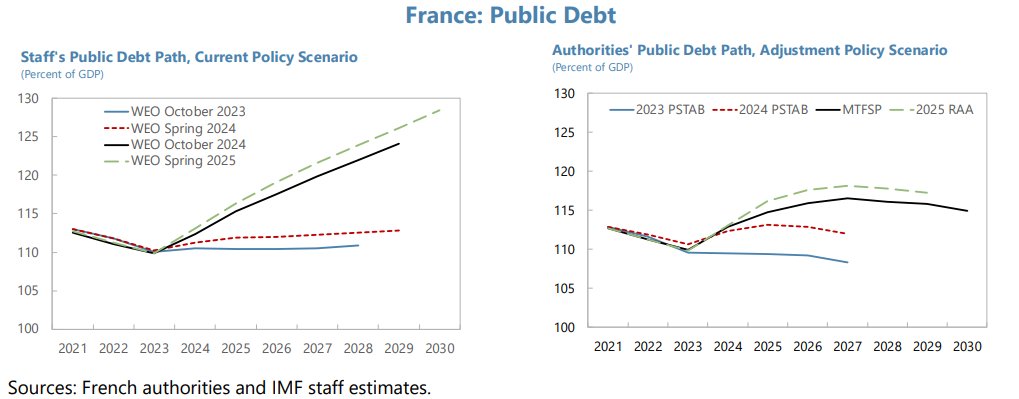
I would be surprised if French budget project proves enough to stabilize things durably… Far too late now that market participants are focusing on the unbalances… especially in the context of current social chaos in France.
https://t.co/PR02H5FMG3
Update #EMU#France 1/x
#EURUSD a good “crisis” gauge - out of its 16m range and not #GBPUSD for instance = confirms the nascent awareness of a risk of European Crisis[3.0?].
More significant levels would be 1,1150 / 12 consistent with much more serious “contagion” scenario.
#EMU & #China_shock_2.0 & Industrial Policies
Watching the damage unfold while waiting for an overdue reaction.
Pathetic lack of policy (and political) leadership by European Leaders. Quite sad...
https://t.co/zMtvTJgK8k
Big decisions being taken?
NY UN's Trump ME meeting, then Netanyahu in UAE ; then this meeting in Riyadh...
+ Middle East exports 94% normalised...
I don't do coincidences.
#Oil, #dollar
https://t.co/nPpbOeyv5J
AI #Productivity debate...
also measurement issues, likely underestimated - discussed in IMF Working Paper.
To add to the Fed's dilemma.
https://t.co/XK8m0zuzUF]
U.S. TREASURY SECRETARY BESSENT URGED THE FED TO KEEP AN “OPEN MIND” ON INTEREST RATES, ARGUING THAT AI-DRIVEN PRODUCTIVITY GAINS AND DEREGULATION COULD HELP KEEP U.S. INFLATION UNDER CONTROL, WHILE SAYING CORE INFLATION HAS REMAINED RELATIVELY SUBDUED IN RECENT MONTHS.