Don't Predict, Respond. We've said this so often at @CapitalmindMF so as we enter our second year, we speak with @SurabhiUpadhyay about what this actually means.
@Calminvestor and I on our evidence driven approach, and our investing road map: https://t.co/yLJ7Gq5AHQ
I know this one was in jest but still paying 60K in interest is slightly painful :)
Better still, sell the gold, buy the iphone. And invest 10000 rs. Per month in an fd (so you don't accuse me of selling our mutual finds) which in 24 months will give you 2.5 lakh, just about enough to buy... iPhone 19 then :)
He sold an appreciating asset to buy a depreciating one. Instead, he could have taken a gold loan, paid just ₹2,500/month approx in interest and invested ₹7,500/month in a recurring deposit. After 24 months, the ₹1.8L loan is closed on RD maturity, the iPhone is his and he still owns the gold which could easily be worth ₹2.2–2.3L by then 🥳
From building wealth early to finding the balance between investing and spending, @deepakshenoy of @CapitalmindMF gets candid about money!
Full conversation out soon🙌🏻
In general, the UPI MDR will reach about 3% of the transactions. 96% of current transactions are anyhow out. Out of the remaining 4%, 1/4th will move to other sources.
But that will still mean some fairly large revenues for all players, let's see if it hits 10,000 cr. +
#TimeToMintMoney 💰
When experience speaks, markets listen.
What happens when decades of investing wisdom come together on one stage? You get conversations you simply cannot afford to miss.
At the 4th edition of Mint Money Festival 2026, hear from some of India’s most respected voices in investing and finance, including:
🔸 Vijay Kedia, Ace Investor
🔸 Sankaran Naren, ED & CIO, ICICI Prudential Mutual Fund
🔸 Rajeev Thakkar, Director & CIO, PPFAS Asset Management
🔸 Radhika Gupta, MD & CEO, Edelweiss Mutual Fund
🔸 Devina Mehra, Founder, Chairperson & MD, First Global
🔸 Deepak Shenoy, CEO, Capitalmind Mutual Fund
One stage. One day. An incredible lineup of money minds.
📅 28 November 2026
📍 National Stock Exchange (NSE), Mumbai
Book your pass now: https://t.co/rsC0UUuljd
🎟️ Early Bird pricing is LIVE till 30th September.
Don’t wait for the last day to make your move. If you miss it, you’ll really miss it.
#MintMoneyFestival #MintMoneyFestival2026 #PersonalFinance #Investing #WealthBuilding #MoneyMatters #Mumbai #TimeToMintMoney
@NSEIndia | @deeptibhaskaran | @jashkriplani | @apri_sharma | @sashindnj | @Shiprasorout@VijayKedia1 | @RajeevThakkar | @iRadhikaGupta | @devinamehra | @deepakshenoy@ICICIPruMF | @PPFAS | @edelweisslife1 | @firstglobalsec | @capitalmind_in
UPI MDR is changing. So, how costly will mutual fund investments be, given this update?
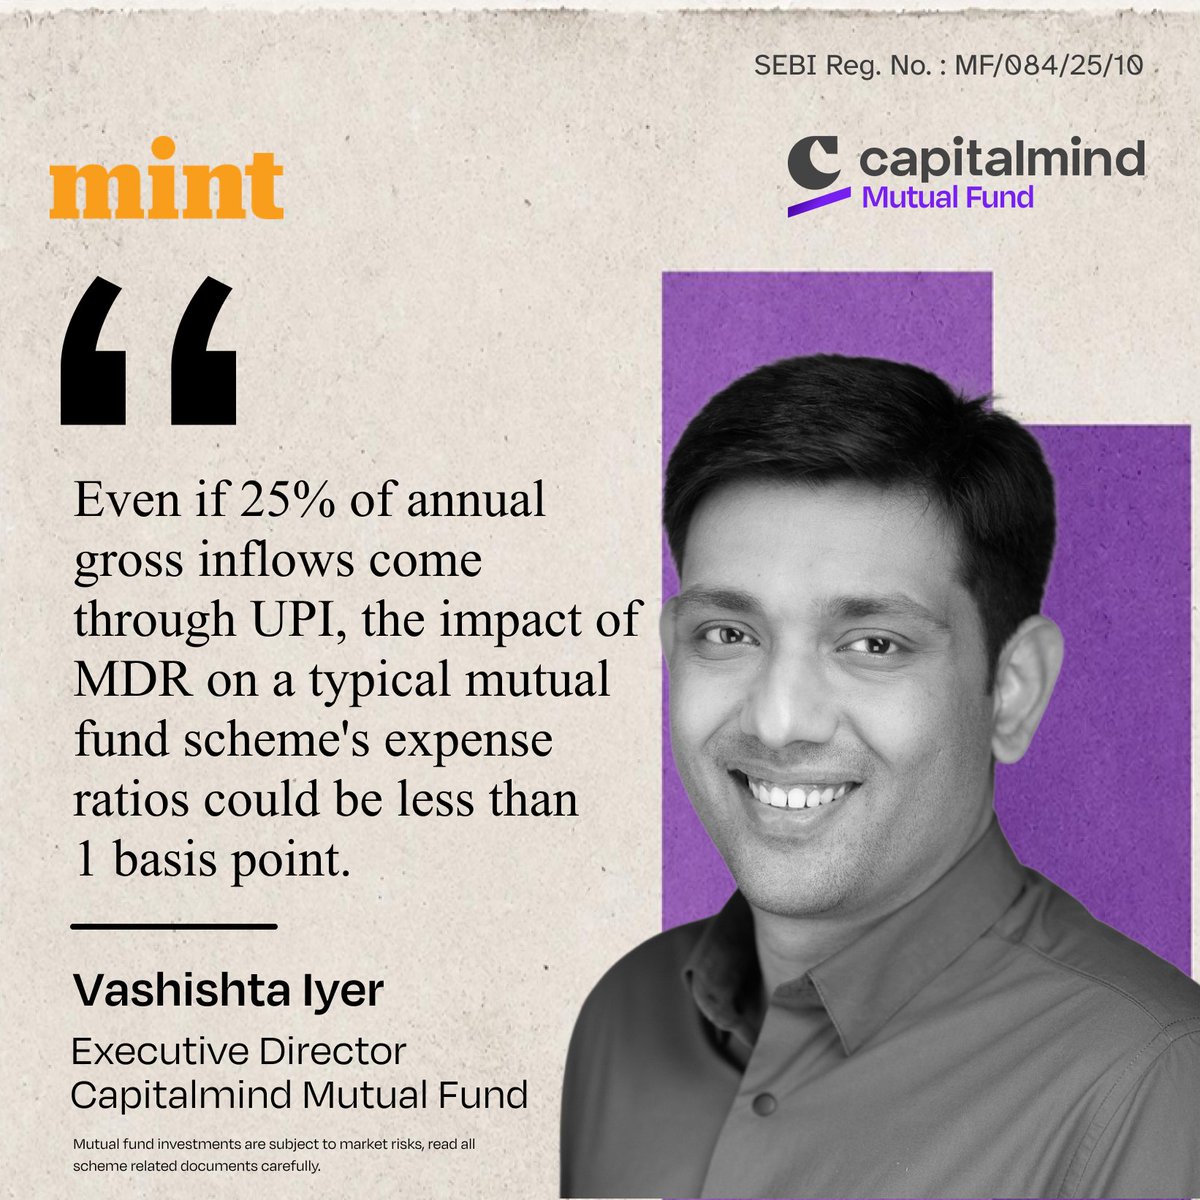
As Vashistha Iyer @uptickr, Executive Director at Capitalmind Mutual Fund explains: For a typical mutual fund scheme like a flexi-cap fund, the impact could be relatively small.
Capitalmind’s analysis estimates that even if 25% of annual gross inflows come through UPI, the impact could be around 0.15–0.20 basis points on the scheme’s expense ratio, depending on the fund and its cost structure.
Read more about this in our recent analysis, featured in Mint, linked below.
https://t.co/g1uj6bZD0b
The biggest risk in a volatile market may not be volatility itself.
It’s reacting emotionally to it.
Buy when markets rise. Exit when they fall. Repeat.
What if, instead, you had a framework designed to respond, not predict?
@deepakshenoy , MD & CEO, Capitalmind Mutual Fund (SEBI Reg. No.: MF/084/25/10), explains Capitalmind’s approach to volatility in Respond. Don’t Predict, in association with Moneycontrol.
https://t.co/obUlosAvJi
Mutual Fund investments are subject to market risks, read all scheme-related documents carefully.
#RespondDontPredict #EvidenceLedInvesting #Partnered | @CapitalmindMF
@sohamdas Petrol pumps will end up charging for filling so people will keep it under Rs. 2000 even for cars or fill more frequently. (Typical car does 4K-5K per month in petrol/diesel)
Qcom and movies - typically less than 2K so it won't matter. ECom is the only space that will continue
MDR on UPI is here - meaning, some merchants will pay money to receive payments on some UPI transactions. First, those that won't pay at all even after this:
1) You and me types, individuals paying each other. Pay like there's no tomorrow, and you won't be charged.
2) Everyone else is a "merchant". So Any payment under Rs. 2000 to a merchant for anything regardless of what anyone says. Yes, you can even pay a merchant in multiples of Rs. 1500 and no one will be charged.
3) Small merchants that make less than Rs. 100,000 in UPI payments per month (including the less than Rs. 2000 ones). They don't have to pay.
Now who will pay: (Next item in thread)
@chithrakanmani@adityajnadi Our mottois "Don't Predict, Respond" - which is why I do it once a year and make a fool of myself (and shine like a diamond once in a while)
Actually there is no choice for consumers. No provider can say I'll forego my bit and give you a better rate other than the merchant acquiring bank. The issuing banks and psp cannot even say don't pay me, and give merchants a better rate.
Only chance is if all merchant plus acquiring bank are the same so you might see a small advantage that's all.