It was Friday October 23, 1987 and the amazing Louis Rukeyser of PBSs Wall Street Week just after the market crash on black Monday October 19.
Louis was the intelligent voice of reason in chaos—so very missed.
Please watch this tonight...
@QTRResearch Doug Kass: The AI Funding Boom Has Peaked
This is why AI companies are ‘rushing’ to go public, Kass argues...
Quoth the Raven
Aug 28, 2026
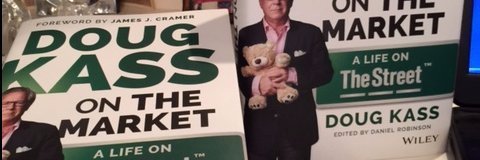
I’ve known Doug Kass for a while now. He’s a veteran investor, and someone readers of TheStreet will know well from his years of sharp, independent market commentary. He also writes a great blog, and this week I read one of his better pieces yet on the artificial intelligence boom.
I thought it would be a great supplement to my recent piece on why I think the AI crash could start as soon as this year:
In his note, Doug makes it clear that he believes the funding cycle for artificial intelligence may already have peaked. Doug thinks that one of the clearest signals is the apparent urgency with which OpenAI and Anthropic are moving toward the public markets.
After years in which AI companies enjoyed abundant private capital, rapidly rising valuations, enormous strategic investments, and relatively little quarterly financial scrutiny, the obvious question is: Why the rush to go public now?
I’ll do my best to sum up Doug’s note. His concern is that beneath the extraordinary valuations and breathtaking capital expenditures, the economics of the AI business may be becoming considerably less attractive. Token growth is slowing, token prices are falling dramatically, competition is increasing, open-source models are improving, and the amount of capital required to keep the ecosystem expanding is staggering. This chart and writeup from Zero Hedge confirms this:
Token Cost Chart via Zero Hedge - Chart
That makes the IPO race particularly important. These companies need enormous amounts of capital to sustain their current spending, but going public would also expose their economics to a level of scrutiny they have largely avoided as private companies. Once OpenAI or Anthropic is publicly traded, investors will be able to examine revenue growth, operating losses, cash burn, capital requirements, and customer economics quarter after quarter. The story will have to collide with the numbers.
There is also a compelling explanation for why the AI trade accelerated again after initially appearing to lose momentum. Massive government support for AI infrastructure helped provide one catalyst. So did soaring equity valuations and extraordinary levels of circular financing throughout the industry. Higher valuations encouraged more investment. More investment generated more spending. More spending created revenue for AI infrastructure companies. That revenue then helped justify still higher valuations.
The result was a reflexive investment and stock-price momentum boom. The problem with reflexive booms is that the feedback loop must continue for the boom to sustain itself, and several parts of that loop now appear to be weakening. Political enthusiasm for massive AI infrastructure investment is encountering resistance. Hyperscalers are spending astonishing amounts of money. Debt and off-balance-sheet commitments are growing. AI-related companies continue issuing both debt and equity. And the aggregate market capitalization attached to the ecosystem has become enormous.
At some point, somebody has to finance all of it.
That is why the funding cycle matters more than whether AI itself succeeds or fails. The argument isn’t that artificial intelligence is going away. It is that the rate at which incremental capital can continue flooding into AI may have peaked. In market terms, the second derivative may be turning negative. Even if investment and spending remain enormous in absolute terms, a slowdown in their rate of growth can have major consequences for valuations built around expectations of continued acceleration.
Another underappreciated issue is the industry’s use of ARR, or annualized recurring revenue. Wall Street generally places a premium on genuinely recurring revenue because subscription businesses tend to have predictable customer relationships, contractual commitments, meaningful switching costs, and relatively durable cash flows. Those characteristics can justify much higher valuation multiples.
But it is far from clear that frontier AI revenue deserves to be treated the same way.
Customers can switch models. Open-source alternatives continue to improve. Prices are falling. Workloads that run on one frontier model today could potentially migrate somewhere else tomorrow. Technological improvements could also produce smaller and cheaper models that dramatically reduce the need for gigantic frontier models. Revenue generated under those circumstances may be valuable, but it doesn’t necessarily possess the characteristics investors normally associate with an annuity-like recurring revenue stream.
That distinction becomes especially important if frontier AI companies are preparing IPOs. Whether Wall Street treats billions of dollars of AI sales as ordinary revenue or high-quality recurring revenue could have an enormous impact on the multiples investors are willing to pay.
All of which brings the argument back to the original question: Why now?
If frontier AI economics are rapidly improving, demand is exploding, pricing is durable, competitive advantages are strengthening, and these businesses are heading toward tremendous profitability, there should theoretically be less urgency to access the public markets. The apparent rush itself may therefore be telling us something about where the industry’s funding cycle stands.
The larger point extends well beyond any individual IPO. Markets rarely turn because investors collectively decide that an important new technology is worthless. The internet didn’t disappear when the dot-com bubble burst. Fiber-optic networks didn’t disappear. E-commerce didn’t disappear. Many of those technologies ultimately became even more important than their biggest boosters imagined.
What disappeared was the willingness to finance virtually anything associated with those technologies at virtually any price.
That is the distinction investors need to understand today. AI can change the world and still be an investment bubble. And if the marginal dollar available to finance that bubble has already peaked, the consequences could extend far beyond OpenAI and Anthropic. Kass concluded:
"My view, the revenue the frontier models have is no different than the revenue Netscape, Yahoo, We Work, Nike, Kodak, Zerox, Polaroid, Mikes Buggy Whip Company or Pete’s Vinyl Record Company had. It is not ARR and should not be quoted that way. Nor should the auditors or bankers allow for that in my opinion.
Further, I have argued (above) that these companies do not belong public and should not be public but are rushing to go public because they (and their investors including the circular ones) have all of the exact same concerns I do. I ask again, what is the rush? I think their own behavior in this regard speaks volumes."
For the most part, I agree with Doug. AI can be revolutionary technology while the financial ecosystem surrounding it can still be batshit insane. When companies invest in one another, buy from one another, lend to one another, and then point to the resulting revenue as proof that everybody deserves a higher valuation, you don’t have to be Jim Simons, barefoot, smoking a cigarette and pacing around the Renaissance offices to understand why the math may not be sustainable…
Where I’d push back slightly is on timing. Doug knows this, but I’ll say it anyway. Ponzi schemes can run for years. Credit has an almost supernatural ability to materialize whenever enough bankers, investors and politicians need the casino to stay open. Just look at our national debt. “This can’t go on forever” is almost always true. The problem is that forever has a remarkable ability to get refinanced.
So I think Doug is right to keep asking, “What is the rush?”.
I’ve already gone on record and said Nvidia could be the market’s next black swan and that I’d never in a million years own CoreWeave. If the economics are really this magnificent, why is everybody suddenly racing for the exits marked IPO? But bubbles don’t end because a few people notice the math looks “a little questionable”. They end when somebody is bludgeoned in the face with reality, when they finally ask for their money back and they discover hoping for a check from the next guy’s checkbook was the entire business model. Wall Street is exceptionally talented at finding one more dollar to keep the machine running, right up until the morning it suddenly can’t.
Disclosure: We recently shorted $NVDA and $CRWV (both put on three days ago....
@thestreetpro for "More Tales From Nvidia"
@edzitron@DarioCpx@RealJimChanos@squawkbox@cnbcfastmoney @cnbchalftime @andrewrosrkin @joesquawk@BeckyQuick@saraeisen@guyadami@SullyCNBC@carlquintanilla@TheJudgeCNBC@joesquawk@tomkeene@lisaabramowicz1@maddow@sruhle@business@annmarie@FerroTV@convertbond@KeithMcCullough @SamofAmerica @RPKent @HedgeyeDJ@gnoble79@pboockvar@LanceRoberts@whitneytilson@BobPisani@DanielTNiles@terranovajoe@jimcramer@jeffberkowitz1@JohnFMauldin
Post Script: After having been blocked by @fundstrat@DivesTech for my critical analysis of AI - I am feeling ever more confident.
Will the irony is whenever his stocks fall dramatically, Drawdown Josh Brown retreats about talking stocks and instead give his big picture strategy and risk management techniques in a most condescending manner.
The fact of the matter is that the asset management he works for doesnt buy individual stocks (they invest in ETFs).
What Drawdown doesnt say and the host doesnt mention is that he buys oddlot positions in the stocks he mentions that @halftime trumpets with importance and relevance.
He is being groomed to be the next Jim Cramer.
God help @cnbc viewers.
Stated simply.
@DougKass Repost the Clown Josh Brown.
MU 950 to 609 -36%
SNDK 170 to 81 -52%
MU 950 to 609 -36%
In 3 weeks! Can you imagine some poor bastard had these on leverage? The "Can you, unbelievably cheap, it's true." How does he run a firm? Recites lines from movies about Wall Street. Geeze
Respectfully Tim @timseymour you have owned and recommended gold into a $100 drop in $GLD over the last several months (to $324).
Tonight @CNBCFastMoney you gave no fundamental or technical indication why the descent should not continue. Beyond the standard currency debasement dollar you seem to use technicals and moving averages.
Try fractals. - it might help. @KeithMcCullough@HedgeyeDJ@RPKInvestor
1. $CRWV has fallen from $50 to $40 in the last two trading days. Any thoughts after you suggested on Wednesday that "this should make you rethink your CoreWeave short) with Brian Venturo purchasing unsecured bonds?
2. With the SEC news (investigation of $NVDA accounting), do you still suggest Jensen Huang should get a pre pardon from President Trump?
3. Do you still admire the former CEO of $NVDA and support his return?
Bravo to @MelissaLeeCNBC in addressing @DivesTech bullish AI narrative.
Finally someone on @cnbc stands up to the perm bullish pablum.
Credit where credit is due.
JUST IN: Michael Saylor's 'Strategy' currently has a $14,100,000,000 unrealized loss on its Bitcoin investment.
Tom Lee's 'Bitmine' currently has a $10,100,000,000 unrealized loss on its $ETH investment.
"CNBC: Breaking News, there is a massive asteroid that will take out planet earth in approximately 3 hours"
"Tom Lee: believe it or not extinction events are actually quite bullish for equities"
As I am watching the @CNBC@HalftimeReport , I am thinking that the tape makes it very easy to be really negative right now. I feel it! That said, I do agree with @Stephanie_Link on both sentiment and fundamentals. We’re approaching what feels like peak pessimism, without an obvious catalyst to turn markets higher.
But I’m not so sure this isn’t another correction driven by a confluence of events rather than a fundamental change in the economic outlook. Political uncertainty following the midterms, a more hawkish Fed, AI capex concerns, the enormous Anthropic IPO absorbing liquidity, and uncertainty surrounding Nvidia leadership have all converged at once.
Meanwhile, the economic growth impulse from AI investment is still ahead of us, and earnings fundamentals remain relatively resilient. I believe the next leg higher can include both technology and broader market participation.
The biggest risk to the economy may be a continued market decline itself, weighing on confidence, spending and investment. This is a real risk, So it’s smart to be nervous. But we’ve seen this before.
Investors often buy when they shouldn’t and hesitate to move forward with their plans when they should.
Markets bottom before the news gets better. Maybe the catalyst is simply running out of sellers.
@NewEdgeWealth@TheJudgeCNBC
The most amazing thing about panelists and guests on Fin TV is that no one will admit to being wrong.
Not @DivesTech not @FundstratDirect not @yardeni not Dr. Jeremy Siegel not Drawdown or Slink or Farmer Jim - no one.
No one takes ownership, everyone wants to polish their image/franchise in order to sell a service or gather more assets.
Everyone smiles, thought their wallet may be aching.
Think about it before you turn on Fin TV.
Think about it hard.
Seek the contrary, always.
Even if you don't immediately act upon it.
@KeithMcCullough@Hedgeye_HGRO@RPKInvestor@HedgeyeDJ@gnoble79@QTRResearch@edzitron@justdario@guyadami
just a reminder that aside from me there was a small cohort of people who have been shouting from rooftops over the last 2 weeks that this $NVDA thing would/will get worse. they are all worth a follow:
@edzitron@gnoble79@kakashiii111@michaeljburry@muddywatersre@rdd147
Today, 5,300 Anthropic insiders have more wealth than 45 million American families combined. There are 271 separate tax loopholes costing $2.3 trillion a year. That's more than Medicare and Medicaid combined.
It's time to fix our broken tax code, close the loopholes, and restore some fairness. We need a tax code that rewards creating wealth for every American, not preserving wealth for the select few.
@TheDomino@KellyCNBC \\Here you go...
BY DOUG KASS · Aug 25, 2026, 9:35 AM
Debunking the Core Bullish Argument That Strong EPS Equates to Strong Price Gains
The investment mosaic is far more complicated than suggested by hosts, investment strategists, panelists and guests in the business media.
First-Level Thinking Vs Second-Level Thinking
Specifically, many distill the bullish argument to this: Since 2026 S&P EPS is expected to be about +20% (well above consensus expectations at the beginning of the year), the S&P price gains in 2026 should be about in line with that profit growth (or better).
Candidly, that sort of distillation is the essence of “first-level thinking.”First-level thinking is lazy, simplistic and superficial — it looks for simple formulas and easy answers.
To paraphrase Howard Marks:First-level thinking says, “S&P EPS growth will be strong, let’s buy the market.”
Second-level thinking says, “S&P EPS growth will be strong, but everyone knows it. Stocks are fairly or overpriced, let’s sell the market.”
Most recent examples of when S&P EPS was better than expected and strong were in 2018 (+20.5% EPS growth, -6.6% decline in the S&P), 2006 (+16.7% EPS growth, +11.3% rise in the S&P), 2005 (+19.3% EPS growth, +8.8% rise in the S&P) and 2004 (+20.1% EPS growth, +4.2% rise in the S&P).Going back, during the last 50 years — other 12-month periods with robust EPS growth and less-than-stellar to down S&P price include the years 1993, 1992, 1987, 1984, 1979 and others.S&P 500 Index
Furthermore, I would argue that the backdrop of 2026-2027 offers unique market challenges relative to prior periods since 1975 (“it’s different this time”):
* High and rising inflation and interest rates.
* A burgeoning deficit and U.S. debtload may be a permanent condition giving the general lack of discipline from both parties in Washington DC.
* Improvisational geopolitical and fiscal policies that present threats to political and economic stability.* Both parties are moving to extremes — the Republican party more to the right and the Democratic party to the left. With a possible Democratic congressional majority win in November, anti-corporate policy (higher corporate taxes, etc.) may be in the offing.
* Traditional valuation metrics in the 98%-tile and two standard deviations above the average.
* The AI capital spending spree and gains from investments have inflated S&P profit reports — as noted in my “More Tales From Nvidia” series an earnings reckoning may lie in the not too distant future.
Bottom Line
Looking at any one variable (e.g. S&P EPS growth) to forecast S&P price is fatuous, simplistic, lazy and is contradicted by past investment returns data.Stated simply, the correlation between S&P EPS growth and S&P price gains is a crutch and is not a reliable indicator.
Historically, elevated consensus long-term earnings growth rates have been a contrarian indicator.
The investment mosaic is far more complex than many present in the business media.==========================================================================================================
@TheDomino@KellyCNBC
Doesn't anyone pushback on guests' errant market forecasts?
Is access more important than the investment well being of your viewers?
Isn't honesty the best policy?
The foundation of Ed Yardeni's bullish forecast (as well as most of the others like @fundstrat) is the strength of EPS growth.
But, what is the message in the shares of $NVDA, $MU (which account for 36% of the projected S and P EPS growth)?
The answer: Semis, memory, AI related are all over earning and the forward prospects will likely be ratcheted lower.
Moreover, as I have challenged other people on @CNBC - EPS is not the sine quo non. Often the market anticipates weaker profits and discounts it well in advance - producing many years when S and P prices departed from the strength in S and P earnings.
@dougkass@KeithMcCullough@Hedgeye_HGRO@RPKInvestor@HedgeyeDJ@gnoble79@yardeni
@TheDomino@KellyCNBC
Doesn't anyone pushback on guests' errant market forecasts?
Is access more important than the investment well being of your viewers?
Isn't honesty the best policy?
The foundation of Ed Yardeni's bullish forecast (as well as most of the others like @fundstrat) is the strength of EPS growth.
But, what is the message in the shares of $NVDA, $MU (which account for 36% of the projected S and P EPS growth)?
The answer: Semis, memory, AI related are all over earning and the forward prospects will likely be ratcheted lower.
Moreover, as I have challenged other people on @CNBC - EPS is not the sine quo non. Often the market anticipates weaker profits and discounts it well in advance - producing many years when S and P prices departed from the strength in S and P earnings.
@dougkass@KeithMcCullough@Hedgeye_HGRO@RPKInvestor@HedgeyeDJ@gnoble79@yardeni