$IREN signed a 5-year contract generating $22M in annual revenue per MW.
By locking in prices for five years, IREN is sacrificing enormous potential upside from rising AI compute prices.
But in exchange, it’s securing a customer prepayment covering approximately 90% of GPU CapEx.
And in today’s debt market, that’s a massive advantage.
At the beginning of 2026, AI infrastructure contracts were generating $10–15M in annual revenue per MW.
Today, some short-term agreements are reportedly commanding over $50M per MW.
IREN itself signed a shorter-term contract generating over $40M per MW annually.
This is exactly why Elon Musk reportedly wants $SPCX to avoid long-term fixed-price contracts.
With AI compute demand growing faster than supply, preserving pricing flexibility allows providers to capture higher prices as the market tightens.
But IREN is making a different calculation.
By securing 90% of GPU CapEx upfront, it dramatically reduces its dependence on expensive debt and potential shareholder dilution.
Instead of tying up billions of its own capital in GPU deployments, IREN can use customer financing to accelerate its expansion.
$SPCX is preserving pricing flexibility to maximize future revenue per MW.
$IREN is sacrificing some of that upside to secure the financing needed to bring more MW online.
IREN is trading future pricing upside for cheaper capital today. And given the current debt market, that’s a trade-off worth making.
Peter Lynch turned $18M into $14B by simply following these 6 stock investment rules:
1. Trailing P/E < 25x
2. Forward P/E < 15x
3. EPS Growth > 15%
4. PEG Ratio < 2
5. Debt/Equity < 35%
6. Market Cap > $5B
Short, simple, & has proven success for decades.
Save this for later…
OMG SHE JUST DID IT AGAIN
Cathie Wood is basically telling you EXACTLY which stocks to buy to get RICH
Here are the 6 companies she just loaded up on :
1) $PLTR - Just bought yesterday
🚨BREAKING
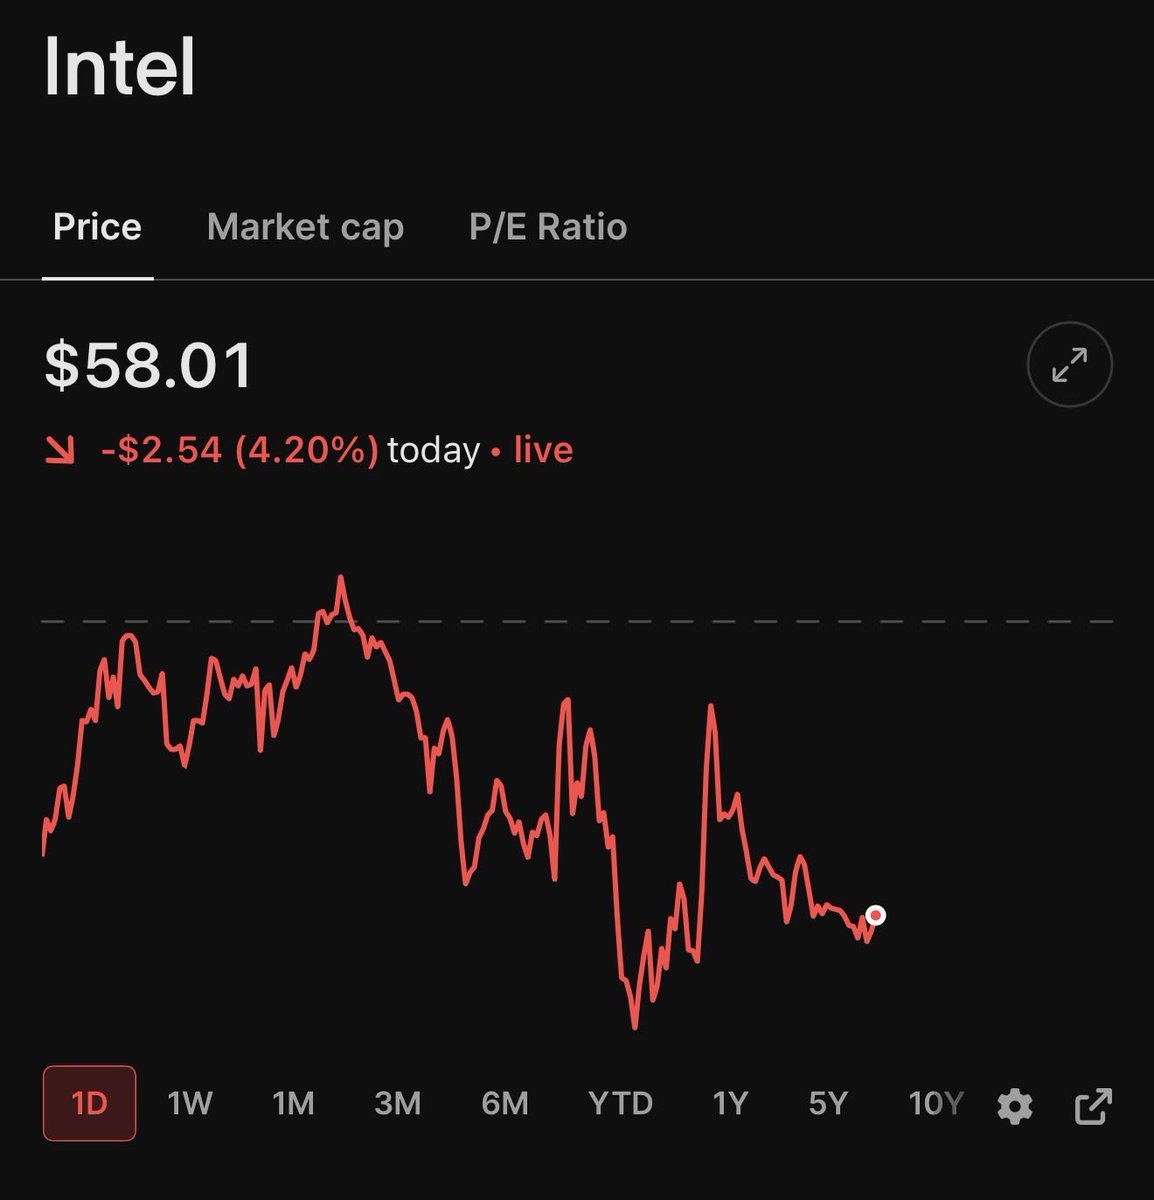
$INTC CEO BOUGHT THE DIP
CEO Lip Bu Tan bought $10M of the stock back in August when it was trading at $95.
2 days ago, he doubled down and invested $10M more, when the stock was trading at $65.
20 politicians hold Intel including Nancy Pelosi
$TE just signed another 1.6 GW in solar supply agreements for 2027 and 2028 bringing its contracted 2027 module capacity above 4 GW.
That’s over 80% of next year’s production already spoken for as T1 prepares to bring its Texas solar cell factory online in Q1 2027.
🚨 UYARI: KORKUNÇ BİR ŞEY TAM AZ ÖNCE OLDU
Çin'in hisse senetleri %40'tan fazla çöktü.
Yapay zeka balonu resmen ÇÖKÜYOR.
Piyasayı dengelemek için Çin, 100 MİLYAR DOLAR'dan fazla ABD Hazine Bonosu'nu elden çıkarıyor.
Bu, 2007'den beri en büyük satış.
Bu arada, Çin'in altın rezervleri rekor 325 MİLYAR DOLAR'a yükseldi.
Çin hisse senetleri elden çıkarılıyor.
ABD borcuna maruz kalma azalıyor.
Altın rezervleri genişliyor.
Ama en büyük sorun neredeyse hiç kamuoyunun dikkatini çekmiyor.
Çin, ALTIN'ı kullanarak yuanın küresel finans sistemindeki konumunu güçlendiriyor.
ABD doları sistemi dışında işleyen alternatif ödeme ağları ve finansal altyapı kuruyor.
Temmuz 2026'da, Hong Kong'un devlet destekli altın takas sistemi deneme operasyonlarına başladı.
Ve doğrudan Şanghay Altın Borsası'na bağlı.
Çin, yuanın küresel finanstaki etkisini genişletmek için uluslararası altın kasası ağı kuruyor.
Ama bu sadece bulmacanın bir parçası.
Çin ayrıca blok zinciri ödeme altyapısını etkin bir şekilde geliştiriyor.
Görev net:
DÜNYANIN ABD DOLARI'NA BAĞLILIĞINI KIRMAK.
Ve ALTIN bu stratejinin merkezinde.
Çin şimdi 23 AYDAN FAZLA SÜREYLE ARALIKSIZ altın satın aldı.
Aynı zamanda, küresel finans sistemi büyük bir dönüşüm geçiriyor:
→ Çin'in hisse senedi piyasası AYI PİYASASI'na girdi
→ Çin'in altın rezervleri büyümeye devam ediyor
→ Güney Kore, 13 YIL sonra altın alımlarına yeniden başladı
→ Ülkeler ABD Hazine varlıklarını azaltıyor
→ Altın tahsisleri artıyor
→ Merkez bankaları rezerv stratejilerini yeniden düşünüyor
BU, YAPAY ZEKA BALONUNDAN ÇOK DAHA BÜYÜK.
Bu, ÇOKLU ülkeleri içeren temel bir ekonomik değişimle ilgili.
Ve sonuçları devasa olacak.
Altın, küresel rezerv varlığı olarak ABD Hazine Bonoları'nı geçti.
Almanya, Hollanda ve Fransa, devasa altın rezervlerini ABD'den ÇIKARIYOR.
Ülkeler sadece altın biriktirmiyor.
ONLAR FİNANSAL STRATEJİLERİNİ YENİDEN TASARLIYOR.
Rezervlerini taşıyorlar.
Uluslararası ödemelerin nasıl çözümlendiğini değiştiriyorlar.
Parçalar şöyle bağlanıyor:
Düşen Çin Hisse Senetleri → Büyüyen Altın Rezervleri → Daha Az ABD Hazine Bonosu → Azalan Dolar Bağımlılığı → Alternatif Ödeme Ağları → YENİ BİR KÜRESEL FİNANSAL DÜZEN.
Daha fazla ulus bu stratejiyi benimserken, ABD doları üzerindeki baskı artacak.
Küresel finans sistemi böyle değişir.
Yavaşça.
Sessizce.
Sonra bir anda hepsi birden.
DİKKAT EDİN.
Çünkü çoğu insan olan biteni fark ettiğinde, çöküş çoktan başlamış olacak.
Piyasaları inceleyip büyük zirve ve dipler çağırarak 12 yıldan fazla zaman harcadım.
2026-2027 döngüsünde en ÜST %1'e girmek ve hayatta kalmak istiyorsanız, takip edin ve bildirimleri açın.
Birçok insan daha erken dikkat etmediklerine pişman olacak.
Soy profesor universitario y considero importante compartir lo que me está tocando ver desde que arrancó el curso, porque es un verdadero desastre.
Esta generación de estudiantes lleva IA, YouTube, Google y toda la información del planeta en el móvil y siguen sin saber nada.
No saben dónde está Roma ni tampoco Huelva, no saben quién es Pérez Revere pero todos conocen a Lola Lolita, no tienen ni idea de historia pero sí de “stories”, no entienden el valor del dinero ni saben cómo funciona la inflación.
Antes, para ser ignorante bastaba con no abrir los libros. Ahora, asisten activamente a clases para no enterarse de nada.
Y encima son de cristal. Cualquier roce es un trauma, cualquier crítica es violencia, cualquier tarea es un atentado y cualquier suspenso es un «ataque» a su salud mental. Y si llueve no vienen a clases, no sea que se derritan.
Han convertido los retos normales de la vida en un espectáculo de victimismo. En lugar aprender a gestionar los problemas que van saliendo en sus vidas, han aprendido a pedir soluciones a los demás y a deprimirse si algo no sale bien.
Tantos años de progresismo abyecto ha resultado en esto, y después de años viviendo entre algodón, sin golpes y sin aprender a levantarse, han creado una generación de ofendiditos con mentes vacías que todavía intentan averiguar qué son.
Eso sí, opinan sobre cualquier tema con una convicción, una superioridad moral y una pasión que asusta, pero con argumentos huecos y no sustentados que son el producto del lavado de cerebro que han recibido de la narrativa woke que han venido escuchando los últimos años.
Si no fuese por ese puñado de estudiantes (con futuro) cuyos padres se preocuparon en formarlos con valores y principios, sería esta, una generación prácticamente perdida.
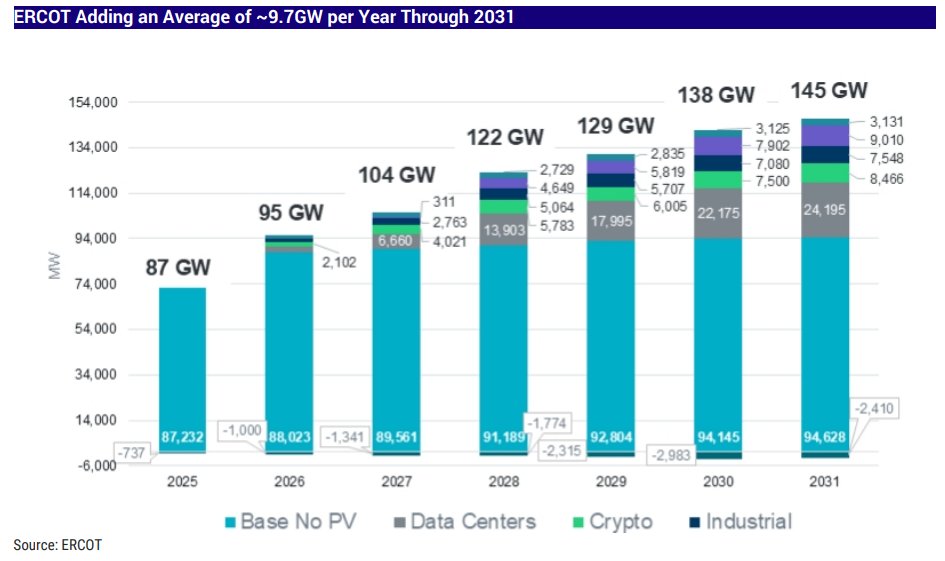
ERCOT is forecasting Texas electricity demand rising doubling to 145 GW by 2031 which is about ~10 GW per year so meeting that demand requires a lot more power at every step of the chain:
• $VST monetizes generation thats already operating and connected to the Texas grid
• $GEV supplies gas turbines needed to bring new generation online
• $BE brings power directly onsite when data centers cannot wait for grid connections
• $VRT handles power and cooling infrastructure once that electricity reaches data center
Essentially every new gigawatt creates another opportunity across generation, grid access and infrastructure inside the data center.
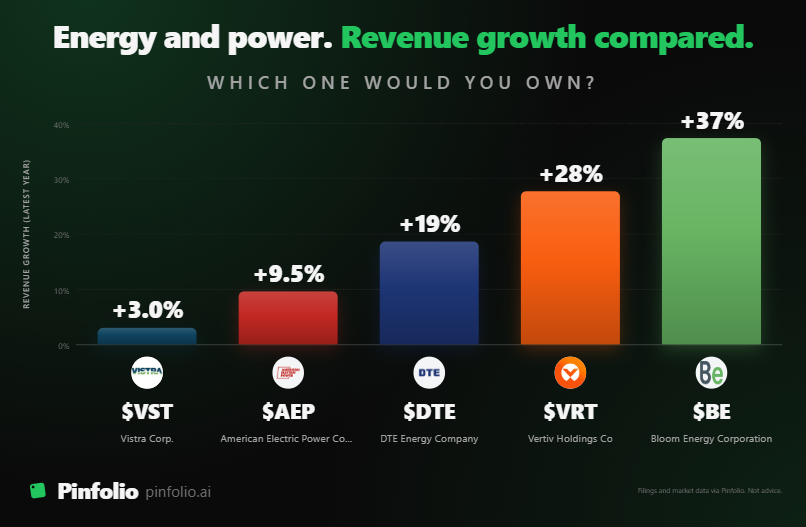
ENERGY AND POWER, REVENUE GROWTH COMPARED ‼️
$BE | Bloom Energy: +37%
$VRT | Vertiv: +28%
$DTE | DTE Energy: +19%
$AEP | American Electric Power: +9.5%
$VST | Vistra: +3%
Which one would you rather own?
Bill Ackman: “If a company is increasing growth capex while earning above average returns, you should applaud.”
With JP Morgan raising $META price target from $640 to $820, the market finally stopped doubting the AI bet and started to applaud it.
This is just the beginning.
Stanley Druckenmiller said earlier this year that he was short the US bonds.
US 30-year bond prices have just fallen to the lowest level since 2007.
Insane.
Ray Dalio: “If you don’t own gold, you don’t know history, and economics.”
He says gold becomes attractive when other currencies are unreliable.
Gold ETF holdings have just reached record highs as reliability of the dollar has been eroding.
This is just the beginning.
JP Morgan sees gold at $8,000 if private investors increase their average gold allocation from 3% to 4.5% in response to eroding trust in fiat.
Interest costs on global government debt have never been higher:
Gross interest expenditure among OECD countries surged +$180 billion YoY in 2025, to a record $2.24 trillion.
This marks the 4th consecutive annual increase, totaling +$960 billion.
The US accounted for ~65% of the total, at $1.45 trillion, while the EU represented ~18%, or $400 billion.
As a % of global GDP, gross interest costs stood at ~3.2% last year, their 2nd-highest level in at least 20 years.
Meanwhile, OECD countries are estimated to borrow another $18 trillion in 2026, the highest annual total on record.
The global debt crisis is spiraling out of control.
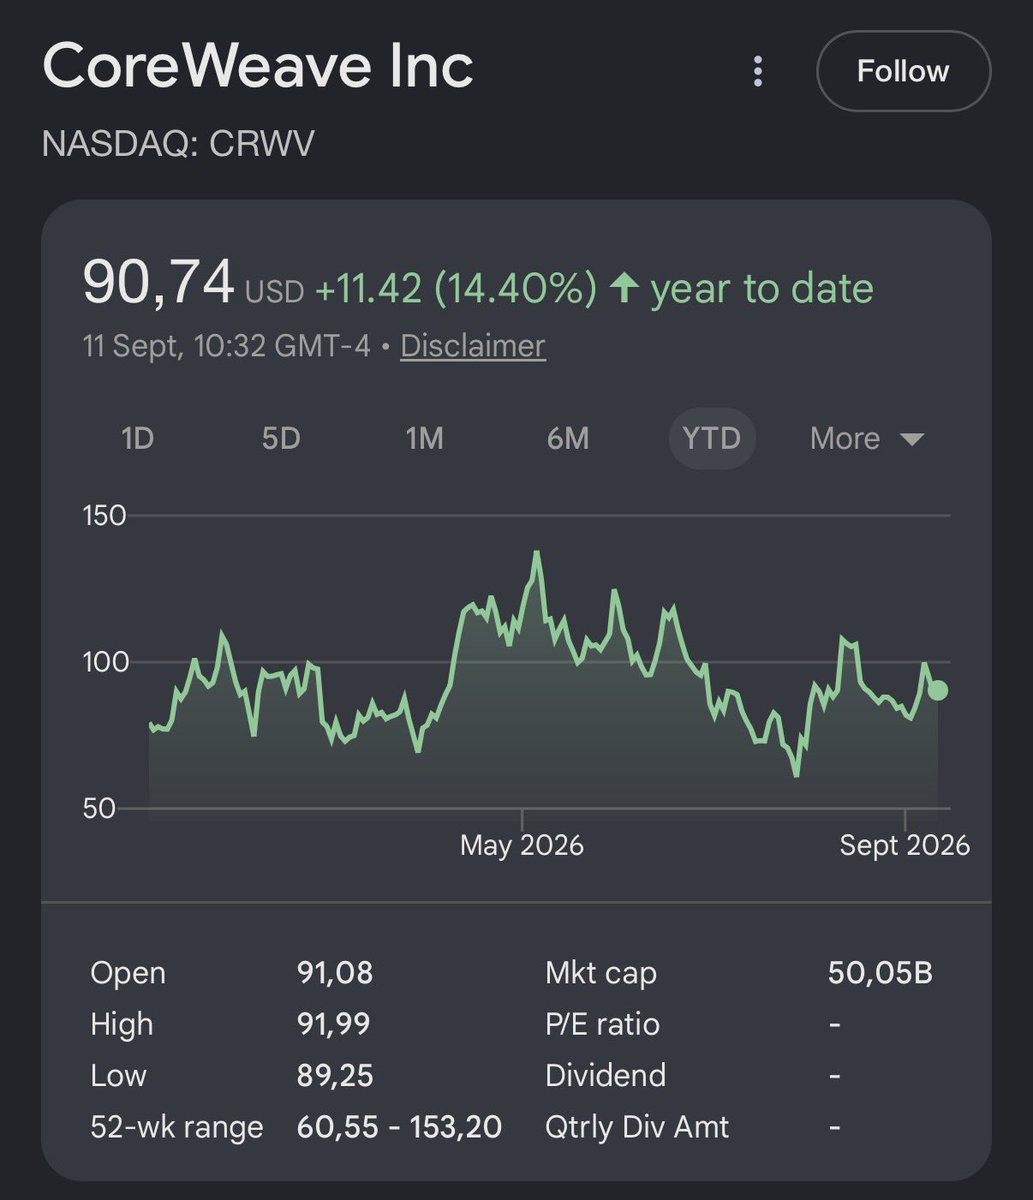
Let’s take a minute to think why $CRWV is the obvious play right now shall we?
- OpenAI has nailed it with the latest models and products, growth is accelerating and it’s taking market share, de-risking its compute providers.
- $MSFT, the biggest customer of $CRWV, has committed to add over 30 GW of capacity by 2032 as it’s short of compute. Given the shortage, it’s not likely to cut third party capacity. This means $MSFT business is safe for the medium term.
- It’s still trading at a serious relative discount to $NBIS.
- Compute prices are holding up as H100 rates are at the same level as 2022.
- Leopold is back in the game with $CRWV calls, which will likely support the sentiment.
Feels like an obvious play here.
AI is about to become the biggest fossil fuel customer on earth (Save this).
BloombergNEF's data shows incremental generation needed for data centers climbing from a rounding error in 2025 to roughly 1,350 TWh by 2035 and the two largest blocks in every single year are gas and coal.
BNEF projects US data centers will consume 20% of the country's power in 2035, up from 5.9% today, or as much as 194 GW.
That is nearly double what BNEF forecast eight months earlier and even assuming record grid additions plus hyperscaler self generation, they still model a 19 GW shortfall by 2035.
Interconnection queues run three to five years and up to seven to ten in congested regions like Northern Virginia.
Renewables cannot fill the gap because a 24/7 AI cluster needs firm output rather than intermittent capacity.
Renewables and storage make up 56% of the capacity needed, but fossil fuels supply 64% of the incremental generation.
BNEF's least cost model through 2050 calls for roughly 370 GW of gas and 110 GW of coal, with most incremental coal coming from plants delaying retirement.
The gas turbine shortage is the single best trade in this chart.
GE Vernova's combined gas backlog and slot reservations went from 83 GW at end 2025 to 116 GW in Q2 2026, with management guiding to at least 125 GW by December.
Order a heavy duty turbine today and it arrives in 2031 because global manufacturing capacity is only 60 to 70 GW per year against roughly 110 GW of outstanding orders.
New orders in the first half of 2026 priced 10 to 20 percentage points higher on a $/kW basis than Q4 2025 and hyperscalers are paying non refundable deposits to outbid regulated utilities for 2029 and 2030 frames.
Meanwhille, coal block is the most contrarian part of the trade.
At least 15 US coal plants have postponed or canceled retirements since January 2025, driven largely by AI data center demand.
Southern Company extended two Georgia coal plants to 2039, which means assets the market wrote off as stranded now have a decade of extra cash flow.
The turbine oligopoly of GE Vernova, Siemens Energy, and Mitsubishi Heavy is the purest expression, since only three companies build these machines and their books are full to 2031.
Bridge power names like Caterpillar, Cummins, and Bloom Energy capture the 19 GW shortfall, because engines and fuel cells are the only things delivering inside 24 to 36 months.
IPPs with existing firm generation, including Vistra, Constellation, NRG, and Talen, own the fleet data centers need before any new turbine arrives.
Gas producers like EQT, Expand Energy, and Coterra sit against 617 TWh of incremental US gas generation through 2035, while grid names such as Eaton, Quanta, and Vertiv ride an Electrification backlog up 69% year over year.
Coal life extension plays like Peabody and Alliance Resource map to the 110 GW of coal in BNEF's model.
AI’s next bottleneck is power and the companies supplying gas turbines, firm generation, backup power, and grid equipment could be some of the biggest winners.
If you want to see exactly how we’re positioned around this power trade, check out the link below and come join us for just $1.
https://t.co/thIhK9ZH4E