$HIMS: $2.9B in revenue over the last 12 months. The whole company is worth about $4B.
The stock is down almost 40% in a month and 77% from its high.
I'm not judging it on the share price. Subscribers and gross margin are my test.
Anthropic starts trading on the Nasdaq today. It priced at $83 a share, above the $70-78 range, valuing it at about $1.5T.
$AMD is putting $2.5B into Anthropic at that IPO price.
For my largest position, that's a public price on one of the biggest buyers of AI compute.
How much of every sales dollar 7 of my holdings turn into free cash, last 12 months:
Palantir 56%
AMD 16%
Zeta 15%
Meta 12%
Celsius 8.5%
Hims 0.3%
Super Micro -12%
Revenue growth gets the attention. I judge my stocks on the cash they keep. For Hims, that number has to go up.
$ZETA hit an all-time high last Friday. It's now about 14% below it.
There's no company news behind it. Same business that just raised its outlook again.
I don't sell a business because of a few bad days.
$NVDA did $115.8B in revenue last quarter, up 103%. It guided $130B for this one, above the ~$125B the street expected, and that assumes zero data center sales to China.
The stock is still down this year.
For my AMD position, this was the answer I wanted: the market AMD competes in is still growing fast.
$NOK grew sales to AI and cloud customers 123% last quarter. Orders from them grew 118%.
The stock is down 44% in six months.
My test for Nokia is simple: AI networking orders showing up in the results. Last quarter they did.
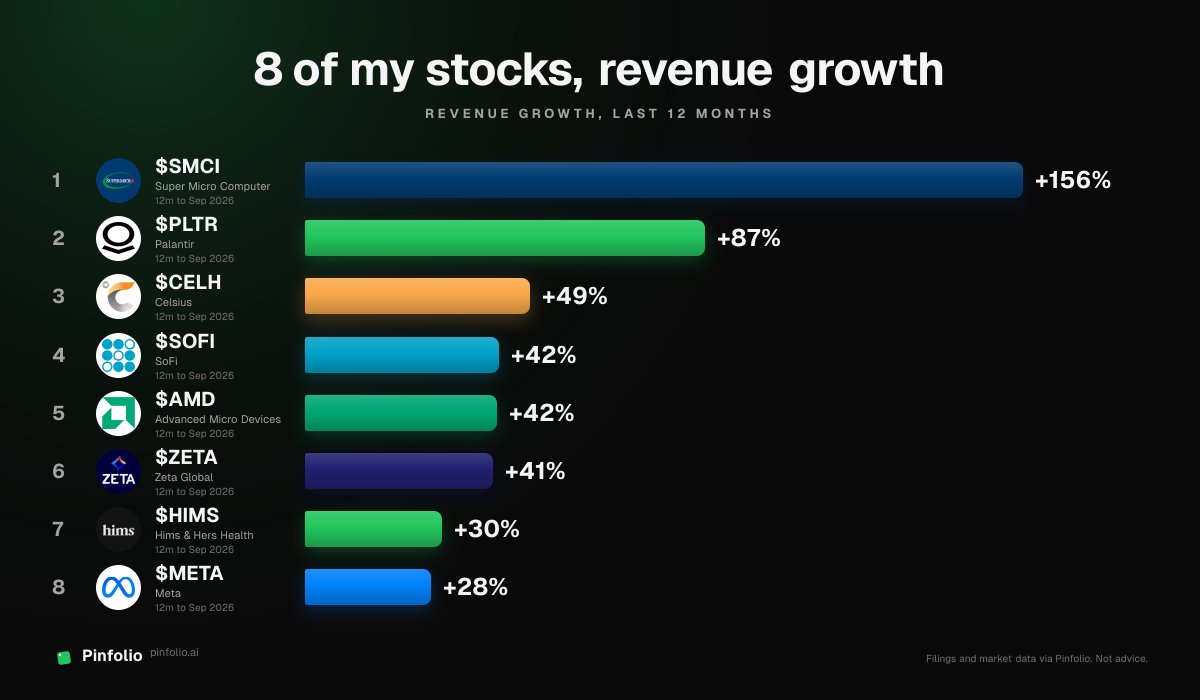
8 stocks in my portfolio, ranked by revenue growth over the last 12 months. The slowest still grew 28%.
Same 8 by share price this year: only AMD and ZETA are up.
Every business growing, six of eight stocks lower. When a business keeps delivering, the price follows eventually.
$NVDA reports tonight. It guided to $108B in revenue for the quarter, almost double the $57B of a year ago.
The stock is still about a third below its all-time high.
For my AMD position, the beat matters less than one thing: how much visibility Nvidia's biggest customers give into next year.
$ZETA has beaten and raised its outlook 21 quarters in a row. Last quarter revenue grew 46%.
This year the stock is up 80%.
When a business keeps delivering, the price follows eventually. It's now my largest position.
$META grew revenue 26% last quarter while spending $135-145B on capex this year.
The stock is at $610. About where I bought it.
Most people see the AI spend as the risk. Dilution and taking on debt is not helping. When are we seeing any ROI? Will Muse pay off?
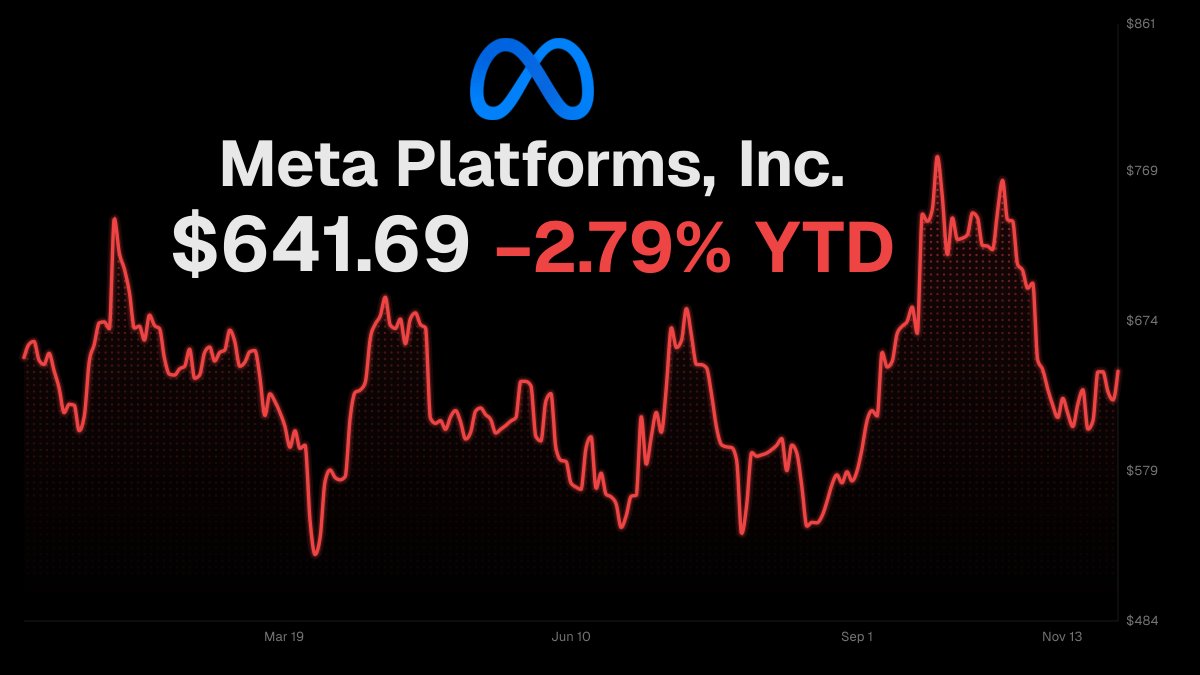
$META did $64.6B in revenue last quarter, up 26% from a year ago.
The stock is down about 3% this year and 19% below its high.
The market is focused on the capex bill. I think Muse will justify it.