Stablecoins established money nnchain, tokenization accelerates assets onchain, onchain capital markets are unifying the entire market apparatus on programmable rails. The financial infrastructure supercycle is taking shape. https://t.co/gDaRT1uvst
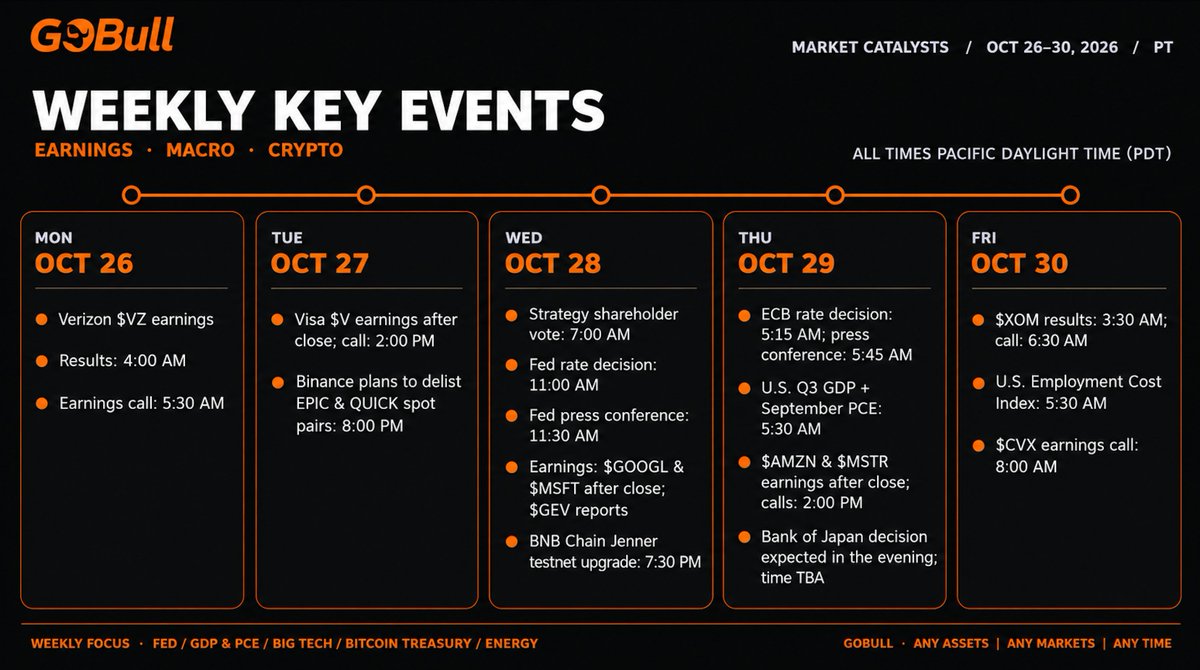
Key Events | OCT26-30
The Fed’s rate decision, earnings from $MSFT, $GOOGL and $AMZN , plus U.S. GDP and PCE inflation.
$MSTR puts Bitcoin treasury strategy in focus, while $XOM and $CVX show how higher oil prices are flowing through to profits.
All eyes on rates, AI spending and cash flow.
Key Events | OCT 26–30
MONDAY, OCT 26
$VZ earnings; call at 5:30 AM PT.
TUESDAY, OCT 27
$V earnings after the close.
WEDNESDAY, OCT 28
#Fed rate decision at 11:00 AM PT.
Earnings from $MSFT , $GOOGL and $GEV.
THURSDAY, OCT 29
Strategy $MSTR earnings after the close.
FRIDAY, OCT 30
$XOM earnings put high oil prices and cash flow in focus.
#OCC released the final #GENIUSAct Act rule on Oct 21 (effective Jan 18, 2027) — the first from any U.S. regulator. Overall looser than the March proposal.
Key takeaways:
1. Yield ban eased (not removed): affiliate yield presumption dropped → case-by-case review
2. More flexible reserves: principles-based + daily liquidity floor + single-counterparty cap
3. Simpler capital rules, clearer backstop requirements
4. Definitions favor issuers: outstanding issuance measured per entity (SPVs only reserve for their own coins)
5. AML/sanctions handled in a separate Treasury rulemaking
Net: more issuer-friendly, especially for multi-entity/SPV structures.
Most of @AnthropicAI $80.7B H1 loss was a non-cash accounting charge. Excluding it, the loss was $8.7B.
At a $1.5T valuation, the concern is slowing growth against $450–600B in compute commitments. Q3 revenue reached $16.8B, but QoQ growth fell from 143% to 45%.
Our valuation model: $1.2T base case, $400B bear case.
👉Read the full report:
https://t.co/7jyWWV2DTk
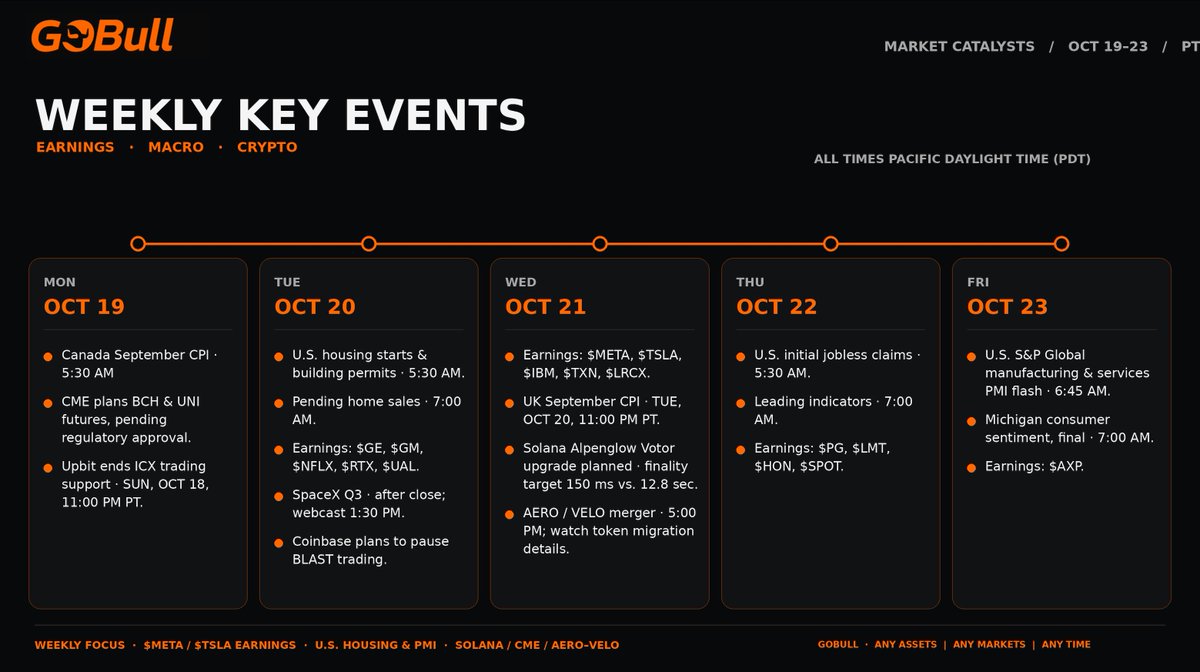
Key Events | Oct19-Oct23👀
Equities: Watch how results from $META , $TSLA and other companies shape tech sentiment.
Macro: Focus on U.S. housing data and Friday’s PMIs.
Crypto: Keep an eye on the $Solana upgrade, $CME’s planned futures launch and the AERO/VELO merger.
Key Events | Oct19-Oct23
MONDAY, OCT 19
Canada’s September CPI, 5:30 AM PT. CME plans to launch BCH and UNI futures, pending regulatory approval.
TUESDAY, OCT 20
U.S. housing data: September housing starts and building permits at 5:30 AM; pending home sales at 7:00 AM. Key earnings include $NFLX, $GE and $GM.
WEDNESDAY, OCT 21
$META and $TSLA earnings are the week’s main corporate events. Crypto markets will also watch Solana’s Alpenglow upgrade and the AERO/VELO merger.
THURSDAY, OCT 22
U.S. initial jobless claims, 5:30 AM PT. Key earnings include $PG, $HON, $SPOT and $LMT.
FRIDAY, OCT 23
U.S. October flash manufacturing and services PMIs, 6:45 AM PT, followed by the final University of Michigan consumer sentiment reading at 7:00 AM.
AI needs more power—and both parties are starting to agree on what it will take to deliver it.
As Washington pushes to speed up infrastructure approvals and Big Tech signs long-term power deals, attention is turning to the companies that build and upgrade the U.S. grid.
Here are the power and energy infrastructure stocks worth watching.👀
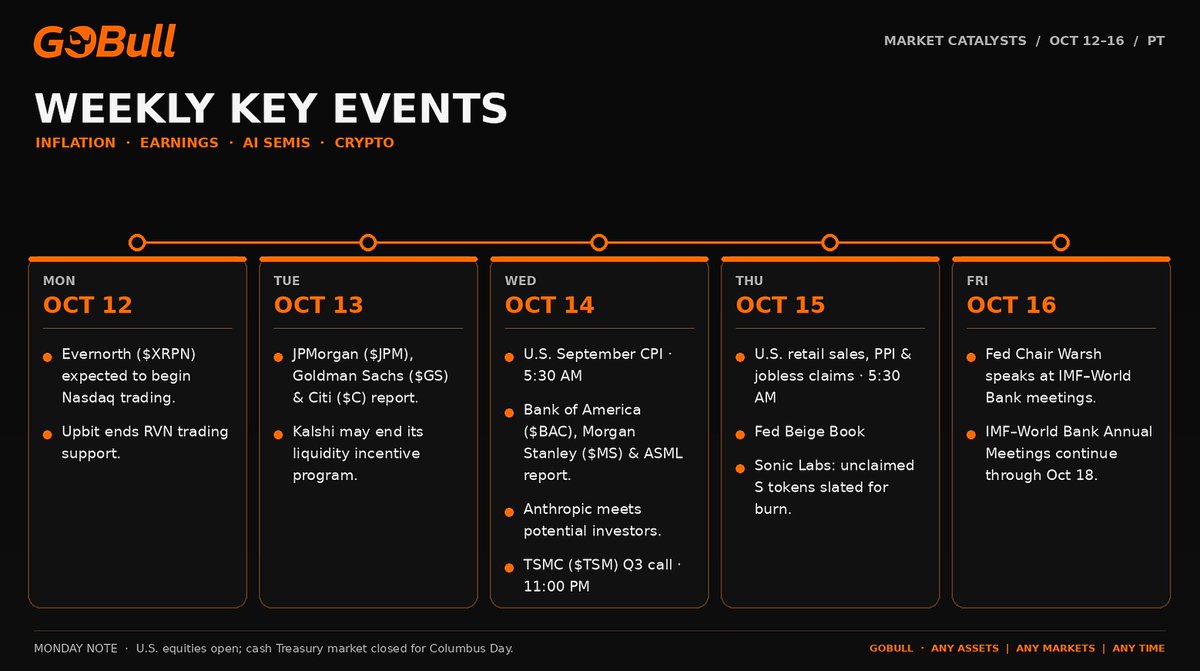
Key events | Oct 12–16
This week’s key catalysts: U.S. September CPI, retail sales, and PPI will shape inflation and rate expectations.
Bank earnings from $JPM, $GS, $C, $BAC, and $MS offer a read on financial conditions and credit quality.
Results from $ASML and $TSM will test the strength of AI semiconductor demand.
Also watch $XRPN’s Nasdaq debut and Fed Chair Warsh’s remarks at the IMF–World Bank meetings.
Key events | Oct 12–16 PT
Mon, Oct 12
Evernorth ($XRPN) is expected to begin trading on Nasdaq. Upbit also ends trading support for RVN.
Tue, Oct 13
JPMorgan ($JPM), Goldman Sachs ($GS), and Citi ($C) report earnings. Kalshi may end its liquidity incentive program.
Wed, Oct 14
The U.S. September CPI takes center stage. Bank of America ($BAC), Morgan Stanley ($MS), and ASML ($ASML) report. Anthropic is also scheduled to meet with potential investors.
Thu, Oct 15
U.S. retail sales, PPI, and jobless claims are due. TSMC ($TSM) holds its Q3 earnings conference.
Fri, Oct 16
Fed Chair Warsh is scheduled to speak at the IMF–World Bank meetings.
🌕 GoBull Moon Landing Carnival Rewards Are Ready to Claim! 🎁
👉 https://t.co/UvfaaMQ52s
Thanks for flying with us. 🌕🐂
See you on the next GoBull mission.
🌕 GoBull Moon Landing Carnival Rewards Are Ready to Claim! 🎁
🏆 $3,000 in rewards are now available for eligible participants.
👉 Claim your rewards here: https://t.co/AwdIBDM30D
Open the Mini App, go to the Claim tab, check your reward status, and follow the on-screen instructions to complete your claim.
Thanks for flying with us. 🌕🐂 See you on the next GoBull mission.
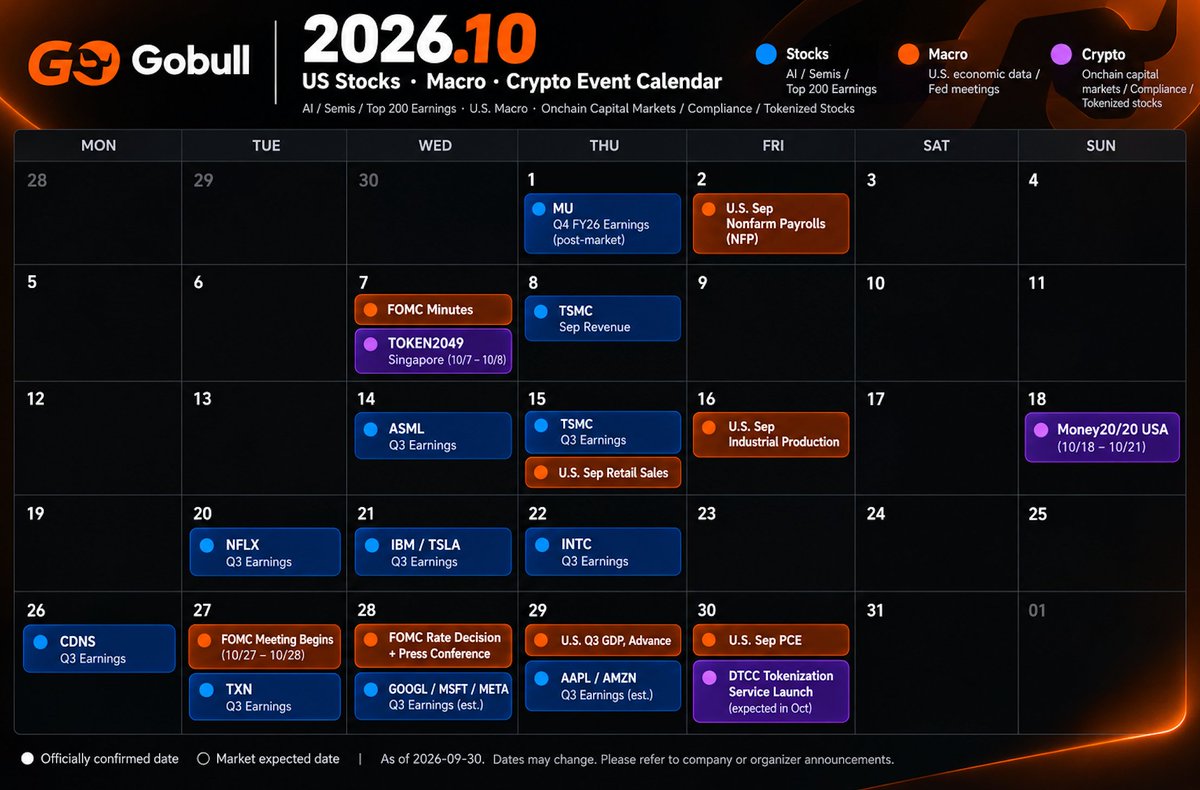
October Key Events
Oct 2 — U.S. Nonfarm Payrolls
Oct 15 — TSMC Q3 earnings
Oct 27–28 — FOMC meeting
Oct 28 — Fed rate decision + press conference, plus GOOGL / MSFT / META earnings
Oct 29 — U.S. Q3 GDP + AAPL / AMZN earnings
Oct 30 — U.S. PCE inflation data
For crypto, TOKEN2049 and the expected DTCC Tokenization Service launch are also worth watching.
Oct 27–30.
Macro, mega-cap tech, and onchain market structure all collide in the same week.
This is what signal discovery is really about. The best traders rarely publish the full picture.
A position here.
A research note there.
A new supply-chain rabbit hole.
Sometimes, silence around the smallest names.
Individually, they’re fragments.
Connect them fast enough, and you start to see the trade before the thesis becomes obvious.
That’s the discovery layer we’re building.
Capture alpha. Trade profitably.
Serenity @aleabitoreddit has been digging into Korea’s AI supply chain.
But some of the most interesting names may simply be too small to talk about publicly.
I went down the rabbit hole and found 7:
$90M–$1.9B market caps.
HBM. Photonics. Testing. Materials.
Some are already on his radar. Others fit the same supply-chain thesis.
Here’s the map 🧵👇
First, the names Serenity has actually touched:
🔥 $138080 OE Solutions — ~$0.25B
Photonics / EML / CW Laser
800G/1.6T, EML and CW lasers → direct exposure to AI data center optics and CPO.
→ Serenity disclosed a position.
🔥 $093370 Foosung — ~$1.05B
WF₆ / Specialty Gas
WF₆ is critical for tungsten deposition. The thesis: memory expansion + potential supply constraints = bottleneck exposure.
→ Direct Serenity research; no position disclosed.
🔵 $322310 AUROS — ~$0.09B
HBM / Advanced Packaging Metrology
Hybrid bonding requires increasingly precise overlay control as packaging complexity rises.
→ Serenity previously owned it, then reduced exposure as hybrid-bonding timelines slipped.
Then there are the names further down the same supply-chain rabbit hole:
🟡 $104830 Wonik Materials — ~$0.30B
Specialty Gases
Samsung + SK Hynix supplier. Advanced DRAM/NAND → higher specialty-gas consumption.
🟡 $089030 Techwing — ~$1.29B
HBM Testing
HBM Cube Prober exposure. More stacked layers → greater testing complexity + higher yield-control value.
🟡 $357780 Soulbrain — ~$1.89B
Semiconductor Chemicals
High-purity etching and cleaning chemicals. More complex memory processes → greater material intensity per wafer.
⚪ $317330 Duksan Techopia — ~$0.19B
Semiconductor Precursors
HCDS, SiCl₄ and other deposition materials tied to DRAM/NAND capex.
The real hunt isn’t for “the next SK Hynix.”
It’s one layer deeper:
AI
→ HBM
→ Advanced Packaging
→ Testing
→ Materials
→ Photonics
Then look for the intersection of:
Small Market Cap × AI Revenue Inflection × Supply Bottleneck
The best picks-and-shovels businesses often sell something that represents only a tiny fraction of the final chip’s cost.
But if that component becomes scarce, billions of dollars of downstream capacity can get held up.
That’s what makes Korea’s AI semiconductor small-cap supply chain worth digging into.
🔥 Direct — explicitly researched / owned
🔵 Weakened — researched, but thesis weakened
🟡 Thematic — closely aligned with the research thesis
⚪ Candidate — supply-chain extension
Burry shorting $NVDA is a headline, shorting chips, memory, cloud, infrastructure, software and the Nasdaq is a signal.
That’s the difference between seeing a trade and discovering the thesis behind it.
BREAKING: Michael Burry is shorting the AI boom.
His $NVDA + $PLTR puts once topped $1B in notional exposure.
And his shorts now span the AI stack.
The bet?
Depreciation. Debt. Overcapacity.
Here’s Burry’s AI Big Short — and what he thinks breaks first.
🧵
1999 $Cisco traded at 130x PE on vendor-financed ghost orders.
2026 $NVIDIA trades around 30x PE backed by trillion-dollar cash reserves.
Why the "higher-for-longer" narrative is failing to stop this cycle:
Fiscal deficits running at 6% GDP are silently out-pumping Fed QT
Hyperscalers earn billions in interest while fueling Capex from organic FCF
Spot ETFs turned Crypto into a sovereign debt hedge, not just retail beta
A deep dive into the macro architecture behind the current rally👇
One of the biggest smart-money trades of this cycle may be hiding in plain sight:
The U.S. government’s strategic investment portfolio.
We’ll track the money, you capture the opportunities.
The U.S. government may have made one of the best trades of the decade.
In 2025, it invested $8.9B in $INTC at $20.47/share.
Sep. 21 close: $121.78
That’s roughly:
+495% price appreciation
~$43.9B theoretical gain
But Intel wasn’t the only strategic investment.
I followed the government money.
Here’s where it went next 👇