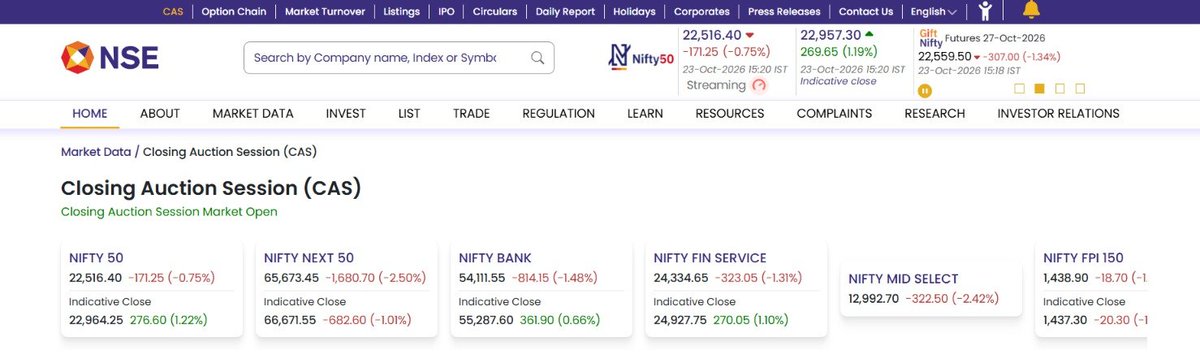
Nifty was down 170 pts in normal trading. CAS then showed at one point an indicative close up 277 pts.
That's almost a 450 pt difference.
Makes you wonder what exactly the market was doing for the previous six hours.
@Shijumonantony Request you to checkout my humble attempt at https://t.co/7ZMovswwUd . This is inline with your msg in chat group. Please share your valuable feedback !!
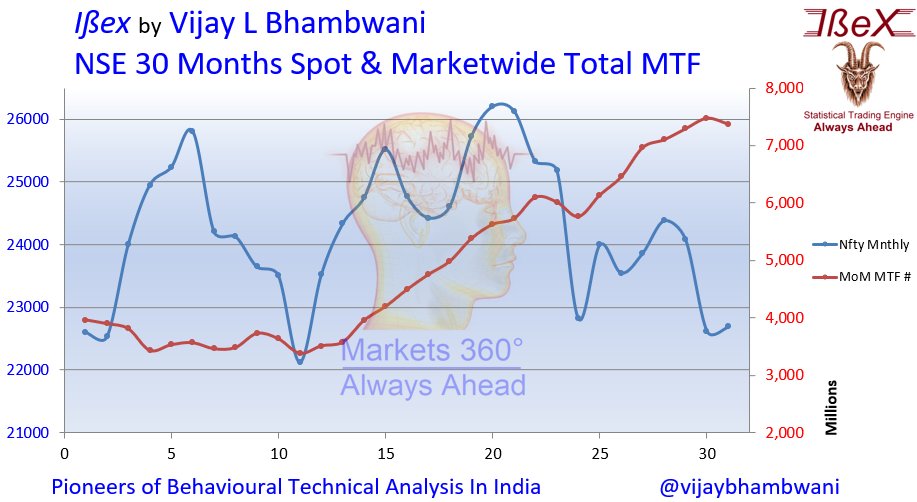
Over a year ago I started warning my @livemint & @moneycontrolcom readers of excess leverage building up. Unfortunately, late comers are focused on MTF alone. What about f&o, loan against securities, off-the-books funding? The total leverage is far bigger! Int rates are rising!
Be ahaead of the curve - signup for premarket intelligence platform to keep urself updated on latest development in markets . Free 7 day trial https://t.co/YKhAzCuDqF
Be ahaead of the curve - signup for premarket intelligence platform to keep urself updated on latest development in markets . Free 7 day trial https://t.co/YKhAzCuDqF
Be ahaead of the curve - signup for premarket intelligence platform to keep urself updated on latest development in markets . Free 7 day trial https://t.co/YKhAzCuDqF
Be ahaead of the curve - signup for premarket intelligence platform to keep urself updated on latest development in markets . Free 7 day trial https://t.co/YKhAzCuDqF
Be ahaead of the curve - signup for premarket intelligence platform to keep urself updated on latest development in markets . Free 7 day trial https://t.co/YKhAzCuDqF
@SarangSood "The Reserve Bank of India (RBI) has raised the minimum daily Cash Reserve Ratio (CRR) maintenance requirement for scheduled banks to 99% from the existing 90%, effective from the reporting fortnight beginning October 16, 2026."
Two years:
Korea: +160%
Taiwan: +110%
Nifty: -11%
Today Nifty another 1%+ lower.
Other Asian markets spent two years creating wealth while we spent two years discussing the growth story.
Sep 28 Daily brief
--------------------
📷 Bias: CAUTIOUS BEARISH
Nifty trades below its 5-day GIFT average near a bearish CPR, FIIs have sold a net ₹14,492 cr over five sessions, WTI crude is spiking on Iran-Hormuz tensions, and the US 10Y yield at 5.18% is compressing risk appetite — all on the eve of monthly F&O expiry.─────────────────
📷 Global Overnight Wall Street closed Friday on a constructive note — the S&P 500 gained +0.51% to 7,743, the Dow added +0.93% to 51,829, and the NASDAQ 100 rose +0.42% to 30,608. However, these are Friday's closing prints; Monday morning futures are reportedly slipping slightly (per CNBC's live update headline). The VIX collapsed -5.1% to 14.87, hitting a 5-session low and signalling complacency rather than outright calm — the streak of 5 consecutive daily declines in VIX is worth watching for a mean-reversion snap. Asia is presenting a mixed-to-negative picture this morning. KOSPI is down a sharp -2.44% to 6,908 — the standout laggard — while Shanghai Composite fell -1.74% to 3,820 (seventh consecutive negative session vs. its 5-day baseline). Hang Seng is a modest outlier, up +0.52%, likely buoyed by stimulus expectations as China's August industrial profit growth hit its weakest print of 2026 at just +4.2%. Nikkei is flat at -0.05%. The Trump-Xi summit headline provides diplomatic noise but markets want "tangible outcomes" before positioning on a US-China thaw. 📷 Currency & Commodities WTI crude surged +1.21% to $93.53/bbl — the key driver being Trump's rejection of Iran's Hormuz Strait reopening proposal. This is a direct inflationary headwind for India, which imports ~85% of its crude. A sustained move above $95 would materially pressure India's CAD and fiscal math. Gold dropped -1.90% to $4,239, snapping a 2-session recovery as the dollar firmed. The USD/INR is at 95.80, which is actually a positive surprise — the rupee has strengthened -0.37%, continuing a 4-session streak of appreciation. The DXY ticked up modestly to 101.09 but sits near the 93rd percentile of its 1-year range, limiting further INR upside. US 10Y yield rose to 5.184% (+2.2 bps), sustaining an elevated regime that keeps FII equity flows under pressure. Notably, the 5Y yield dipped -1.8 bps to 5.007%, narrowing the curve — a signal of near-term rate uncertainty.
📷 Indian Market Technicals GIFT Nifty is at 23,115, below Friday's cash close of 23,140 and well below the 5-day average of 23,199 — suggesting a soft open, approximately -25 to -30 points gap down. CPR for today: BC: 23,091 | PP: 23,108 | TC: 23,124 — a width of 32.44 pts (above the 5-day avg of 28.16, 6-session widening streak), pointing to a trending day, not a rangebound one. Direction of trend will be set by the first 15-minute candle relative to the CPR band. Key pivot levels: - Resistance: R1 23,195 → R2 23,250 → R3 23,337- Support: S1 23,053 → S2 22,966 → S3 22,912 The 23,000–23,050 zone is critical floor support; a close below it opens a fast move toward 22,966.
📷 FII/DII Positioning Friday's (Sep 25) institutional data is telling: FIIs net sold ₹3,694 cr in cash equities, extending their selling streak to 4 consecutive sessions with a massive cumulative 5-day net outflow of ₹14,492 cr. The 5-day average daily selling is -₹2,922 cr — Friday's print was above-average intensity. DIIs absorbed the blow, buying a net ₹2,838 cr — their 8th consecutive day of net buying. DII support is holding the market up but is being tested. This is a clear tug-of-war, and at these yield levels, FII pressure may persist.
📷 ADR Signals
Indian ADRs closed with modest green Friday: HDFC Bank (HDB) +0.79% to $23.01 is the leader and implies some buying interest in financials. Wipro (WIT) +0.61%. ICICI Bank (IBN) +0.14%. Infosys (INFY) flat at $10.50. ADRs are broadly constructive but not providing a strong enough signal to overcome the crude and yield headwinds. IT sector (INFY flat) may open tepid.
📷 Market Outlook & Strategy The dominant setup for today: expiry-eve volatility with a bearish tilt. Monthly F&O expiry is tomorrow (Sep 29). Max pain sits at 23,250 — currently ~110 points above spot — suggesting shorts may face short-covering pressure if the market dips toward 23,050–23,000. However, the PCR at 0.93 (rising from 0.82 average — put writers adding) and massive CE OI wall at 23,300–23,500 cap meaningful upside. The ATM straddle at just 0.84% implies a tight expected move, yet CPR warns of trending action — a contradiction worth respecting with tight stops. Strategy: Avoid aggressive directional bets at open. Watch the 23,100 CPR pivot — sustained trade above it opens a drift toward 23,195–23,250 (max pain magnet). A break below 23,050 (S1) with volume confirms the bearish setup targeting 22,966. Crude and US yields are the macro wildcards; any crude print above $95 intraday should be treated as a fresh sell signal for broader markets. Defensives and BFSI ADR-positive names (HDFC Bank) may relatively outperform. ─────────────────
Trader's note: With one day to monthly expiry, option writers control the narrative — respect the 23,000–23,300 range as the battlefield; breakouts beyond these levels will be sharp and fast, so keep positions sized for volatility, not just direction.
For free daily updates like this sign up to
https://t.co/blpMSrKmiZ