@P_Remarks $FOSL how about 300%+... Fogliato (former Saloman CEO) executing turnaround & return to growth plan. Core business flipping positive, IWM inclusion & massive catalyst with potential India IPO. Traditional watches capitalize on macro trends as Gen-Z and others ditch digital.
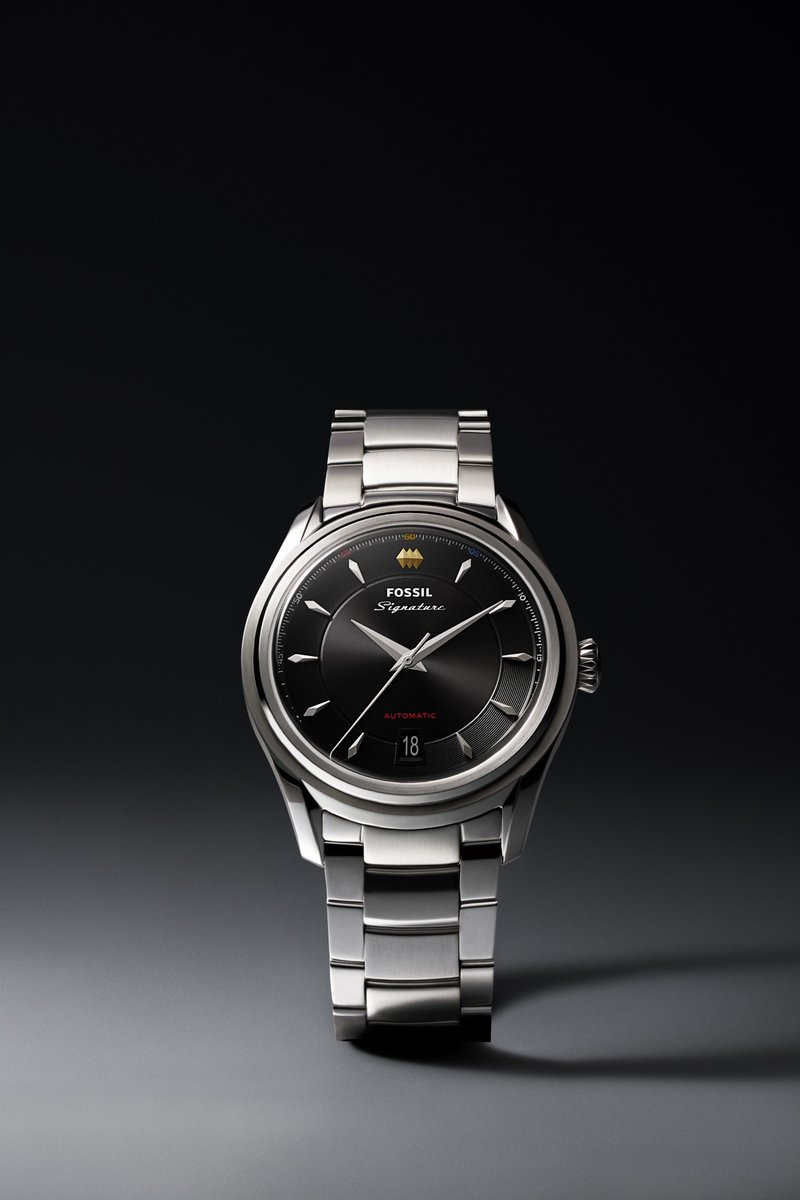
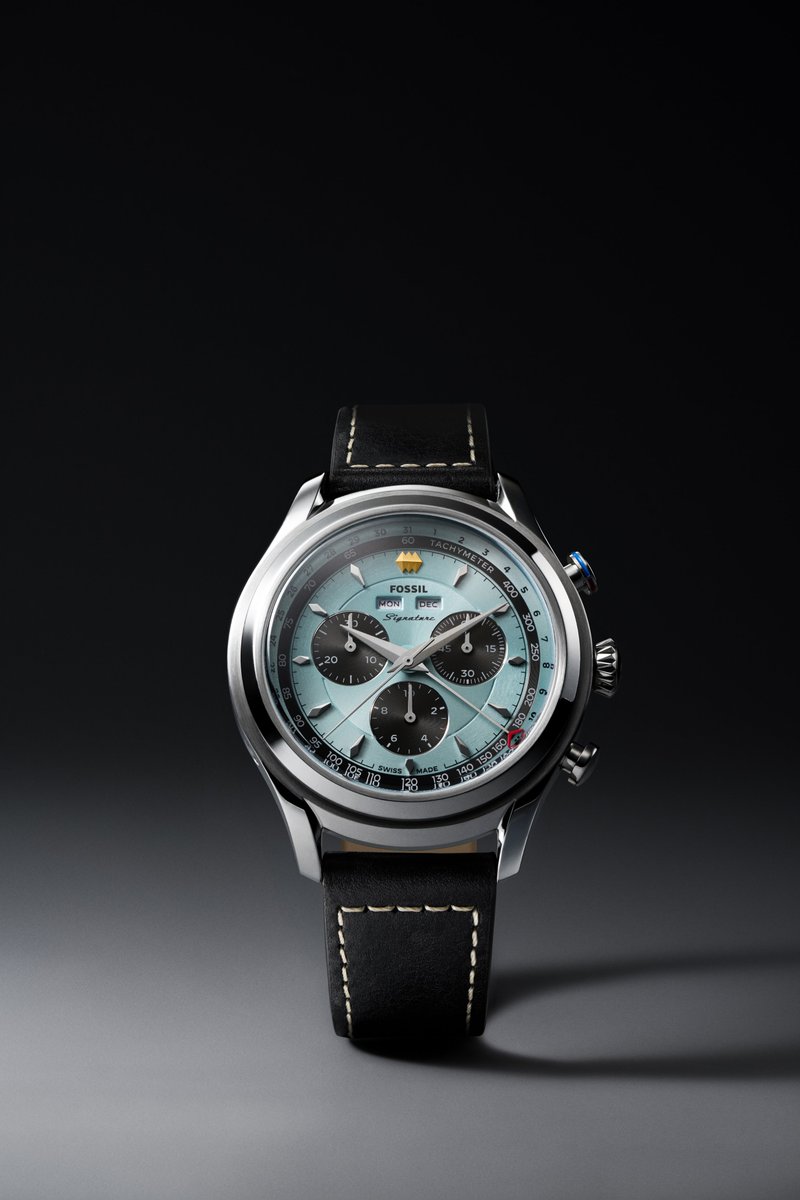
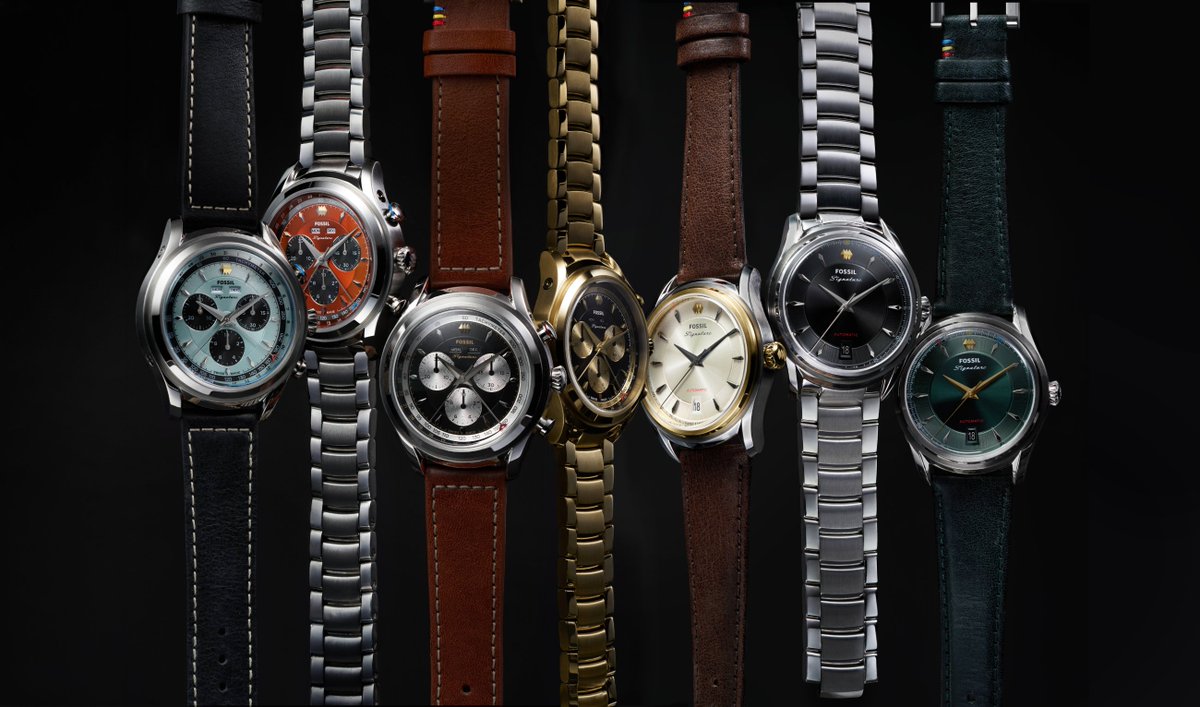
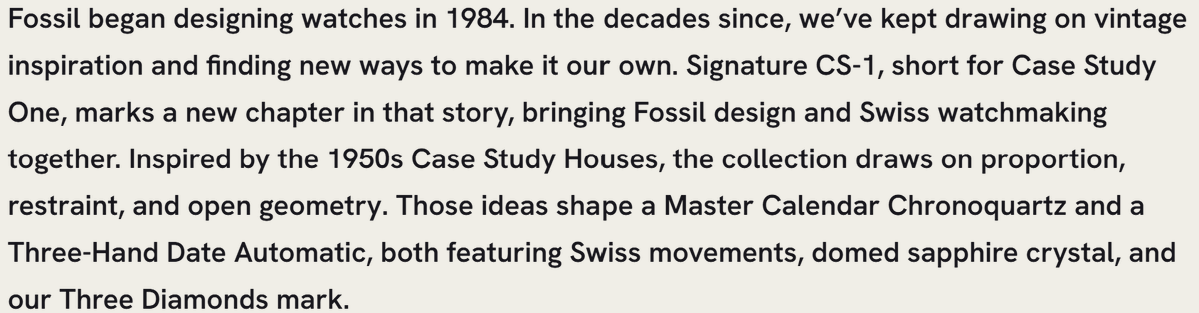
Fossil's new Swiss line, Signature CS-1, early preview on the Windup NYC exhibitor page. Swiss movements, domed sapphire, and a triple-calendar chrono. Vintage/MCM Case Study House-inspired design. Elevated quality & best-looking product they've made in years. $FOSL
@P_Remarks $FOSL traditional watches breaking out w/gen z, q4 rev growth inflecting pos & fy27 guide +msd = >$1.50 eps. stock to re-rate to $10+ & potential India ipo kicker. still time to hop in before it hits $16.
If you publicly assign a >10% probability to human extinction within a decade, you owe people a clear explanation of how you reached that number + what would change your mind.
I’m disappointed in all the fear-mongering.
This tech wave needs adult chaperones.
$FOSL Beat & Raise: $211M actual vs $199M
- Raised FY guide & expecting + FCF
- Gross Margins expanded by 490 bps & Q4 return to growth
- Traditional watches +12% wholesale and +16% in the US.
- India delivered strong double-digit growth
- Only 2 closures remain on the schedule for the rest of the year.
- Premiumization: Machine X1 is confirmed for the fall & new Swiss-made "Signature" platform debuting at NY Watch Week
$FOSL Q2 '26 Preview: Expect a top-line beat (Street $199M). Conservative mgmt. team (fmr Salomon CEO). Turnaround on track with FY guide - return to growth in Q4.
Key variables tonight:
• Core: Traditional watches remain the driver. Looking for sustained US/India momentum.
• Headline Noisy: Mix shift continues with strategic rationalization of store footprint & product categories with focus on traditional watches.
• Catalysts: Commentary on $300M India IPO. First premium line launching 2H (Machine X1 - sapphire crystal & Japanese movement) elevating the brand ($500 ASP).
@CorsicaInvestor@MikeFritzell FOSSIL, TIMEX, TITAN, MOVADO, CASIO - all outperforming. The market is mispricing the ongoing secular rotation out of wearable tech.
@P_Remarks $FOSL how about 300%+... Fogliato (former Saloman CEO) executing turnaround & return to growth plan. Core business flipping positive, IWM inclusion & massive catalyst with potential India IPO. Traditional watches capitalize on macro trends as Gen-Z and others ditch digital.
@CapitalOnValue Don’t forget the “planned outage” that impacts every quarter. If Long Ridge doesn’t close, investors won’t have to worry about being fooled again. They can look forward to deploying some capital tax losses when the equity gets wiped
everyone: "nobody is prepared for AI"
me: Nobody is prepared for the traditional watch supercycle. Multi-year breakout occurring and nobody is positioned for it ( $FOSL, $MOV, Casio, TIMEX, TITAN, etc.)
@sama The car is called the “traveling confessional” because our kids are more open to conversation while we drive. This is a well-known phenomenon and results in some of the most enjoyable discussions as a parent.
A series of fairly wild thoughts from Dwarkesh. I thought I was bullish but even I am not assuming that the price to rent compute continues to go up!
I will say that I am in SV this week and Dwarkesh is capturing the zeitgeist.
Net, net public markets would probably be trading differently if they saw the OpenAI, Anthropic, Grok/Cursor and Open Source numbers over the last 6 weeks.
And really good for anyone who has installed compute coming off contract and/or is bringing on compute that is not already contracted. And credit slowing down capacity adds - if it happens - only exacerbates all of this.
In Germany, a talented 14-year-old earns his club money. In America, his parents pay the club $15,000 a year.
That single inversion explains why "we will not" is the most accurate line ever written about US soccer.
FIFA built a global system for this. Training compensation and solidarity payments send a cut of every transfer fee back to the clubs that developed the player, from age 12 onward. Develop one future pro and your academy gets paid for a decade. Barcelona's La Masia, Ajax, every Bundesliga academy runs on this logic. The kid is the asset.
US Soccer refuses to enforce those rules. When Seattle's Crossfire Premier claimed its $60,000 share of DeAndre Yedlin's transfer to Tottenham, it got nothing. Claims on the Dempsey and Bradley transfers died partly because the federation couldn't even produce the youth training records.
So American clubs earn zero dollars when a kid turns pro. They earn when a kid enrolls. Which makes the parent the customer, and the product is whatever keeps the parent writing checks: travel tournaments, hotel weekends, $500 showcase events, private training at $100 an hour. Elite pathways run $8,000 to $20,000 a year. A comparable academy spot in Italy costs about 120 euros.
Follow the incentive one level deeper and it gets darker. A club dependent on fees can't cut its weakest paying players, so rosters optimize for retention over development. The scouting pool shrinks to families who can afford the cliff, which appears around age 11, exactly when development matters most. The country runs a talent filter sorted by household income instead of ability.
Every four years someone proposes fixing this. The proposal always requires the people profiting from the $15,000 model to vote themselves out of business.
They will not.