$DUOT ...egg on face today. I've gotten some interesting messages so figure I would add thoughts after going through AGPU's transcript.
1) Got a question of "why is it down so much?" I'll provide two items from my POV that warrant stock moving lower like it is. First is them delaying 10 MW hyperscaler deployment in GA cluster to 2Q27. If your pitch is deploying DCs quickly at smaller scale because you avoiding the delays bigger deployments face drives speed to market, and then you announce a multi-quarter delay - the stock should be punished. I've mentioned "say vs do" ratio on this and it is moving the wrong way. They should stop the "we rolled out 7MW in 75 days, we are great" because the next 10MW beyond that are taking 180+ days... not good for your value prop. Executing is hard, but stumbling here is not good. Second there isn't a financing update. Every day they don't have debt financing secured in this backdrop, things get harder. There is clear reflexivity. Then they hint at potentially looking to equity at some point... not helping.
2) Would not be shocked if the 55MW JV between DUOT/AGPU isn't happening after going through the AGPU call. It didn't even get brought up after being center of attention last call. If DUOT really has 100MW+ of demand from CSP's with the powered land under LOI, then substituting out the AGPU 55MW JV where they only have 51% economics with a higher credit quality, longer duration 20MW CSP cluster would be a good trade. This doesn't really matter in the current moment, but at some point it will. I am hopeful that if/when not pursuing the AGPU JV gets announced, it is directly accompanied with another 20MW CSP cluster deployment announcement.
3) What is this actually worth? Current book value covers the entire 20MW Columbus GA cluster value ( just needs to be powered up), some deposits on land in 100MW pipeline, ~$43mm owed to them by AGPU, and ~$10mm in escrow from the APR deal that should pay in May 2027. Question here becomes what value we should place on the 20MW CSP cluster in the Carolinas, how to value the 100MW pipeline, and how to adjust for the execution and dilution risk.
$DUOT - Some updates on the 3Q call since they spoke at LD Micro ~4 weeks ago. Mix of positives, negatives, and generally interesting details in the call and 10Q. They answered the main questions I think most people that follow this had.
Again, this all comes down to is project funding and execution. Simple doesn't equal easy. Stock is trading below book value and there is 0 value being assigned to the 20MW CSP deal, 55MW AGPU JV, or 100MW land pipeline.
Positives
- Gave important clarification on unit economics/payback. Capex ~$6.5mm/MW, annual revenue ~$2mm-$2.5mm/MW, and annual site-level EBITDA of ~$1.5mm/MW. Implies ~23% return on an EBITDA/Capex basis which also ties with a <5 year payback period. This is a very solid return in absolute and should provide adequate margin of safety in a higher cost of funding environment.
- Sounds like funding in the works for the 20MW CSP site and future sites. "For the 20 MW cloud deployment and our next sites, we’re in active discussions with several potential lenders and capital providers at both the project and corporate level, and we’ll update the market as agreements are finalized."
- 7MW became fully operational in Columbus in beginning of October so should get full quarter of revenue from that in 4Q.
- Developing additional GA site that could go live 1Q27. Guessing this is the 4MW neocloud deployment they mentioned at LD Micro.
- Site for the 20MW CSP already secured and in development phase. They said it could be delivered at or before ready for service date. Per the 10Q, as of 10/5 they put the remaining ~$9mm of ~$10mm purchase price in escrow for the site in Lee County (I believe South Carolina), subject to closing conditions around getting ~20MW of power.
- Majority of remaining 75MW of the 100MW pipeline in negotiation already has deposits down. Imagine we get a few more announcements over the next 6 months.
Negatives
- 10MW hyperscaler deployment in Columbus is delayed because of an issue with Georgia Power. All of the DUOT equipment is there, it's a power delivery issue with GP. Doug saying they have a solution (BTM I am guessing?) that gets this up and running in 2Q27. Operating is hard, but you cannot have delays at this scale of deployment. Thankfully they were able to pay for this site 50% on an earnout basis so cash not wasted on power not secured.
- I thought they could lever up the Columbus site and take proceeds from that raise to fund other projects into early 27. Now that prob can't happen until late 27.
- No update on the 55MW AGPU JV deployment. Not sure if they are waiting for AGPU to discuss more tomorrow morning, but this is not encouraging for the timing.
- No update/comment on 0Lat expiration.
- I think odds are higher than before that equity-like securities could be used for some funding per commentary on the call. I get that in a spreadsheet it will show as "accretive" but common equity should be quite literally the LAST option chosen with stock sub book value.
Other Stuff
- Calling the 20MW CSP deployment "Project Atlas" per the 10Q. Bought the land in Lee County (I think in SC) from a "CTS Infrastructure LLC" for ~$10mm.
- Per the 10Q, Alyeska exercised warrants for 1.5mm shares on 10/21/26. The 9/30 13G showed common shares of 1.4mm and 3.8mm of warrants. The 6/30 13G had common shares 2.0mm and 3.8mm of warrants. Didn't sell as much as I thought in the 6/30-9/30 period, but potentially ramped up selling since 10/21 if they are exercising 1.5mm warrants (based on the 4.99% threshold they are staying under here).
- Hydra Host fully out of the picture per the 10Q.
Not sure if it is exactly Aethir flipping it to a hyperscaler. That wasn't my understanding but if you have specifics showing that, would be helpful to see.
My understanding with Meta 1 (Aethir) is that DUOT is providing "site identification, risk assessment and conceptual design services for future compute center locations." per the 10Q which makes me think that they aren't actually deploying anymore DCs for AGPU. Just doing other work that they are being paid for.
$DUOT - Some updates on the 3Q call since they spoke at LD Micro ~4 weeks ago. Mix of positives, negatives, and generally interesting details in the call and 10Q. They answered the main questions I think most people that follow this had.
Again, this all comes down to is project funding and execution. Simple doesn't equal easy. Stock is trading below book value and there is 0 value being assigned to the 20MW CSP deal, 55MW AGPU JV, or 100MW land pipeline.
Positives
- Gave important clarification on unit economics/payback. Capex ~$6.5mm/MW, annual revenue ~$2mm-$2.5mm/MW, and annual site-level EBITDA of ~$1.5mm/MW. Implies ~23% return on an EBITDA/Capex basis which also ties with a <5 year payback period. This is a very solid return in absolute and should provide adequate margin of safety in a higher cost of funding environment.
- Sounds like funding in the works for the 20MW CSP site and future sites. "For the 20 MW cloud deployment and our next sites, we’re in active discussions with several potential lenders and capital providers at both the project and corporate level, and we’ll update the market as agreements are finalized."
- 7MW became fully operational in Columbus in beginning of October so should get full quarter of revenue from that in 4Q.
- Developing additional GA site that could go live 1Q27. Guessing this is the 4MW neocloud deployment they mentioned at LD Micro.
- Site for the 20MW CSP already secured and in development phase. They said it could be delivered at or before ready for service date. Per the 10Q, as of 10/5 they put the remaining ~$9mm of ~$10mm purchase price in escrow for the site in Lee County (I believe South Carolina), subject to closing conditions around getting ~20MW of power.
- Majority of remaining 75MW of the 100MW pipeline in negotiation already has deposits down. Imagine we get a few more announcements over the next 6 months.
Negatives
- 10MW hyperscaler deployment in Columbus is delayed because of an issue with Georgia Power. All of the DUOT equipment is there, it's a power delivery issue with GP. Doug saying they have a solution (BTM I am guessing?) that gets this up and running in 2Q27. Operating is hard, but you cannot have delays at this scale of deployment. Thankfully they were able to pay for this site 50% on an earnout basis so cash not wasted on power not secured.
- I thought they could lever up the Columbus site and take proceeds from that raise to fund other projects into early 27. Now that prob can't happen until late 27.
- No update on the 55MW AGPU JV deployment. Not sure if they are waiting for AGPU to discuss more tomorrow morning, but this is not encouraging for the timing.
- No update/comment on 0Lat expiration.
- I think odds are higher than before that equity-like securities could be used for some funding per commentary on the call. I get that in a spreadsheet it will show as "accretive" but common equity should be quite literally the LAST option chosen with stock sub book value.
Other Stuff
- Calling the 20MW CSP deployment "Project Atlas" per the 10Q. Bought the land in Lee County (I think in SC) from a "CTS Infrastructure LLC" for ~$10mm.
- Per the 10Q, Alyeska exercised warrants for 1.5mm shares on 10/21/26. The 9/30 13G showed common shares of 1.4mm and 3.8mm of warrants. The 6/30 13G had common shares 2.0mm and 3.8mm of warrants. Didn't sell as much as I thought in the 6/30-9/30 period, but potentially ramped up selling since 10/21 if they are exercising 1.5mm warrants (based on the 4.99% threshold they are staying under here).
- Hydra Host fully out of the picture per the 10Q.
$DUOT set to report earnings on Monday. If I was running the IR effort, below is what I would tell CEO/CFO to spend significant time on in prepared remarks. Frankly, the "say vs. do" ratio here has moved in the wrong direction. No need for fluff or cheerleading, just give facts/details and clarity on the important issues.
1. Financing/Balance Sheet: This is the most important item. How does the business get financed moving forward. Just using their $/MW capex guidance, the 20MW Columbus cluster is built entirely from cash on the balance sheet. The real question is, how do they fund the rest? If you cannot fund the growth as a standalone entity, the rest literally doesn't matter. Just go sell the in-place assets and secured pipeline to the highest bidding DC operator and call it a day. Someone that can raise capital at a more attractive rate to fund your projects will make multiples of invested capital....Questions to answer: How has selling GPUaaS biz to AGPU changed your financing discussions with lenders? Will you put debt on the Columbus cluster when it is finished? If so how much and at what cost of capital? What is final funding status of AGPU 55MW cluster (type of financing and what cost)? How are you financing the 100MW land pipeline? Are you looking at any equity-like structures to fund future growth? Are you trying to do longer-term funding partnerships iwth larger DC players or PE/PC/infra funds?
2. Unit Economics: They caused a lot of confusion in my mind on this one and really offered no explanation at LD Micro why the numbers are so different from the Feb 26 unit economics. Maybe some of this is a switch in definitions, but you cannot put out unit economics slides with such a big change and give no color why. Questions to answer: What ROI/unit economics should an investor model on a project? What is the difference between the ~$1.5mm/MW contribution margin from Feb 26 deck and the ~$1.0mm/MW site EBITDA in the Oct 26 deck? Is there corporate cost or something else in the new number than change the comparison? You fumbled answering the payback question (3yr stated vs 6yr implied in slide) at LD Micro, can you give us a clear answer to what this should actually be? What makes a cluster have better/worse profitability and in your current road map how wide is the differential?
3. Current Project Status Updates: Listing these in order of importance for this specific call IMO.
- Columbus, GA Cluster: At LD Micro said they have 7MW live and billing. This is the first active cluster so they should spend time updating us on it. Questions to answer: When did this officially start billing and at how many MW? How many MW are currently active/billing? When will it be fully active/billing? When does 10MW for hyperscaler commence? How does rev/EBITDA profile change after selling GPUs to AGPU?
- AGPU 55MW Deployment: We haven't heard much on this intra-quarter so I would expect meaningful time is spent here. Questions to answer: Are powered sites secured for both clusters that comprise this? What is updated timeline (prev. 4Q26/1Q27)? What is the finalized JV structure and how is it being funded? Are unit economics different than average, if so why?
- Expiration of LOI with 0Lat: Thankfully this really isn’t a material revenue driver, but clearly they didn’t execute this per their LinkedIn posts. Questions to answer: What happened here that co now advertising the 12 Texas pods as available? What terms was co looking for and why didn’t co get them? How will co redeploy these? Why did co build these on spec and burn shareholder $?
- 20MW CSP Deal: Relatively new so I am guessing not much to add here from them and that's why it is lower on my list for addressing on earnings call. Questions to answer: Is powered land secured for this? Is CSP providing pre-payment or investment in the project? Do you already have financing secured? Are unit economics different than average and if so why?
4. 100MW Land Pipeline Update: Announced in late October, and noted all of the land is DC-zoned. Questions to answer: How much of this is under contract now? How much is for announced vs. unannounced deployments? How are you buying this and are they all structured as options or outright land purchases upfront?
@jdm_trades I think showing they can get debt financing for the 20MW CSP deal is the key. Otherwise they need to just execute the buildouts. I think it’s that simple, but “say vs. do” ratio here is trending wrong way.
$DUOT set to report earnings on Monday. If I was running the IR effort, below is what I would tell CEO/CFO to spend significant time on in prepared remarks. Frankly, the "say vs. do" ratio here has moved in the wrong direction. No need for fluff or cheerleading, just give facts/details and clarity on the important issues.
1. Financing/Balance Sheet: This is the most important item. How does the business get financed moving forward. Just using their $/MW capex guidance, the 20MW Columbus cluster is built entirely from cash on the balance sheet. The real question is, how do they fund the rest? If you cannot fund the growth as a standalone entity, the rest literally doesn't matter. Just go sell the in-place assets and secured pipeline to the highest bidding DC operator and call it a day. Someone that can raise capital at a more attractive rate to fund your projects will make multiples of invested capital....Questions to answer: How has selling GPUaaS biz to AGPU changed your financing discussions with lenders? Will you put debt on the Columbus cluster when it is finished? If so how much and at what cost of capital? What is final funding status of AGPU 55MW cluster (type of financing and what cost)? How are you financing the 100MW land pipeline? Are you looking at any equity-like structures to fund future growth? Are you trying to do longer-term funding partnerships iwth larger DC players or PE/PC/infra funds?
2. Unit Economics: They caused a lot of confusion in my mind on this one and really offered no explanation at LD Micro why the numbers are so different from the Feb 26 unit economics. Maybe some of this is a switch in definitions, but you cannot put out unit economics slides with such a big change and give no color why. Questions to answer: What ROI/unit economics should an investor model on a project? What is the difference between the ~$1.5mm/MW contribution margin from Feb 26 deck and the ~$1.0mm/MW site EBITDA in the Oct 26 deck? Is there corporate cost or something else in the new number than change the comparison? You fumbled answering the payback question (3yr stated vs 6yr implied in slide) at LD Micro, can you give us a clear answer to what this should actually be? What makes a cluster have better/worse profitability and in your current road map how wide is the differential?
3. Current Project Status Updates: Listing these in order of importance for this specific call IMO.
- Columbus, GA Cluster: At LD Micro said they have 7MW live and billing. This is the first active cluster so they should spend time updating us on it. Questions to answer: When did this officially start billing and at how many MW? How many MW are currently active/billing? When will it be fully active/billing? When does 10MW for hyperscaler commence? How does rev/EBITDA profile change after selling GPUs to AGPU?
- AGPU 55MW Deployment: We haven't heard much on this intra-quarter so I would expect meaningful time is spent here. Questions to answer: Are powered sites secured for both clusters that comprise this? What is updated timeline (prev. 4Q26/1Q27)? What is the finalized JV structure and how is it being funded? Are unit economics different than average, if so why?
- Expiration of LOI with 0Lat: Thankfully this really isn’t a material revenue driver, but clearly they didn’t execute this per their LinkedIn posts. Questions to answer: What happened here that co now advertising the 12 Texas pods as available? What terms was co looking for and why didn’t co get them? How will co redeploy these? Why did co build these on spec and burn shareholder $?
- 20MW CSP Deal: Relatively new so I am guessing not much to add here from them and that's why it is lower on my list for addressing on earnings call. Questions to answer: Is powered land secured for this? Is CSP providing pre-payment or investment in the project? Do you already have financing secured? Are unit economics different than average and if so why?
4. 100MW Land Pipeline Update: Announced in late October, and noted all of the land is DC-zoned. Questions to answer: How much of this is under contract now? How much is for announced vs. unannounced deployments? How are you buying this and are they all structured as options or outright land purchases upfront?
$DUOT basically in the process of doing this already, targeting sub-30MW sites across the country. Focus on building smaller with less community disruption. Cluster in Columbus, GA is live. More to come across Carolinas, Iowa, Oregon, Texas, and more (securing 100MW of data centers-zoned land) . Should win as focus moves to smaller clusters, with CEO that has built them before. Only question is access to capital. Demand clearly exists beyond initial customers. Earnings coming next few weeks.
Exclusive: Nvidia has submitted a proposal to Brightspeed, an Apollo-owned broadband provider reportedly nearing bankruptcy, to convert some of its 130-plus telecom buildings into AI data centers.
Nvidia estimates the sites have roughly 1 gigawatt of available power, potentially enough to run tens of billions of dollars of Vera Rubin chip systems.
Read more: https://t.co/6fFBdcrIT9
$DUOT - LD Micro pres provided some interesting news/insights. Good time to update priors esp with the pullback. Will walk through takeaways (both positive and negative).
TLDR: business outlook improving with longer-dated, better counterparty contracts (20MW CSP deal for 2Q27 deployment signed). High visibility into securing another 100MW of capacity to deploy for publicly traded CSP’s and hyperscalers. Georgia AI cluster already partially running/generating revenue. Proving ability to deploy MW for AI DC’s at fast pace. Stock trading at a discount to tangible book value(!!), no upside baked in for future deployments. The big question is getting debt financing, and at what rate. Getting financing is the unlock for the stock IMO, along with continuing to book these 10 year leases with large public companies
Positives
- 10yr 20MW deal with a mature publicly traded cloud service provider for >$400mm is a great step. 10yr term is a nice upgrade from 5yr, and the CSP customer is a material step up beyond AGPU. Could be one of the hyperscalers, but more likely AKAM, IBM, ORCL, etc. just based on not calling it a hyperscaler. FWIW they called the contract value ~$450mm-$460mm in the Q&A. More of these would be highly preferred over more AGPU biz. More diverse tenant base makes a more attractive biz/takeout target.
- Columbus GA cluster is live and revenue generating. they said 7 MW is live and billing right now. Based on disclosure in the new deck, we should see hosting revs from this flow through in 3Q. Proof of execution will show up in PnL when they report in November.
- Doug said they just signed a 4MW contract deploying in Roberta, Georgia with a "well backed neocloud" customer. That seems like a new announcement to me.
- Under contract/in active negotiations for 100MW of additional powered, data center-zoned land across multiple US sites. Of that, ~25MW is currently under contract across multiple sites in the US, and DUOT is in active negotiations on an additional 75 MW. Expects to finalize all site agreements by year-end. Should have a solid deployment road map after these deals are signed.
- They are very focused on raising debt at the project level instead of issuing equity going forward. Longer duration contracts with strong counter parties should help that. Saying 50-70% LTV is how to think about the raise but most debt now is all based on customer contract. Using rough math of ~$120mm cost for Columbus, could mean ~$60mm of capital raised via debt to use as equity in future projects (probably AGPU JV). Even at 12.5% rate and 5yr amort, the site cash flow could cover the debt service. Interested to see if they try to raise debt on the 20MW CSP ahead of deployment to fund construction.
Questions/Concerns
- Doug says Technology Solutions business has done ~$30mm YTD. Business did ~$3.8mm through 1H26. Did they really do ~$26mm of sales here in 3Q, or is he talking about the backlog #? Is this all flowing through in 2026?
- Doug says margin in Technology Solutions is 12-15%. is that an EBITDA margin figure? Business did ~23% gross margin in 1H26
- What ROI/unit economics should we be modeling to? Previous HPC colo example had 75% "contribution margin" that included operating expenses of ~$1.5mm/MW. The new slides imply ~45% site EBITDA margin with ~$1mm/MW. What is driving such a big delta here? This is one of the most important things, and they really aren't being clear on it.
- The new unit economics slide says 3 year payback period, but the ~$1mm/MW EBITDA would imply 6 year payback period. They clarify in Q&A saying the bigger deployments have a longer payback but the small 4MW ones are 3 years. One has extremely good returns, one is just in line with the average powered shell provider. What drives them to accept longer payback period?
- Of this 100MW of land under negotiation, how much is for unannounced deployments vs. matching announced deployments with land?
I agree that there is a difference between constructing/operating a data center for traditional CPU and enterprise servers compared to a GPU-focused data center with higher density AI servers.
However, I would argue the bigger difference is for the company that actually owns/operates the servers and chips.
For the Colo provider like DUOT, you need to build with higher power distribution requirements, more cooling capacity/infra needed. Doug has spoken about these differences and how DUOT addresses them. They are using DDC/Daikan to address some of the cooling aspects.
If you are the actual owner/operator of the GPUs/servers then it is much more of a step change in requirements for operating and deploying.
I’m not saying it isn’t different or harder, but I think you may be over-emphasizing just how much more difficult it is from a Colo perspective. Some of this is that it is simply more expensive, but you also charge for that in lease rates.
A lot of this gets solved from a stock perspective when these clusters come on line. Given the potential upside vs what market is baking in, I’m fine waiting for that to show up.
I’ve laid out the high level thesis on $DUOT in the quoted post. ~$300mm mkt cap AI colocation operator run by an industry veteran, access to powered land, 90-120 day deployment timeframes for 5-30MW clusters, strong unit economics, low maintenance capex, contracts with hyperscalers and smaller neoclouds, clean balance sheet, and EBITDA set to grow from ~$5mm this year to ~$40mm in 2027 and at least ~$80mm in 2028. If you have any duration and can stomach share price volatility, this is a small cap data center business worth owning.
The market panic presents a great opportunity to step back to 1) review the underlying DUOT assets/valuation, and 2) explore why DUOT is a prime acquisition candidate.
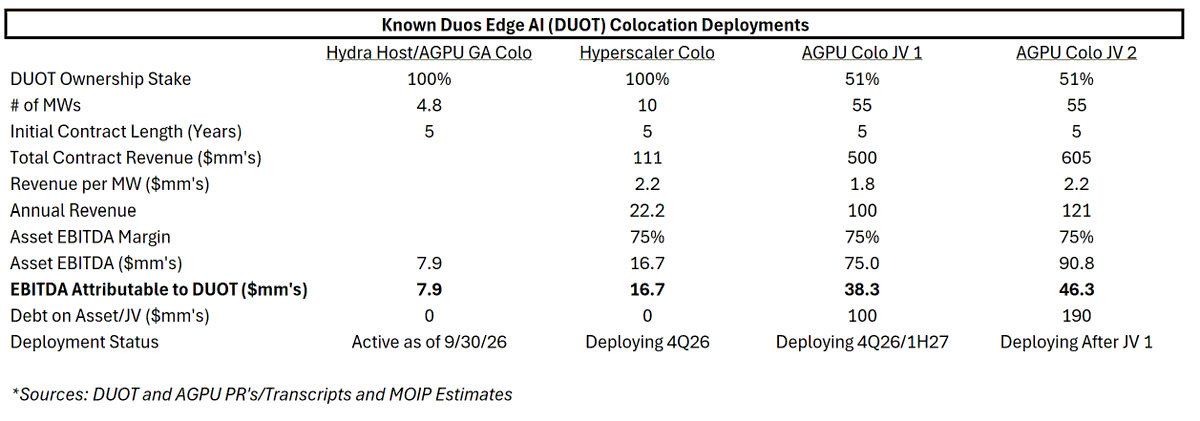
Given the nature of the business, we can evaluate each of DUOT's deployments individually (table with more detail in photos). These are just clusters we are publicly aware of, and with a 90-120 day deployment time there are likely more in the pipeline that aren't announced/can still be deployed for 2027/28. 2027 Guidance doesn't even include one of the deployments I discuss (!), but the opportunity has been disclosed by the customer (AGPU) at a conference.
4.8MW Hydra Host/AGPU Colo in GA
DUOT Ownership: 100%
Initial Lease Length: 5 Years
Annual Asset EBITDA: ~$7.9mm (4.8MW x $2.2/MW x 75% margin)
Debt on Asset: $0
Status: Active as of 9/30/26
Other Comments: DUOT recently sold the GPU's in this cluster to AGPU and is due ~$43mm cash in 12 months. They will still be customer facing and lease the GPUs from AGPU. My estimate on the MW figure. Revenue accounting on this may be a little funky, so just solving for the EBITDA based on disclosed unit economics.
10MW Hyperscaler Colo
DUOT Ownership: 100%
Initial Lease Length: 5 Years
Lease Contract Revenue: ~$111mm
Annual Asset EBITDA: ~$16.7mm (~$22mm x 75% margin)
Debt on Asset: $0
Status: Coming online in 4Q26
Other Comments: IG hyperscaler customer, also located in Columbus, GA. Disclosed in June 2026
55MW AGPU Colo JV 1
DUOT Ownership: 51%
Initial Lease Length: 5 Years
Lease Contract Revenue: >$500mm
Annual Asset EBITDA: ~$38.3mm (~$100mm x 75% margin x 51% ownership)
Total JV Debt: ~$100mm (est.)
Status: Deploying in 4Q26/1H27
Other Comments: AGPU investing ~$140mm of cash for its 49% JV stake. AGPU already has customer prepayments for the deployment. DUOT CEO flagging deployment costs are tracking below the ~$6mm/MW planned level, no DUOT equity investment required.
55MW AGPU Colo JV 2
DUOT Ownership: 51%
Initial Lease Length: 5 Years
Total JV Debt: ~$190mm (est.)
Annual Contribution Profit: ~$46.3mm (55MW x $2.2/MW x 75% margin x 51%)
Status: Comes after first 55MW deployment
Other Comments: Disclosed per AGPU CEO at the Moody Capital conference. Assuming similar JV structure though more debt required (assuming ~$6mm/MW build cost)
Total Company EBITDA and Valuation
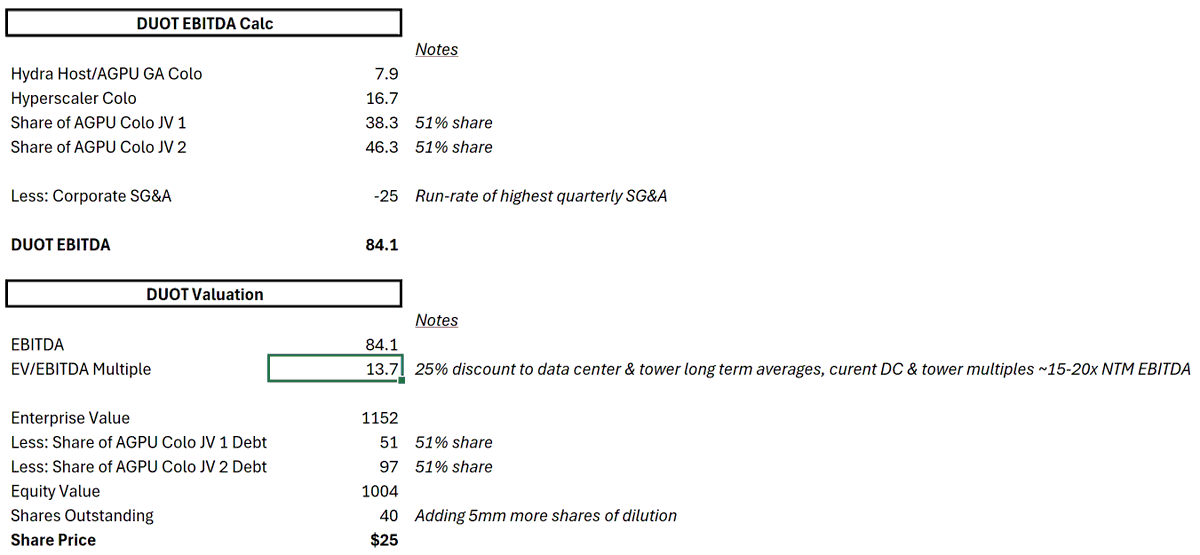
Putting this all together, we get ~$109mm of EBITDA net attributable to DUOT at the asset level. Factoring in ~$25mm of corporate SG&A gets us to ~$84mm of EBITDA at full deployment of these 4 clusters.
I use 13.7x EV/EBITDA to value the biz which is a 25% discount to the LT average of data center and tower operators. This would imply EV of ~$1.15bn. The comps currently trade at 20x EBITDA, and I think DUOT could get acquired for even more than this.
Subtract ~$150mm of JV debt attributable to DUOT, we reach ~$1bn of equity value. Assuming 40mm shares outstanding, we reach a $25/share price. At a 20x multiple valuation is ~$38/share.
Note, I don’t assign a value to the technology solutions/distribution business but I believe it is a key factor to DUOT being able to deploy clusters in a 90-120 day time frame.
Why DUOT is an Interesting M&A Target
1) Re-lease opportunity. DUOT is leasing its colo assets at ~$2mm/MW per year on average. On AKAM's update call on their Anthropic deployment, the CFO noted models should assume colocation costs of ~$3-4mm/MW. An acquirer has the ability to re-negotiate the DUOT leases at a meaningfully higher rate closer to current market levels. At the low end this is 50% higher leasing revenue for the DUOT assets.
2) Cost of capital. Executing on the announced pipeline will be done at a more accretive manner than if DUOT kept going at it alone.
3) Large SG&A synergies. I think 75% of the ~$25mm of SG&A can be cut by a larger buyer with scale.
4) Getting Doug Recker on your team. Doug has built/operated/sold two data center businesses already. The amount of change he has driven at DUOT in 2 years requires strong operational prowess and industry know-how. He's also been key to finding these 10-30MW latent powered land opportunities. Having him as an advisor (or just not competing against you) is a plus.
$DUOT - AI data center colocation operator. Specialize in finding attractive sites/infra/power and deploying 10-30MW edge data center clusters at these sites in ~90 days. They do not own the GPU’s - this closer to a traditional Colo data center biz model.
Fully diluted market cap of ~$325mm with no debt. Targeting ~25MW of deployed capacity at YE26, >65MW in pipeline that will be fully deployed in 2027. Current contracts are 5 year terms with built in extension options. Already has a hyperscaler customer for 10MW and deploying 55MW for $AGPU in a 51/49 JV (which AGPU is funding and DUOT is operating). Potential for another 55MW upsizing from AGPU. Targeting >$50mm of revs and positive EBITDA this year. Targeting ~$170mm of revs in 2027 (fully consolidating the AGPU JV). DUOT operating model targets ~$2.2mm/MW of revenue with ~75% contribution margins. Cost to deploy a MW is ~$6mm (~28% ROIC) and management saying all in cluster cost coming in lower. I estimate EBITDA attributable to DUOT in 2027 ~$40mm-$50mm.
Most of the big Colo players ($EQIX and $DLR) trade at >20x NTM EBITDA with slower growth. DUOT filling a niche in the market (fast deployment of smaller clusters) and serving a growing AI inference compute need.
Main risks are customer concentration, deployment issues, and further dilution (they are saying no more equity but we will see).
I’ve given more thoughts (both positive and negative) over the last few months in my posts and replies.
Owning/operating actual GPU's is a far more capital intensive business and not what DUOT wants to do. They have and advantage/skillset on the colo side. Let other players take the BS risk to fund the GPU roll outs. They will still be making money on this via the colo. Also, the capital deployed is FAR lower, which means the required profit to make good return is also lower.
@970nWDva74YTuQI Yep, you should underwrite AGPU to the extent you would like to. The prepayments, high level customer commentary, and other research make me feel good about their abilities to pay and operate the GPUs. I am comfortable underwriting this.
Where do you get 75% on all projects?
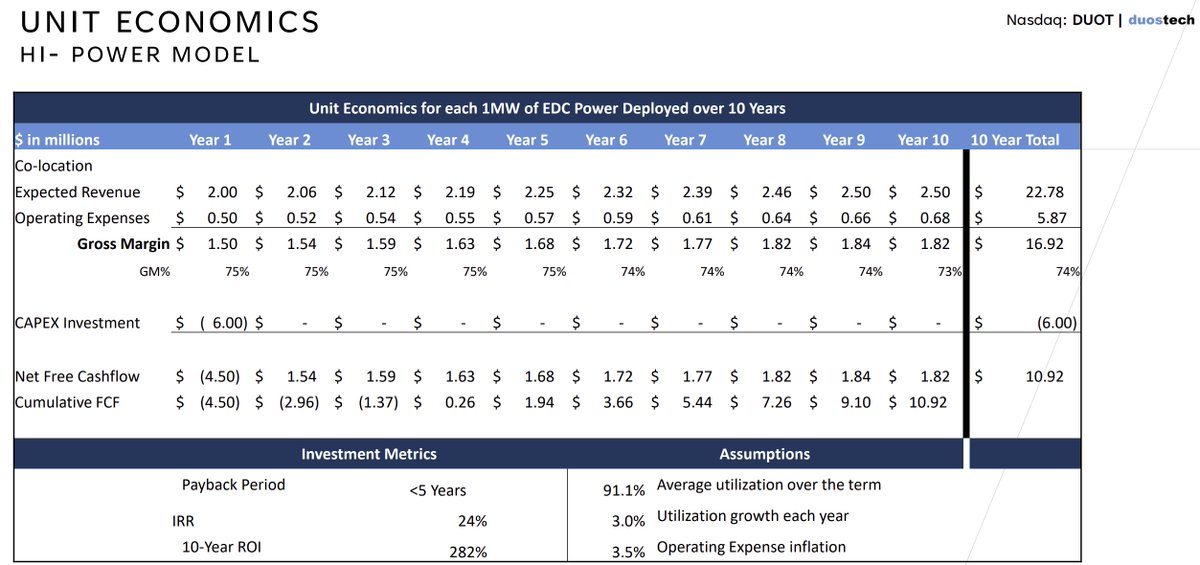
Slide 15 of their deck shows the high powered EDC unit economics. They use 75%. See the screenshot I include.
I call it asset-level EBITDA but they refer to it as a gross margin. In reality it is revenue less cash operating expenses – a cash profit number. If someone was to buy the asset and not the corporation, this would be the EBITDA they are earning. If you read my valuation math, I do subtract all of the corporate SG&A out to get the corporate EBITDA for DUOT. I value the stock off of the fully loaded EBITDA number. Yes the fully loaded corporate EBITDA margin figure for most of these is not 75%, and it isn't in my DUOT figures in the original post.
Other Colo players don’t even earn 60% margin
I’m not going through every public colo player for you, but as an example look at the most recent deck from EQIX Slide 15. Their stabilized data center profitability shows 70% cash gross margin. This is, to my understanding, very comparable to the figure I reference above and in my work. Let me know what colo's you are using and what figured you are using. See in the screen shot. If you want to take down my 75% to 70%, go for it. There is still meaningful upside ahead. Though I would flag EQIX is operating in higher cost metro markets with likely higher level costs than in the locations DUOT is deploying in.
Axe Georgia site has extra costs so aren't margins lower
I 100% agree with you on this. It definitely will have lower margin % as they are leasing compute and have to pass it through to the customer. The margins on this cluster will be lower than every other asset, but the actual $ profit figure will be similar to what they would be for a normal colocation deal on a MW basis. Go back to my original post where I note “Revenue accounting on this may be a little funky, so just solving for the EBITDA based on disclosed unit economics.” They inevitably will have a compute pass through which probably makes margins optically lower. Also look at my screen shot where I don’t have a revenue or margin number for the Hydra Host/Axe cluster that was just purchased. My math for the EBITDA at this cluster is just based on what $ profit they would earn on a normal colo project for 4.8MW. That is the math.
DUOT has not, that is correct. They pivoted to this business upon Doug joining in 2024.
However, Doug actually has built/operated this size at Colo5/Cologix. Your assertion that he has not, based on publicly available information, is incorrect. Let’s go through the facts…
From 2009-2014, Doug Recker was the Founder/CEO of Colo5. At Colo5, Doug built, retrofitted, and operated 2 data centers in Florida: one in Lakeland and one in Jacksonville. Doug sold this business to Cologix in 2014. Doug then became the VP/GM of Florida for Cologix from 2014-2017.
The power specs on these two specific data centers:
Lakeland (Currently LAK1 under Cologix): 12MW as retrofitted/built under Colo5
Source: https://t.co/vFRq5RBoEt
Jacksonville (Currently JAX2 under Cologix): 3.75MW as built under Colo5, then immediately post acquisition they added ~4MW of capacity which Doug was involved in. Currently listed as 7.5MW of capacity.
Doug noted in November 2014: “They comprehensively planned for this upgrade during the acquisition and hit the ground running immediately after we closed. This power expansion will allow our current and prospective customers to scale their IT infrastructure in this site predictably, well into the future.”
Source on size: https://t.co/tn49OCnvWG
Source on Doug’s comments: https://t.co/le3woNdnKc
After joining Cologix in late 2014, he also oversaw the existing Jacksonville facility (JAX1) that Cologix had which begun expansion to ~5MW in 2014 after Doug joined Cologix.
Source on size of JAX1: https://t.co/7mF7bS3NCS
Added all of these together and that gets you ~25MW of capacity between 3 separate DCs, with one of these facilities alone being >10MW. What led you to conclude that Doug has not built or operated data centers >10MW? Curious to know what I am missing!
EdgePresence, the business he founded after leaving Cologix, was more focused on smaller scale pods that are placed in the “far edge” and at telecom/cell towers. Still had a modular focus.
You're right, there hasn't been. But why would AGPU take the risk of buying the GPUaaS asset if this isn't going to generate revenue or work? Also, read about the season-and-sell model that https://t.co/7zHaAIGBWq used - it would imply that the facility was operational when the original loan was sold.
Let's say it is delayed still, I am not really concerned. I am playing for much more than that....
My point is stocks can move in either direction for reasons that have nothing to do with business fundamentals. BTW all of these index add/sell trades play out ahead of actual rebalance day.
If you’re worried about 4 months of underperformance, I’d suggest avoiding volatile small/micro caps….
@bagooga777@danbayston@duosEdgeAI@Axe Example of DUOT actually benefitting from this non-fundamental buying came in mid-to-late May. Stock went basically vertical on Russell index inclusion.
1) not every institution is running a fundamental investment strategy. Could be quant/factor algo, technical-based strategy (the chart has broken some important technical levels so this is possible), etc. Could also be an index arb strategy playing for them to get bounced out of Russell 3000 (rebalance twice a year) I’m saying that based on the fundamentals and my view of the end market/business, this is an attractive investment.
2) if it is a fundamental investor selling, maybe some institution has changed their outlook on AI infra and is taking down their exposure.
3) institutions being patient is a myth. I have witnessed this first hand. Stock starts moving against PM’s and they bounce. Those involved (likely not many) could’ve jumped ship seeing stock move wrong way.
4) this stock trades so little (<$8mm ADV) that I doubt most funds are actually doing work on it/are involved. Buying enough shares to make it worthwhile is outright hard at this point.
5) would guess most institutions are waiting for them to execute on the first 55MW of deployment with AGPU before getting involved.
6) maybe someone knows something we don’t and things aren’t as good as I think they are.
These are buying opportunities if you believe in the fundamentals of the business….. but we are learning that most of the DUOT shareholders are wildly impatient and very reactive to share price not going up 😂
Fundamentally this business is getting better and we are approaching the inflection point….
I’ve laid out the high level thesis on $DUOT in the quoted post. ~$300mm mkt cap AI colocation operator run by an industry veteran, access to powered land, 90-120 day deployment timeframes for 5-30MW clusters, strong unit economics, low maintenance capex, contracts with hyperscalers and smaller neoclouds, clean balance sheet, and EBITDA set to grow from ~$5mm this year to ~$40mm in 2027 and at least ~$80mm in 2028. If you have any duration and can stomach share price volatility, this is a small cap data center business worth owning.
The market panic presents a great opportunity to step back to 1) review the underlying DUOT assets/valuation, and 2) explore why DUOT is a prime acquisition candidate.
Given the nature of the business, we can evaluate each of DUOT's deployments individually (table with more detail in photos). These are just clusters we are publicly aware of, and with a 90-120 day deployment time there are likely more in the pipeline that aren't announced/can still be deployed for 2027/28. 2027 Guidance doesn't even include one of the deployments I discuss (!), but the opportunity has been disclosed by the customer (AGPU) at a conference.
4.8MW Hydra Host/AGPU Colo in GA
DUOT Ownership: 100%
Initial Lease Length: 5 Years
Annual Asset EBITDA: ~$7.9mm (4.8MW x $2.2/MW x 75% margin)
Debt on Asset: $0
Status: Active as of 9/30/26
Other Comments: DUOT recently sold the GPU's in this cluster to AGPU and is due ~$43mm cash in 12 months. They will still be customer facing and lease the GPUs from AGPU. My estimate on the MW figure. Revenue accounting on this may be a little funky, so just solving for the EBITDA based on disclosed unit economics.
10MW Hyperscaler Colo
DUOT Ownership: 100%
Initial Lease Length: 5 Years
Lease Contract Revenue: ~$111mm
Annual Asset EBITDA: ~$16.7mm (~$22mm x 75% margin)
Debt on Asset: $0
Status: Coming online in 4Q26
Other Comments: IG hyperscaler customer, also located in Columbus, GA. Disclosed in June 2026
55MW AGPU Colo JV 1
DUOT Ownership: 51%
Initial Lease Length: 5 Years
Lease Contract Revenue: >$500mm
Annual Asset EBITDA: ~$38.3mm (~$100mm x 75% margin x 51% ownership)
Total JV Debt: ~$100mm (est.)
Status: Deploying in 4Q26/1H27
Other Comments: AGPU investing ~$140mm of cash for its 49% JV stake. AGPU already has customer prepayments for the deployment. DUOT CEO flagging deployment costs are tracking below the ~$6mm/MW planned level, no DUOT equity investment required.
55MW AGPU Colo JV 2
DUOT Ownership: 51%
Initial Lease Length: 5 Years
Total JV Debt: ~$190mm (est.)
Annual Contribution Profit: ~$46.3mm (55MW x $2.2/MW x 75% margin x 51%)
Status: Comes after first 55MW deployment
Other Comments: Disclosed per AGPU CEO at the Moody Capital conference. Assuming similar JV structure though more debt required (assuming ~$6mm/MW build cost)
Total Company EBITDA and Valuation
Putting this all together, we get ~$109mm of EBITDA net attributable to DUOT at the asset level. Factoring in ~$25mm of corporate SG&A gets us to ~$84mm of EBITDA at full deployment of these 4 clusters.
I use 13.7x EV/EBITDA to value the biz which is a 25% discount to the LT average of data center and tower operators. This would imply EV of ~$1.15bn. The comps currently trade at 20x EBITDA, and I think DUOT could get acquired for even more than this.
Subtract ~$150mm of JV debt attributable to DUOT, we reach ~$1bn of equity value. Assuming 40mm shares outstanding, we reach a $25/share price. At a 20x multiple valuation is ~$38/share.
Note, I don’t assign a value to the technology solutions/distribution business but I believe it is a key factor to DUOT being able to deploy clusters in a 90-120 day time frame.
Why DUOT is an Interesting M&A Target
1) Re-lease opportunity. DUOT is leasing its colo assets at ~$2mm/MW per year on average. On AKAM's update call on their Anthropic deployment, the CFO noted models should assume colocation costs of ~$3-4mm/MW. An acquirer has the ability to re-negotiate the DUOT leases at a meaningfully higher rate closer to current market levels. At the low end this is 50% higher leasing revenue for the DUOT assets.
2) Cost of capital. Executing on the announced pipeline will be done at a more accretive manner than if DUOT kept going at it alone.
3) Large SG&A synergies. I think 75% of the ~$25mm of SG&A can be cut by a larger buyer with scale.
4) Getting Doug Recker on your team. Doug has built/operated/sold two data center businesses already. The amount of change he has driven at DUOT in 2 years requires strong operational prowess and industry know-how. He's also been key to finding these 10-30MW latent powered land opportunities. Having him as an advisor (or just not competing against you) is a plus.