@lejooon @AnalysAvAktier @Th__Nielsen@aktiehesten Thanks, yes could be higher than 60% and in that case up to 100% downside… but at least we know it has flattened now
I think there’s an error in that chart, looking at the b2c numbers in the excel from Betsson’s home page (and here) it has not declined yoy in any quarter
@lejooon @AnalysAvAktier Due to the addictive nature of gaming the levels typically persist post championships, as seen historically. Base growth at 8-9% with periods of higher is still good. ~20% on my estimates based on Turkey flat ahead (10% growth with ~50% incremental margins)
@lejooon @AnalysAvAktier 1. Yes i assume around 60%, same as Thomas Nielsen etc. We know they have other B2B customers as well. Why do you think it’s higher?
2. since Q1 2024 at least no quarters of negative revenue growth for b2c?
@lejooon @AnalysAvAktier Include rhino+world cup growth ahead, op. Gearing will flip => p/e 7x. 10% bb + div yield, >20% underlying ebitda growth.
TSR: >30% not accounting for multiple expansion from 7x. Given Turkey flat ahead. >10% given tirkey to 0. Good risk reward?
@lejooon @AnalysAvAktier Rest of co is growing at 8-9% pre World cup which will have massive effect. max 5% of remaining rev is turk. Assume 100% turk margin => ~20% further ebitda downside from turkey. Q1 annualised=> p/e 11x
@ReneSellmann Yep, the deal was announced but not the increase (afaik), local brokerage houses also noting it as an unexpected increase.
Still a cheap imo though
@JFremming@siddhar59844987 Ser ut som det også vil gjelde «seriøse» aktører. Ref: https://t.co/ww6x1otlMF
I tillegg ønsker venstresiden å gå lenger enn dette
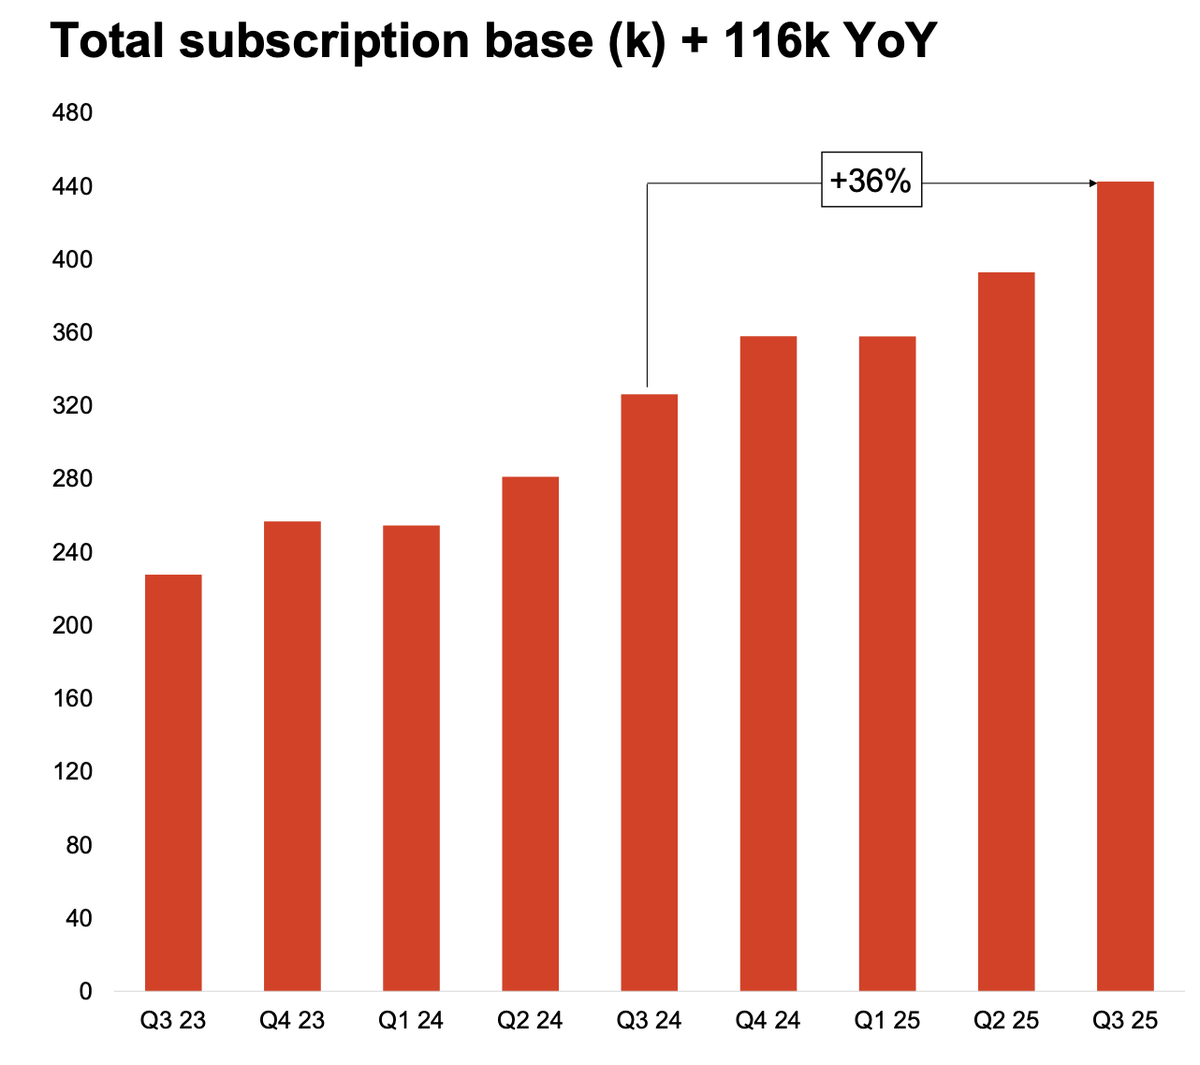
Lots of stars aligning for Xplora...
Megatrend: Social media regulations for youth as a demand tailwind
Doro acquisition: About to add high-margin subscriptions for senior phones (2x volume of kids segment)
Currency effect: COGS in USD => inc. marg. exp.
P/E 26e/27e: 9x/7x ?
Lots of stars aligning for Xplora...
Megatrend: Social media regulations for youth as a demand tailwind
Doro acquisition: About to add high-margin subscriptions for senior phones (2x volume of kids segment)
Currency effect: COGS in USD => inc. marg. exp.
P/E 26e/27e: 9x/7x ?
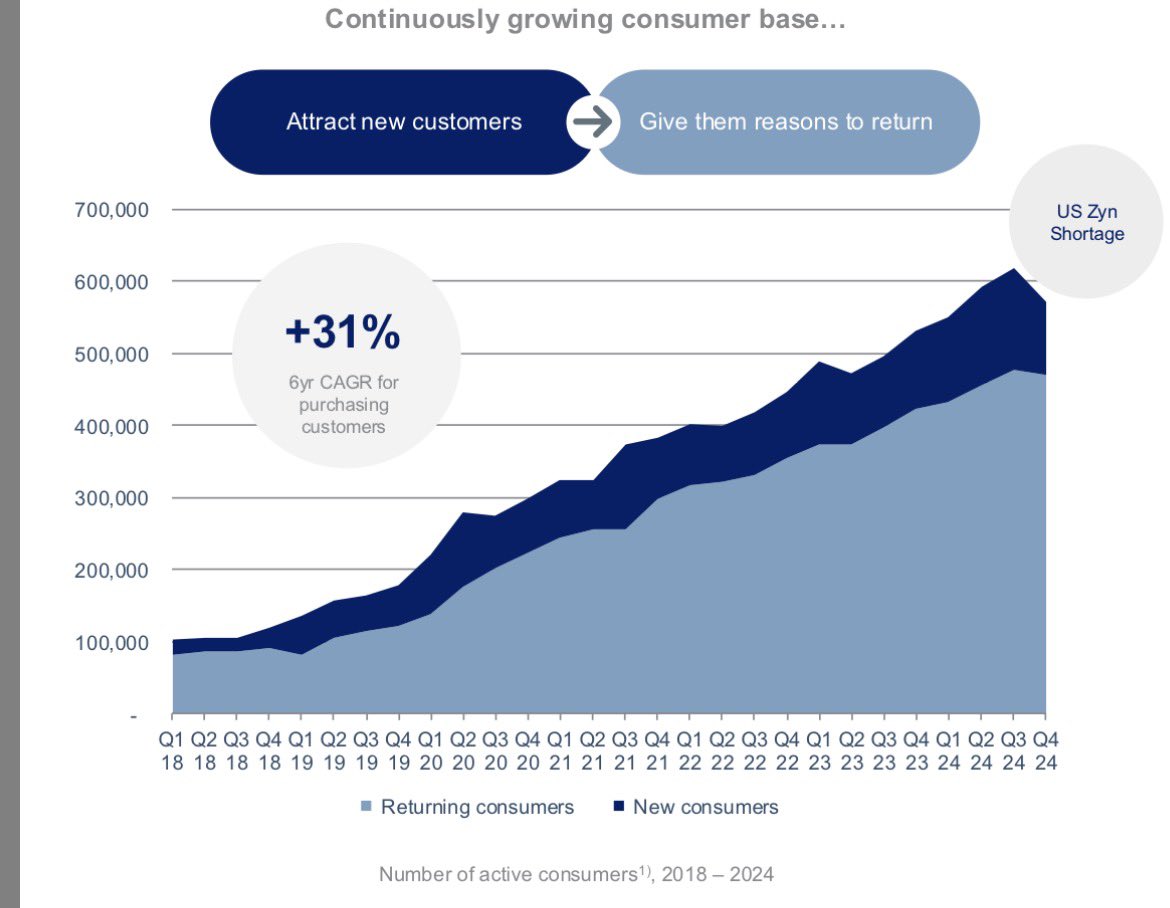
@Divergent7651 What competitive advantage does haypp have over its retail competitors? Scale and lower overhead means they can sell cans at a much lower price which clearly is attractive to the consumer. In addition you have the M&I business unique to haypp vs retailers…
@Divergent7651 But like for like growth was ~80% essentially indicating customers were switching from zyn to other brands, indeed staying loyal to haypp rather than the NP brand?
Appear: Tek til live tv/stream prod. (OL,PL,NFL,VM++)
'25e P/E 17x, '26e 12x & 27e <10x på guiding; 25-30% growth, 17-20% ebitdac margin
Net cash (300m vs mcap på 2.5bn). Capex > D&A slik at EV/EBITDAC ≈ P/E
~20% recurring rev. NWC 8% sales. 70% GM & >30% inc. EBITDAC margin