@Mr_Derivatives So I will start calling out your track record since I asked Claude to check your tweets for the past 24 months: average p&l 3.5%, around 1000 (!) tickers mentioned, hit ratio below 50%. Hmmm....
@RAlvarez114@HedgeyeHC Don‘t expect too much usually such negative events are ignored on the call… I stopped subscribing years ago because the kept hyping a stock and then left you hanging when it went downhill
@CynicalPublius omg no its not! kitkat ismjust industrial crap without taste it lacks the richness and crunch of kvikk lunsj, its not even close! have you ever had a kvikk lunsj???
I need a haircut before classes start. But after examining my bank statements, I discovered I'm running a huge trade deficit with my barber. I'm always buying haircuts from him, but he hasn't purchased a single economics class from me! Luckily, my wife tells me she's good with horse clippers. Balance trade here we come!
I just hope my dentist is interested buying some econ lectures...
@Mike_Taylor1972@EricSte83854527 stop scaring people Mike your track record for predicting general market movements is terrible. Where I respect your skill is in picking stocks in the Health Care space I think there you have real expertise which works. stick to that.
@MOSSADil So I typed that in as well and this is what I got: "That's always a good opportunity to make a new connection! Have you had a chance to say hello and introduce yourself yet?" Are you gaslighting Google?
This is essentially true.
However, it is possible to filter for exceptional people from any country. The problem for the left is that exceptional people mostly won’t vote for them.
A MESSAGE TO THE AI BEARS
When AI bears look at the low multiples $SKHY, $MU, $SNDK and Samsung then the response is usually some version of “earnings multiples are meaningless for cyclical companies at peak demand and peak margins.”
The reason these suppliers trade at such low multiples is precisely because the market already assumes today’s earnings are temporary... people aren't valuing current margins as permanent so the debate is really about duration.
If earnings peak this year and begin collapsing shortly afterward then the low multiples are traps and I agree with the bears but if supply remains tight for several more years (which I do) then those valuations are WAY understated with how much cash the companies will generate before the cycle turns.
SK Hynix has said the shortage could remain severe through the end of the decade while Samsung has also pointed toward meaningful tightness continuing through at least 2027.
These companies obviously benefit from presenting a strong outlook so their forecasts shouldn't be accepted blindly but they also have the clearest view into customer commitments, equipment orders, wafer capacity, packaging constraints and the production schedules of the entire industry.
The double-ordering argument also deserves a bit more context because a weak fill rate can sometimes indicate ghost demand but it can also mean customers are trying to secure supply they genuinely cannot obtain.
The stronger evidence for me is from the structure of the agreements since customers are signing multiyear contracts, accepting pricing floors and ceilings, providing prepayments and in some cases helping suppliers fund additional capacity (temporary demand usually doesn't commit capital years ahead or help finance the supplier’s expansion).
This cycle also looks different from a traditional cycles because the physical bottleneck is much harder to solve since HBM consumes substantially more wafer capacity than standard DRAM while each new generation becomes more difficult to manufacture and package.
As the memory suppliers move from HBM3E toward HBM4, HBM4E and later generations, part of every capacity increase is absorbed by the greater manufacturing intensity of the product itself.
That same narrative supports $TSM and $ASML because more advanced AI chips require leading edge wafer capacity, EUV tools, advanced packaging and years of coordinated capital investment before supply can meaningfully expand.
TSMC doesn't add capacity overnight while ASML machines sit at the beginning of nearly every leading edge production roadmap which makes the supply response slower and more capital intensive than a normal short-cycle industry.
$NVDA, $AMD, and $AVGO sit one layer closer to the end demand but the same duration question applies since bears say $META, $GOOGL, $AMZN and $MSFT are overordering accelerators and custom silicon which eventually creates excess inventory and falling margins but my takeaway is that training demand is being joined by inference, agentic AI and custom silicon programs that extend the cycle way longer than people expect.
The argument that these companies are at peak demand also becomes less convincing when the bottlenecks continue moving across the stack since one quarter the shortage is GPUs, then its HBM, then advanced packaging, then optical connectivity, then power, cooling or data center capacity.
Again that doesn't mean shortages last forever but it does suggest the buildout is still expanding across several physical layers rather than reaching a clean and obvious peak.
I agree that cyclicality hasn't disappeared since semiconductors will eventually reach a point where supply catches up with demand, pricing weakens and margins decline but I really think people need to compare the expected duration of the shortage with current valuations, contract structures, capacity timelines and the risk that AI demand slows before new supply reaches the market.
The industry will eventually normalize but if the market is valuing many companies as though earnings collapse next year while supplier commentary and fab timelines point to tightness lasting much longer then the low multiple may represent opportunity rather than warning.
Elon just created 4,400 millionaires in a single day.
400 of them are now worth over $100 million.
These aren't VCs. They're SpaceX employees, and the list includes welders, technicians, and cafeteria staff, because for two decades the company paid every level of the workforce in stock instead of higher salaries.
Juan Hernandez immigrated from Mexico and took a $28 an hour contractor welding job in 2015. He says he didn't even know what SpaceX was. The company gave him a $10,000 equity grant and let him buy more shares through payroll deductions. That stake is now worth $880,000.
Trevor Hise's parents wanted him to take a stable job at General Electric. He picked SpaceX instead, stayed 12 years, and accumulated over 100,000 shares. At the $135 listing price that's $13.5 million. He's 37 and semiretired. His words: "The magnitude of this has been ridiculous."
The most telling detail came before the listing. Over 100 employees quietly banded together and negotiated a group wealth management deal covering up to $5 billion, because none of them had ever needed a wealth manager before.
Software IPOs have minted millionaires for 30 years. This is the first one where the money went to the factory floor.
🚨 IDF SEIZES BEAUFORT RIDGE IN LEBANON
The IDF says it has launched a large-scale operation in the Beaufort Ridge and Saluki River area of southern Lebanon.
According to the report, Israeli forces crossed the Litani River and expanded attacks against Hezbollah north of the river, near Nabatieh.
The operation includes Golani, Givati, the 7th Armored Brigade, the Fire Brigade, and the multi-dimensional unit, under Northern Command and the 36th Division.
Before ground forces entered, the Israeli Air Force carried out heavy strikes on Hezbollah infrastructure, backed by artillery and tank fire.
The goal, according to the IDF: strengthen operational control in southern Lebanon and remove the direct threat to the Galilee panhandle and Metula.
This is not just another tactical move.
Beaufort Ridge is one of the most symbolic and strategic points in southern Lebanon, overlooking critical terrain and carrying deep military history from Israel’s previous wars in Lebanon.
Boost the algorithm: Bookmark, Share, Reply, Repost, Like and Follow @Mossadil.
Ironically, by blocking the Straits of Hormuz, Iran became Israel's proxy. Each time Israel is threatened, it can attack Iran and in response Iran will send oil prices rocketing, forcing the world to deal with the problem. Iran basically became Israel's Houthis.
I am the Chairman and CEO of Vornado Realty Trust. Eighty-four years old. Seven buildings in Midtown Manhattan. I said what I said.
I said "tax the rich" is the equivalent of a racial slur. I said it at REBNY. Into the microphone. Eight hundred people. Median net worth in that room was north of $240 million, I know because our CFO ran the guest list through a Bloomberg terminal as a joke, and then it wasn't a joke. And when I said it, twelve people applauded. The rest nodded. One woman in the third row mouthed, "Finally." I saw her.
Sharon, my communications advisor, Columbia, $430,000 a year, very bright, Sharon wants me to walk it back. She drafted something. "Mr. Roth's comments were intended to highlight the emotional impact of political rhetoric on business communities." I read it. I put it in the trash can on my desk. Not the recycling. The trash. Here's my clarification: I understated it.
"Tax the rich" is worse than a slur. A slur is just a word. It doesn't come with a CBO score. Nobody is introducing a bill called the Racial Slur Implementation Act of 2026. But there are seventeen active proposals in Congress, I had Sharon count them, seventeen proposals designed to take more of my money. My money. Mine. Money I acquired by being better at acquiring Manhattan commercial real estate than anyone alive for four consecutive decades. That is not a crime. That is a record.
I pay property taxes on $18.2 billion in assessed assets. $412 million a year. Say it again: four hundred and twelve million. I carry that number. It's the first thing I think about when I see a protest sign. I think: I pay more in property tax than the entire annual budget of the city of Fort Lauderdale. I looked this up. Fort Lauderdale: $408 million. Steve Roth: $412 million. I am a small city. And the city doesn't get screamed at.
My effective tax rate last year was 11.4 percent. I say this because I believe in transparency and because I'm not ashamed of it. The rate reflects the legal structure of real estate investment trusts, depreciation schedules Congress established in 1986, and carried interest provisions that both parties have voted to preserve for forty years. I did not write these laws. I organized my entire financial existence around them with the help of nine full-time tax professionals who have offices on the 38th floor of 888 Seventh Avenue, which I also own. Their office is in my building. Their work protects my buildings. This is not a loophole. Sharon calls it a loophole. I've told her: a structure maintained by nine attorneys across four decades is not a loophole. A loophole is something you slip through once. This is architecture. This is the foundation. This is the building.
Last Tuesday, same as every Tuesday, I walked past 1290 Sixth Avenue. My building. And there was a man. Same man as last week. Same sign: "Billionaires Pay Your Fair Share." He was standing on my sidewalk. My literal sidewalk — my company owns the ground lease. He was maybe thirty. He was wearing a jacket I would estimate cost $60. My lunch that day was $114. For one. I am telling you this not to boast but because these are facts. He has decided I'm his enemy. Based on a number he saw on a Forbes list. He doesn't know what I pay. He doesn't know what my buildings cost this city in construction jobs and lease revenue and foot traffic. He knows one number. He has made one judgment.
I see him every Tuesday. I've started to notice things. He brings coffee from the cart, not the Starbucks. He has a backpack that looks heavy. He doesn't look unhealthy. He looks like he probably works somewhere, but not on Tuesdays. I've wondered: does he have a job? Does he have a building? Does he have anything that depends on him the way 4,200 employees depend on me? I suspect not. And yet he has opinions about my tax rate.
I gave $22 million to charity last year. The Met. NYU Langone. Mount Sinai. I gave a building to NYU. Not money for a building — a building. The Steven Roth Residence Hall. It houses 400 students. That man with the sign has never housed 400 students. He hasn't housed one. He gives cardboard. I give structures. This is not a comparison I'm making to flatter myself. It's just arithmetic.
When I said what I said at REBNY, I was saying what every person in that room believes and none of them will say publicly because they have communications advisors and the communications advisors all went to Columbia and they all say "unhelpful." I'm eighty-four. I'm too old for helpful. I'm too old to perform restraint for people who hate me for something I can't change.
I didn't choose to be rich. I chose to be good at one thing for a very long time, and this is what happened. You don't punish someone for that. You don't legislate against someone for that.
My net worth fluctuates between $3.8 and $4.1 billion depending on the quarter. I fluctuate more in a fiscal week than that man on my sidewalk will earn in his life. Both of these are facts. Only one of them is considered polite to say.
They want me to apologize.
I'll be dead in ten years. Twenty if I'm lucky. And they'll still be renting my buildings.
Why Bears Are Always the Most Popular People in the Room:
There is a peculiar irony at the heart of financial markets. The people who have been most consistently wrong over the past century — the permabears, the perennial crash callers, the doom merchants — are also the most followed, the most quoted, and the most admired. Understanding why tells you something profound about human nature, and something even more useful about how to make money.
It starts in the brain. Neuroscience has established beyond doubt that humans process negative information more deeply than positive information. A warning of danger triggers an ancient threat response — the same one that kept our ancestors alive on the African savanna. When a bear steps in front of a camera and says "the system is broken and here's why," something in your nervous system sits up and pays attention in a way that "equities look reasonably priced" simply never will. Bears don't just get attention. They get the right kind of attention — the deep, visceral, share-it-with-your-friends kind that built the entire media industry.
Then there is the intelligence problem. Optimism sounds naive. Pessimism sounds sophisticated. Saying "the economy is fundamentally healthy and stocks should grind higher" sounds like something a used car salesman would say. Saying "the debt supercycle is entering its terminal phase and here is the 47-slide deck that proves it" sounds like someone who has done their homework and seen behind the curtain. Social media was purpose-built to reward perceived intelligence, and on social media, doom sounds smart.
The bears also benefit from the most generous get-out-of-jail-free card in intellectual history: the unfalsifiable prediction. "The market will crash" has no expiry date. It will always eventually be true. A permabear who has been wrong for a decade simply says "I was early" — a phrase that somehow carries no shame whatsoever in financial circles. If you are wrong in the bearish direction, is essentially a career-neutral event.
And when the bear finally gets their crash — once every seven to ten years, because markets do in fact correct — they become legends. Everyone remembers who called 2008. Nobody remembers the forty-seven wrong predictions that came before it. One correct call creates a halo that lasts decades, sustaining careers, book deals, and podcast audiences long after the original insight has expired.
The deepest reason bears dominate social media, however, is cultural. A significant portion of the audience feels economically left behind — unable to afford a home, watching wealth concentrate at the top, sensing that the system works for someone else. Bear content doesn't just entertain these people. It validates them. "Yes, the system is rigged, and it will collapse under its own contradictions" is one of the most powerful sentences in modern media because it simultaneously confirms the audience's lived experience and promises justice.
The data, of course, tells a different story entirely. The S&P 500 has compounded at roughly 10% annually for a century, through wars, pandemics, financial crises, and political chaos. The single greatest wealth-building strategy in history has been to buy great businesses and do almost nothing. It is not exciting. It does not go viral. It does not validate anyone's grievances or confirm their suspicions about the ruling class. It just works, quietly, decade after decade, for the patient and the brave.
The bears will always be in the room. They will always be the most entertaining guests. Just don't let them manage your money.
PG&E and @Tesla have just announced that the Cybertruck, Tesla Powershare Gateway and Tesla Universal Wall Connector have all been approved for participation in PG&E's residential Vehicle‑to‑Everything (V2X) program, marking a major milestone for bidirectional EV integration in California.
This marks the first AC vehicle-to-grid application approved for customers in California, enabling vehicles to connect using much simpler equipment rather than specialized DC infrastructure.
PG&E customers with Cybertrucks will now be able to use their vehicle to power their home in an outage and earn money by selling power back to the electric grid during grid events.
"Electric vehicles can do more than move people—they can help power homes and support the grid," said Jason Glickman, Executive VP of Strategy and Growth, PG&E. "By welcoming Tesla into our residential V2X program, we're expanding customer choice while making California's grid more flexible, resilient, and affordable. Powershare Grid Support enables Tesla vehicles to strengthen our electricity system, while earning money for EV owners."
More info below:
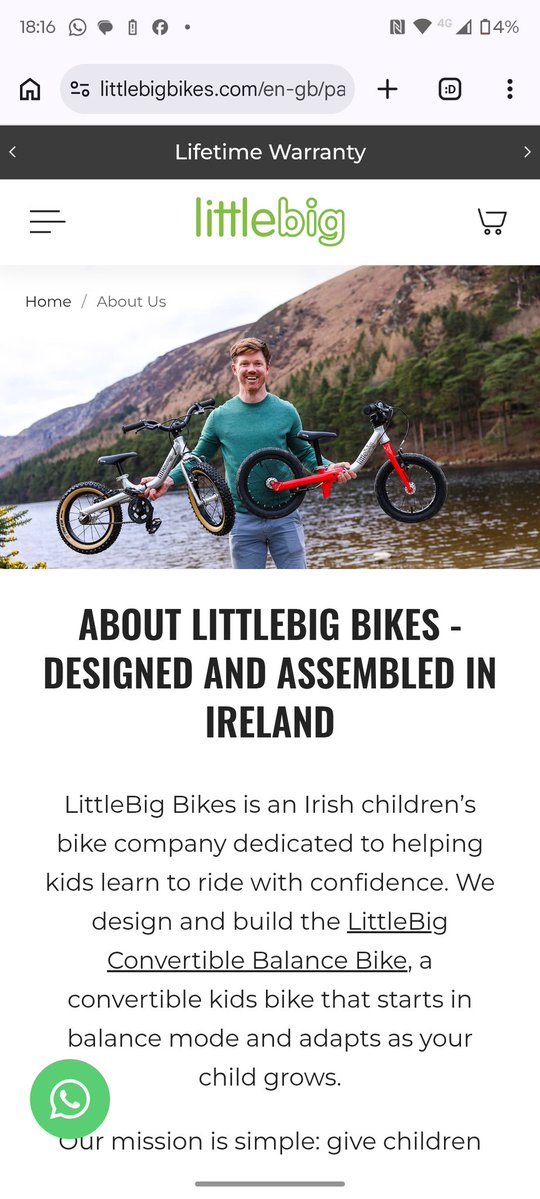
I can't imagine having this mentality. @LittleBigBikes think they are helping Palestinians by punishing an Israeli child by refusing to replace pedals and brakes which they agreed to replace when the bike was bought. "Lifetime warranty" my ar*e. Ireland has a sickness.