most people in the comment section will just share their referral links.
here are categories of different crypto cards/neobanks based on what you actually want to do with them:
• if you want to spend against your assets (fully self-custodial) and avoid tax issues: @ether_fi, @Nexo & @xplaceapp
• if you have a lot of people to refer to a crypto card, here’s one that currently offers the best referral rewards: @Nexo, @EthenaPay & @SolidYield
• if you want access to DeFi, yield & more: @avici & @useTria
• if you’re in the EU, LATAM,.: @wirex_one, @ether_fi & @coca_card
• if you want to avoid the standard 1% FX fee when spending in multiple currencies: @ether_fi
• best for people in India and maybe other restricted regions: @Pionex & @KoloHub
• if you want a privacy card: @SeismicSys ecosystem & @offgridcash (non-KYC, still in beta)
• best card options in APAC & Africa: @Redotpay, @plasma, @pulsarmoney & @Bitgetwallet
• best for the highest yields on your idle balances: @EthenaPay, @ether_fi, @avici & @wirex_one
• if you want to send money abroad, get USD accounts, off-ramp, etc.: @jup_mobile global & @hyperbeat
• if you want access to credit: @joinCero
• unsecured credit for people who use crypto cards: @UVcredit
what did i miss?
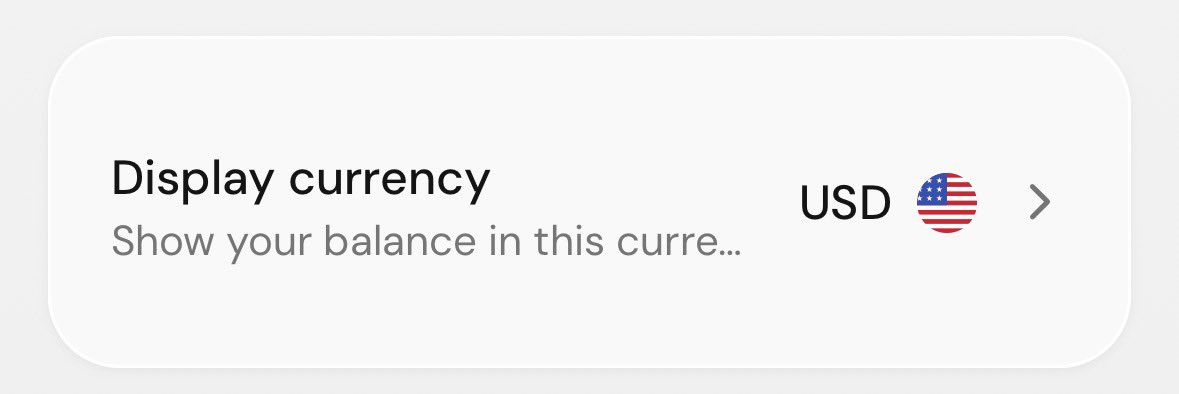
One of the most underrated features for every crypto neobank:
Displaying currencies that users can switch from $ to their own local currency.
People value their money in their own currency. It’s one way to help them get familiar with your product rather than always using $ or £ as the default.
If you want to replace their bank, at least look like one first.
shame on everyone who was pushing this from the very beginning and is now radio silent, especially those people at Polygon.
but they can’t use the same energy they used to push the product to us to make the founder accountable.
there are just too many unanswered questions.
what really happened?
why did the founder pivot?
why can’t we get a full, detailed explanation of the whole scenario?
why are they charging people outrageous fees to withdraw their money?
even if you want to shut down, this is never the right way to do it. people need answers.
you can’t just vanish into thin air without updating people on what’s going on.
if the former founder can find the energy to make a tweet and comment on random messages, they should be able to prepare a proper post-mortem explaining what really happened behind the scenes at KOSHMoney.
this is very wrong!
Well played, @usekoshmoney. A $10 fee to automatically settle my funds after three weeks of downtime.
I’m never touching another product built by @TarunMangukiya, @dalpattapaniya, or the @usekoshmoney team.
Kosh went down three weeks ago. There was no public update for the first week. Then, under pressure, they posted a GPT written update. Founders were busy responding to random tweets.
They were supposedly working on a “security update.” Now they’ve liquidated all the funds on my card without my approval and charged me $10 out of the blue, even though the dashboard explicitly said "card withdrawals were coming soon."
They accepted deposits from multiple chains, but Polygon is the only option for withdrawals.
@iirfan I used your referral for sign up, please be mindful when sharing referral for such products in the future.
I understand that products and startups can fail, but founders should have the guts to take responsibility instead of chickening out.
@usekoshmoney was supposed to be better than @KASTxyz, and its founder was supposed to have more fintech experience than the founders of @dodopayments.
What a joke!