“NYSE margin debt is reaching historic levels:” Deutsche Bank analysts. This is partly due to a “surprise dovish Fed pivot in Dec’23…Since Oct’23, NYSE margin debt has increased 136%, which is the fastest rate of margin debt expansion on record” except for February & March 2000
I just published my post on why I believe the market is underestimating how big AI winners both $AMZN and $META are. In the article, I also explain that Anthropic's Mythos preview was trained on $GOOGL TPUv7.
- AWS acceleration and the importance of its "traditional" infra
- Trainium, TPUs vs $NVDA GPUs (including costs)
- The value of $META's MSL lab, and the importance of Muske Spark
- $META's unique distribution advantage
https://t.co/zvHcyU8Icr
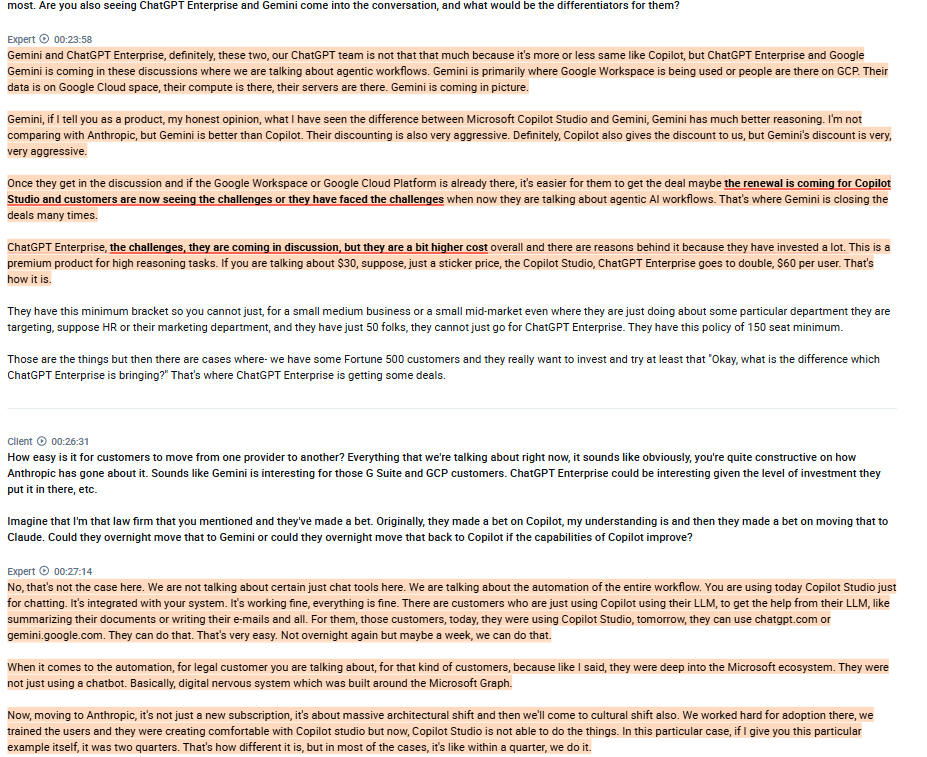
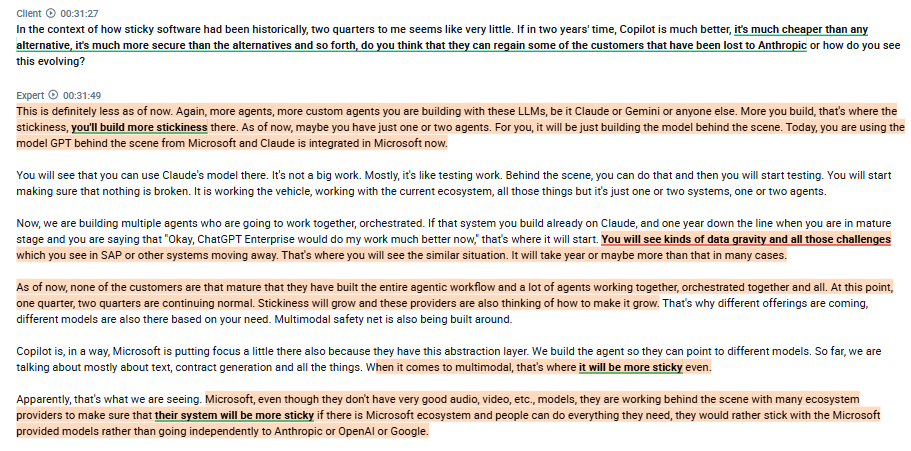
A MUST-read interview with an Accenture employee explaining the current usage patterns of $MSFT Copilot, Claude, and other AI models in enterprise usage:
1. They mostly work with large and large mid-market companies. According to him, as far as it comes to $MSFT Copilot, everybody has a license wherever they have Microsoft. 80% of his clients start with $MSFT because of the plumbing, security, and data access, as the integration is very seamless, as they already use $MSFT. But now he estimates that AROUND 50% of the clients are actively experimenting with second vendors. This is where Anthropic is coming into the picture, mostly because of reasoning, the long context window, and other things.
2. He explained that while 80% of their clients have adopted these solutions, that doesn't mean the market is saturating, as there is the question of usage.
3. In his view, we are not entering the phase where people are looking for these providers to automate the workflow.
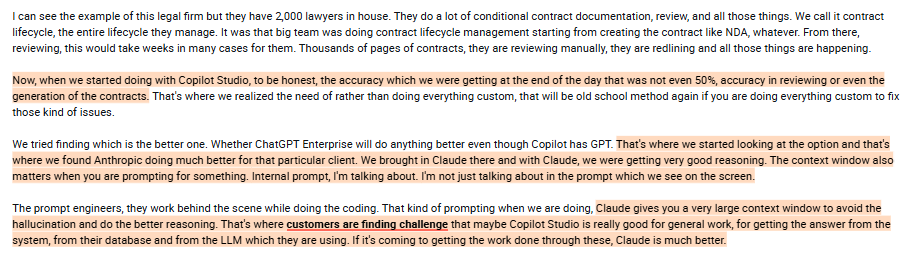
4. The main issues of $MSFT Copilot in terms of performance vs Claude are, in his view, the hallucinations and worse reasoning. Claude's context window also matters a lot.
5. They are also seeing ChatGPT Enterprise and $GOOGL Gemini coming into discussions, especially when talking about agentic workflows. Gemini is strong where people use $GOOGL Workspace or are on GCP. When he compared the performance, he thinks $GOOGL Gemini is better than Copilot, but doesn't think it's better than Anthropic. $GOOGL with Gemini is also very aggressive with discounting.
6. According to him, $GOOGL Gemini is closing many deals with agentic AI workloads when Copilot renewals are coming, and customers are seeing the challenges they have faced.
7. In terms of switching costs between providers, the expert explains that when we were in the chatbot era, the switching costs were small, as you could switch between chatbots in a week. But now, as we enter the agentic workflow era, the switching costs are higher and last 1-2 quarters.
8. He also thinks that as more and more agents are built, the stickiness of a vendor becomes higher, and the switching costs might start to resemble more of the traditional software, where it takes a year or more to switch in some cases. He thinks stickiness will continue to grow, especially with things like multimodal usage.
9. In his view, $MSFT is working behind the scenes with many ecosystem providers to make sure that their system will be more sticky as a lot of clients would rather stick with $MSFT-provided models rather than going independently to Anthropic, OpenAI, or $GOOGL.
found on @AlphaSenseInc
Interestingly, investors in credit markets are starting to buy around the margins. For example, at the end of February, leveraged loans yielded the most relative to high-yield bonds since before the pandemic, but have since started to gain back some ground. (3/3)
Foreign money is rotating hard into Japan 👀
When open interest on 20Y JGB futures spikes to records on the Japan Exchange Group, that’s not random flow; that’s positioning.
It feels like a macro bet:
- Peak global yields
- Front-running a Bank of Japan shift
- Pure relative value vs US/EU debt
When foreigners are 20x domestic participation, it’s not “tourist” money. It’s conviction.