Did you know that the FDIC covered all 86% of the deposits in the $SBNY bank failure using the Systemic Risk Exception (SRE) Rule?
Did you know that 76% was above the FDIC Insured limit of $250k? (~$84B)
They used stock holder assets to bail out the "uninsured" rich people. Hence, the stock crash.
So who is at fault? I think you are pointing the finger at the wrong people at this point. SBNY may have screwed around but the real theft came when the FDIC and Yellen envoked the SRE and stole the assets of share holders to bail out the rich deposits (that knowingly deposited funds over the federally insured limit)!
@SecScottBessent promised to review this, but so far it has been silence by him and the FDIC, even though the FDIC is legally required to update the public on a regular basis, they just don't do it.
In my eyes, this is the real crime. $SBNY
🧵
“Signature Bank shareholders weren’t wiped out by the market... They were wiped out by a rule that protects the irresponsible rich depositors.”
Signature Bank - $SBNY didn’t fail because it was insolvent in the traditional sense.
It failed because regulators changed the rules mid-game & shareholders paid the price.
Here’s what most people still don’t understand 👇
🔹 What normally happens when a bank fails
Under standard FDIC rules:
• Depositors are insured up to $250,000
• Uninsured depositors absorb losses
• Shareholders are last in line — but not automatically zero
This hierarchy exists for a reason:
Risk is supposed to sit with large, sophisticated depositors — not equity alone.
🔹 What changed with Signature Bank
In March 2023, regulators invoked the Systemic Risk Exception (SRE).
That single decision:
• Guaranteed 100% of uninsured deposits
• Shifted tens of billions in losses away from depositors
• Replaced them with an FDIC subrogation claim
• Pushed shareholders from “last in line” to “structurally impossible”
This wasn’t a market outcome.
It was a policy override.
🔹 The math no one wants to talk about
At failure:
• ~$110B in assets
• ~$88–90B in deposits
• ~85–90% of deposits were uninsured
Under normal rules, uninsured depositors would have taken losses — and equity would likely have survived in some form.
Instead:
• Losses were socialized
• Depositors were made whole
• Shareholders absorbed everything
That is not capitalism.
That is selective risk redistribution.
🔹 Why this matters beyond SBNY
If regulators can:
• Retroactively rewrite depositor priority
• Override long-standing loss allocation
• Do so without shareholder consent or compensation
Then bank equity is no longer a defined risk instrument — it’s a political one.
Markets price rules.
When rules become discretionary, capital disappears.
🔹 Final thought
$SBNY still trades because some investors understand this:
“If the SRE had not been invoked, Signature equity would not be trading at pennies — and likely wouldn’t be zero at all.”
That’s not speculation.
That’s math + hierarchy + precedent.
And it’s why the SRE deserves far more scrutiny than it’s ever received.
Perhaps @SecScottBessent is already investigating this unfair turn of events!
MMTLP BIGGER THAN ENRON…REALLY???
@annvandersteel, do you like math??? Check our work…
Our friend @JohnnyTabacco did some math with actual verified prints (executed and recorded trades) on MMTLP shares sold on 12/9/2022 ( subsequently CANCELED). 21,000 shares sold at Etrade for $26M!
Let’s get to mathin’…
🔽🔽🔽
$26M / 21,000 shares = $1238 / share
Issued shares of MMTLP: 165,472,241
165,472,241 x $1238 / share = $204,854,634,358 (and that was just the beginning!)
🔽🔽🔽
#Enron: $60B (estimated pension & assets losses)
#Madoff: $65B (estimated investor losses)
#FTX: $8B (estimated investor losses, but they are getting their money back)
#SVB: $1.8B (estimated investor losses)
🔽🔽🔽
$204.8B > $60B (Enron) ✅
$60B + $65B + $8B + $1.8B = $134.8B
$204.8B > $134.8B (COMBINED) ✅
Did we get that right, Ann?!?
Bigger than ENRON??? You Betcha!!! 🎯🎯🎯
Bigger than ENRON, MADOFF, FTX and SVB…COMBINED!!! 😳😱🤯
Now you know why…
WE…ARE…NOT…GOING…AWAY!!! #Relentless
$MMTLP $MMAT $TRCH @FINRA@SECGov #RICO @TuckerCarlson@laralogan@JamesOKeefeIII@cvpayne@RealAlexJones@TheRobbCarter@kshaughnessy2@denniskneale
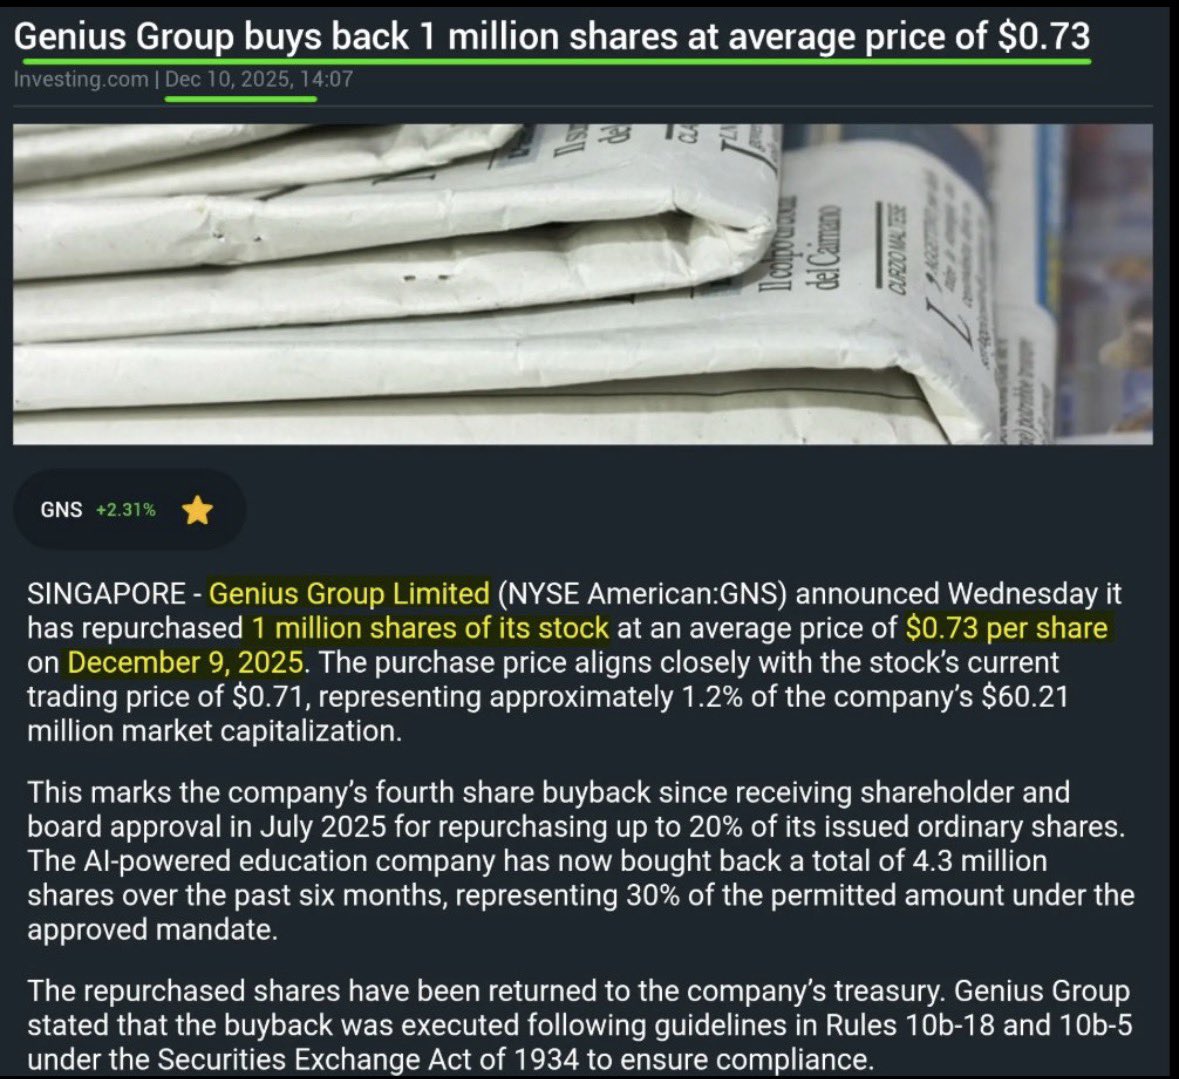
By my calculations, $GNS is now 2/3 locked up in DRS. When that number hits 100%, the proof of stock manipulation is solidified for their lawsuits. Congratulations on the buy-back @rogerhamilton
❄️❄️❄️
“Never doubt that a small group of thoughtful, committed citizens can change the world. Indeed, it is the only thing that ever has.” ~Margaret Mead
🚨3 Years after FINRA's U3 Halt of MMTLP that trapped thousands of investors...
🫵 YOU created The MMTLP Fiasco.
🫵 YOU conspired to protect the criminals.
🫵 YOU sacrificed innocent investors on the alter of your insatiable greed.
🫵YOU flipped that switch, and unleashed the MMTLPArmy.
✊WE warned you.
✊ WE are relentless.
✊ WE keep diggin'.
✊ WE are and will continue to expose you ALL, and
WE STILL COMIN'!!!
We didn't start this fight, but WE WILL FINISH IT. We are the MMTLP Army, and...WE ARE NOT GOING AWAY!!! #Relentless
BREAKING🚨 LARGEST FINANCIAL FRAUD IN U.S. HISTORY
This month marks three years since $MMTLP was halted. Investors have sent over 40,000 letters to Congress, gathered 100+ congressional signatures, and more, yet regulators still haven’t taken action.
BREAKING🚨 TOP EXECUTIVES ARE DEPARTING CITADEL
Are they flocking before major lawsuits?
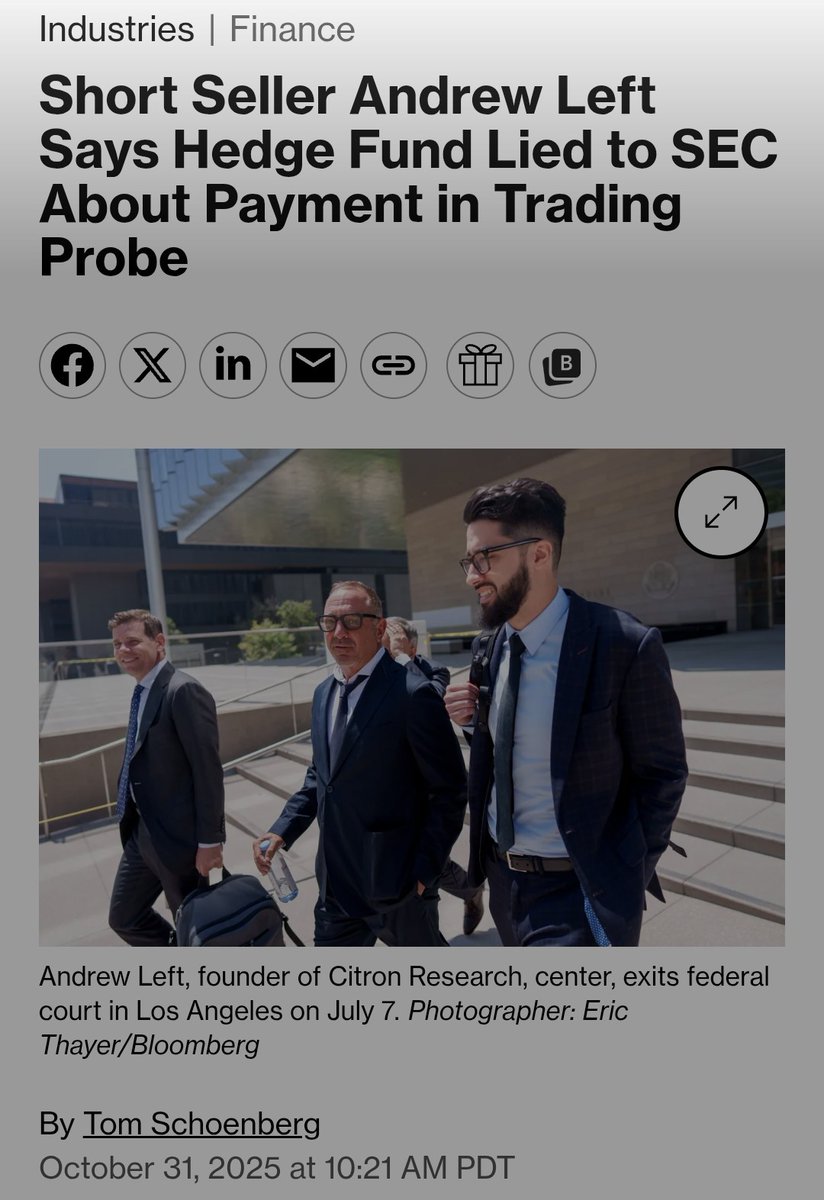
Genius Group is expected to file one of the biggest lawsuits against market manipulation (spoofing, naked shorting).
Defendants are about to be released by Nov 15th, is Citadel one? $GNS