1/N
Li Lu's is only person Munger trusts with his money besides Buffett. He has a simple investment checklist
Is that a good business?
Is that Cheap?
Who is running it?
What did I miss?
Using this lens, l will look at #Apar Industries
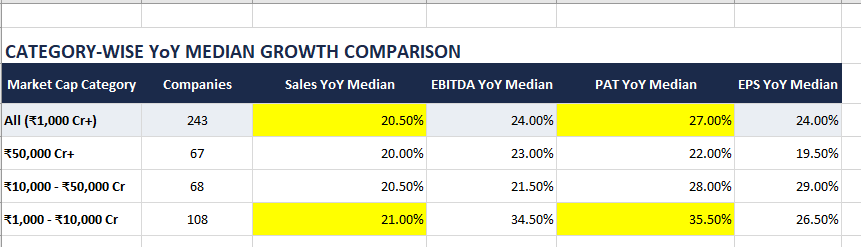
What ever be the reasons for price correction in nifty over aug/sep and now in smallcaps in oct.. its hard not to feel bullish if u look only at earnings and ignore all noise.
this is median of all companies (not aggregate).
Sales up 20%, PAT up 27%.
Indian stocks - This is a real big billion sale. Why are people not excited ?😎
Missed the sale in March ? Don't worry time for another sale! 😜
On a serious note, pick decent companies at attractive prices and leave the rest to time. The IRR will take care of itself.
I am looking for cheap (on earning capacity) / decent (co has some right to win) and where promoters are buying or bought recently (say last 6 months)
If you have to share one name what would that be?
If for whatever reason you can't do it publicly here dm me.
This is the single best chart highlighting the attractiveness of Indonesia.
Assuming the payout ratio is not abnormal, one can borrow in local currency and buy stocks.
On a diversified basket of well chosen sustainable high dividend plays you are unlike to loose money and may make 20-30% CAGR over the next few yrs say 3-5 yrs.
🇮🇩 #Indonesia - following this year's decline, equity dividend yield (8.2%) now exceeded 10yr gov't bond yield (7.4%) per Bloomberg data based on broker estimates.
2027 will be interesting with two opposite forces (MSCI threat vs. unusual valuations) for Indonesian equities.
Ujjivan at ~61/- odd is a no brainer investment.
At 10x FY27 Earnings , <1.5x BV and high teen ROEs (best in class) and high growth. (>20%)
And at some point it will become a universal bank.
What else do you want ?
Why l don't like PVR as a business
I feel cheated everytime I have to pay 300-500 for popcorn / cold drink.
We did a poll once with show of hands in an investor event in Kolkata and some 30-40% people felt that. The group would largely be comprising of top 5% of the income/wealth cohort
To me it's inverse Costco philosophy
Not to mention that they don't own any hard assets so depreciation is actual expense.
TVs are getting bigger and cheaper , and really wealthy would set up their own private den / theatre (5-20 members)
So OTT is a real threat.
So is declining attention span
They have negligible negotiating power
So at best, PVR is a trade and not investment worthy in my opinion
@Random_Gyan Not invested, just curious. Don't penetration & ticket prices both have a long way to go in India? Besides, premium consumption is finding a lot of appeal in India's middle class. Not sure about Indonesia's mkt dynamics..
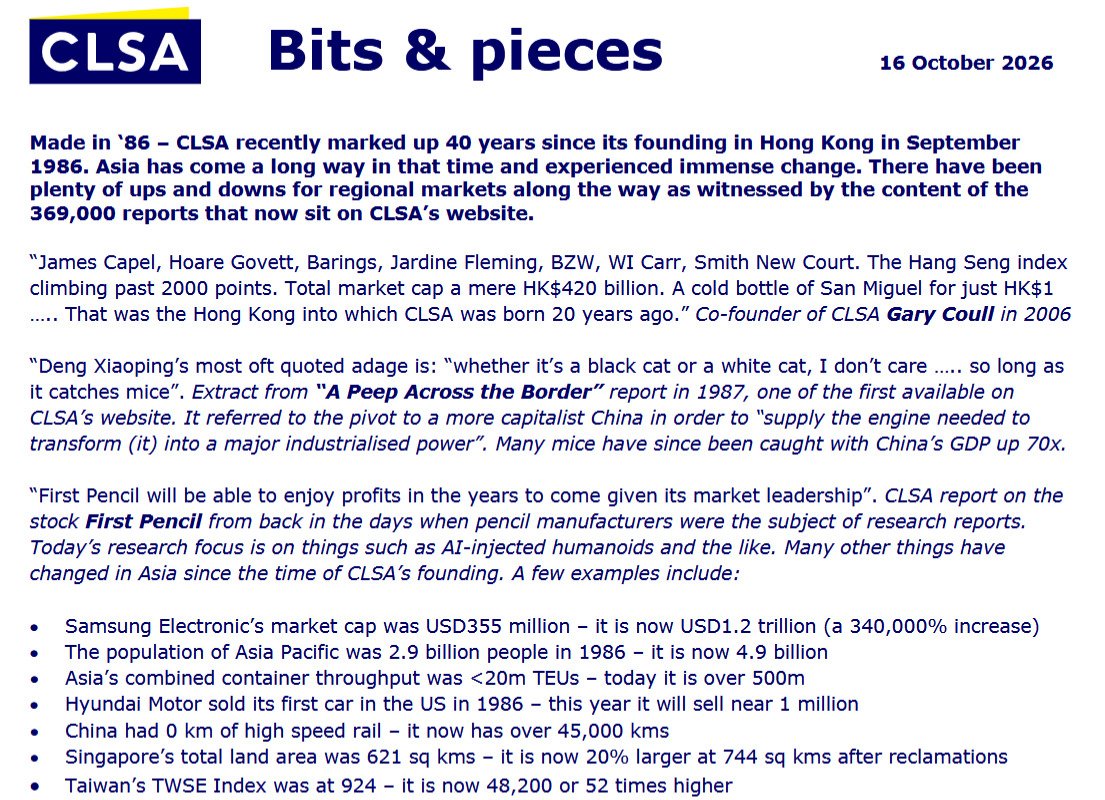
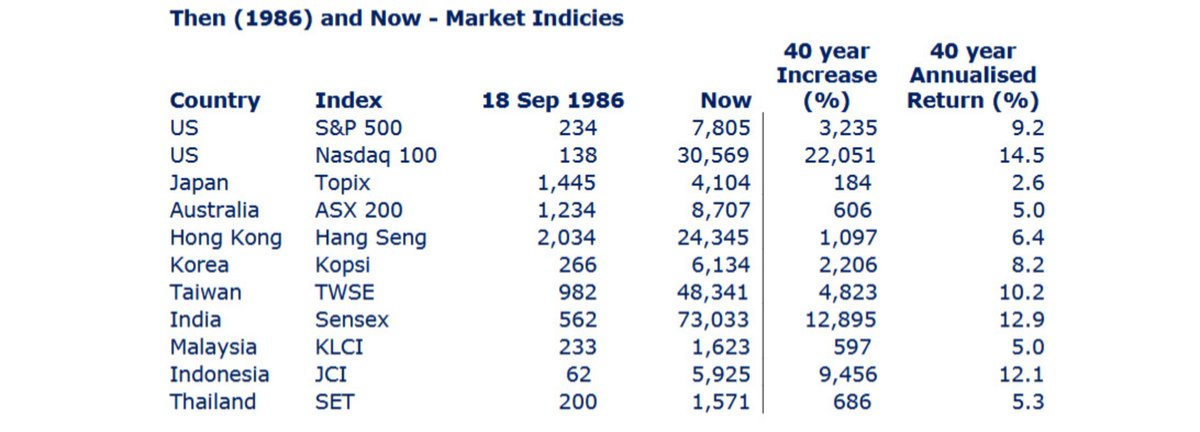
CLSA recently completed 40 yrs. They came out with this note.
The 40 yrs index returns of Asian indexes is not that impressive especially considering the currency depreciation.
Also it helps you set the base rate.
Lower your expectations!!!