Stalin sent political prisoners to gulags after a show trial before regime stooges. We saw the Soviet Union as monstrous. We were America. Here we are now. Our country as we know it ended today.
15-30 you will feel like their is endless time.
Then at 30ish you will realize there is not, but there is still time.
At 35 you will realize you had nearly no time at all and your life runway is pretty much set, making adjustments becomes WAY harder.
At 40 you REALLY do not want to be "figuring" it out. At 40 you want to be enjoying your fruits bigly and have your life stats/skills maxed out.
It's incredibly important you max out your stats, skills, talents as much as you can 15-35. Yes I said 15.
If you are 15, you should be finding your passions and future skills and going HARD on them.
If you have kids that age, you should be exposing them to as many different things as you can.
Biggest regret I have is I didn't get into combat sports, start coding, playing guitar until my 30s. I also wish I had started learning about money/business way sooner.
Just general friday thoughts for the youth.
There are people who will look your straight in the eye and tell you that our government was founded on slavery and genocide, that it protects and enriches the powerful at our expense, and that we should make it much bigger and rely on it for all of our needs.
Market Update : I've been a bit quiet. Mostly because I have nothing new to say. But here's my most current thoughts :
Recap : Caught the S&P bottom at 3,500 and bought crypto at that time. Sold at about 4240. Got back in on at the dip and sold 4100 (with Similar bitcoin timing). Have been out making 4-5% on my money since. My logic below.
So what's up :
Yes it stinks I missed this most recent rally. However at this point I don't think we are in a bull. I don't think the RoR is there. I don't think the market with sustain enough to make any 2021 like alt coin gains.
There could be GOOD gains on the table for GOOD traders, but nothing life changing or easy for on side non professional traders like myself.
I also dont think this is a good entry point in stocks, which I have been much better at looking at and are MOST of my interest since I am much more interested in storing large sums of money long term VS trading in and out.
The only reason I can think to buy right now is fear of missing the next bull run if it occurs. I dont see a potential to make big gains here worth the energy or risk.
AKA pretty much my same exact position since September. AKA I dont see a 2021 market brewing. I dont see some way I can pull of a quick 2-5x on a large sum of money without excessive risk.
I also dont see a time ROI that beats working on my businesses. In 2021 with heavy focus you could make millions per month with little risk. This is 100% not the case RN. There's massive risk and the gains are 2x-3xs at best in return for absolute focus.
You 100% can make money here if your a excellent trader, but that I am not nor do I think I can perform outside of outlandish bull markets...thus I will wait for one and if I'm not confident, ill just keep my money safe and making me safe money.
No one can say what will happen for sure, but my money is on
-This not sustaining
-Recession hitting later this year
Everything points to problems, war and turmoil in the economy. There is nearly no condition set up similar to 2021 other then the DESIRE for this to be 2021 again.
THAT SAID : In my video at 3500 S&P I predicted they had printed WAY to much money and that we were actually far far lower when you factor in the m2 money supply.
Frankly I should I stuck to this theory as I think that is what happened with Bitcoin.
A $1 pre 2021 = 1.5 to $2 now. Thus we actually did hit a sub $10k Bitcoin in 2020-2021 values...Which I believe is what people still judge it by.
This is false. As 15k bitcoin is actually more like a 7.5-10k bitcoin.
I nailed the S&P but really did not apply this as much as I should the same way with Bitcoin and crypto. The way Bitcoin reacted to the bank crisis also totally surprised me.
That said
I frankly do not see how with this much money flooding the market we go to 10k. Theres just to much money printed. Even if Binance and Tether go down it could be hard to get there and that would be the BIG buy chance.
I think a pull back to 22-25k is almost guaranteed, and outside world war 3 a good time to start taking long term positions IF IF IF the S&P also is pulling back as well.
I think most moonboy/non trader/holder types will just lose their money again as they always do. Gamblers always make the biggest gains and then match them with the biggest losses.
Thus I am just stacking cash from my businesses and focusing on making as much money as possible when the time comes.
THERE is IMO a 25% chance we just fuck all and go back to bull. But I think theres a 70ish% chance we are in for another big pull back in stocks and thus also in crypto...But not to 15k.
The only thing I am really looking for is the first mainstream web3 game. This will start a bull run in gaming regardless of the market. This will probably be the best shot at making STUPID X's the next 2 years or so.
That's all. I just rather get this all in one post VS beating a dead horse over and over for months.
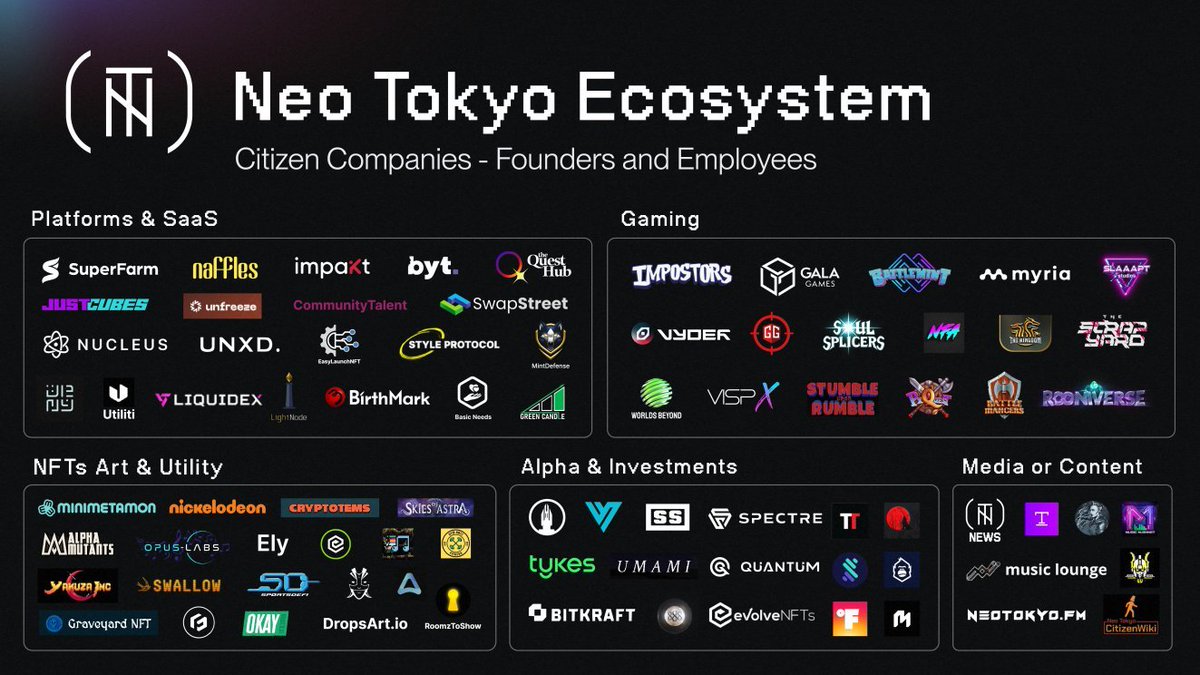
As a community of founders/builder/VCs/Devs & countless projects/teams in the gaming space...
It only make sense to pool knowledge so we can best position to scorch earth when the gaming bull come
Our weekly founders table is essential to that culture. Should be a good one.
1/19
US banks are more fucked than I thought.
Cato institute estimates: "$1T-$2T of withdraws from US Banking in the next 12 months"
To contextualize, US commercial assets according to Fed is only $24T.
So that'd be an 8% of all assets, or 12% of deposits
The law firm that litigated the original Operation Chokepoint case in 2014 just published a whitepaper explaining how the banking regulators are using the same unlawful threats and pressure tactics against the crypto industry in 2023.
This is a must read:
https://t.co/Ko0lodmqZz
If the RESTRICT ACT (“Tiktok ban”) passes, it will be used to attempt a ban on #bitcoin.
Have any of y’all actually read the text of the bill?
This isn’t about Tiktok. This gives the executive branch total control to police the internet.
Wake up.
PRINT TRILLIONS WHILE HIKING RATES
The Fed now has “high rates” like SF has “low crime rates”. It says it does, but it doesn’t.
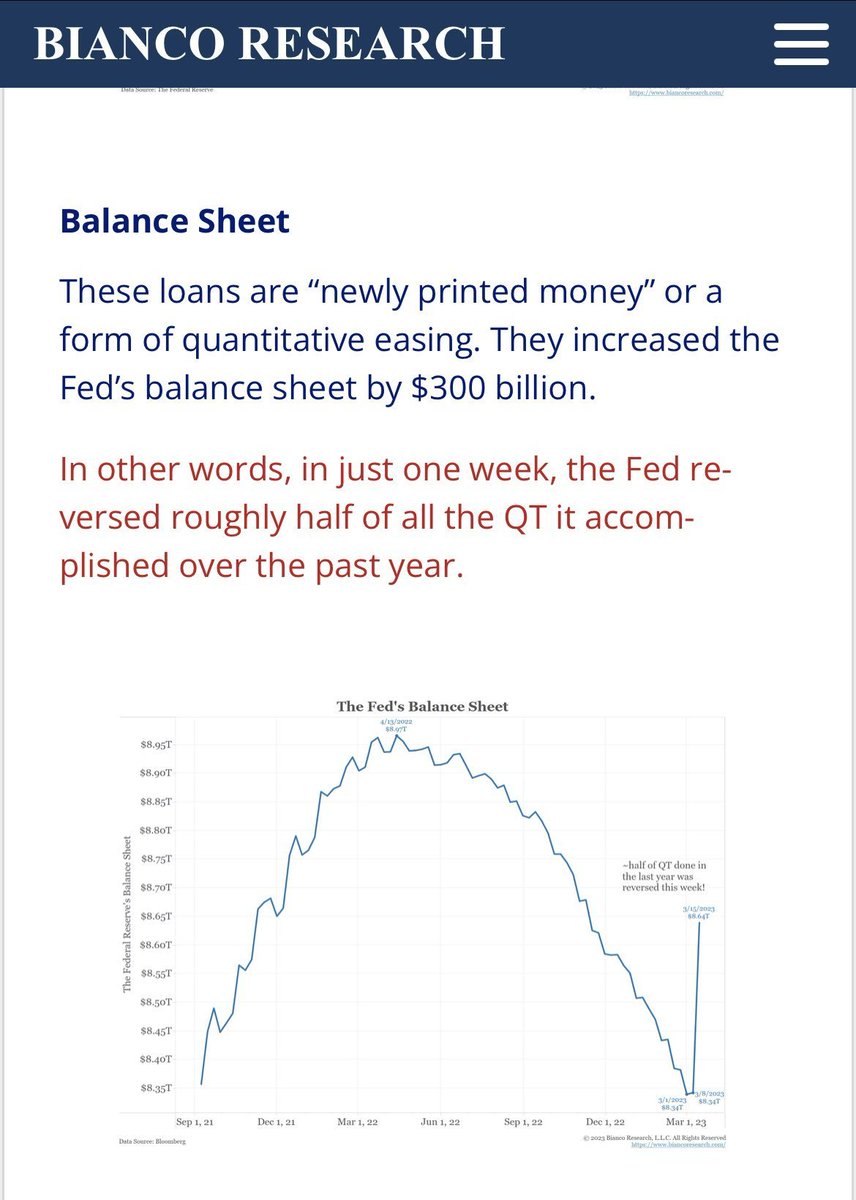
Because you have to be pretty naive to think today’s rate hike means the Fed is still “fighting inflation”. You can see it in the graphs — the printing is already vertical[1,2], and trillions in new money is available for both domestic[3,4] and foreign[5] banks. Yet the Fed continues hiking rates to fool low information voters into thinking the last two weeks were just an isolated series of multi-hundred-billion dollar bank failures, and that their policy is unchanged. Nothing to worry about, the Western banking system is resilient, and it’s normal to have banks die at the rate of five in ten days![10]
Because that’s actually all this state does: it fakes the rates.
Remember when SF claimed officially low crime rates[6] even as criminals robbed stores in broad daylight[7]? Remember when FDA prevented labs from testing so we all underestimated the COVID infection rate[8], till old people in New York started dropping dead? And remember when the Fed claimed the inflation rate wouldn't be a problem[9] before anyone buying groceries found out it was an emergency?
The American state fakes the rates.
And that’s what’s happening with today’s “hike”. After killing five of their own banks[10], catalyzing a series of bank runs[11], and realizing the public now knew they’d made hundreds more banks insolvent[12,13], the Fed rolled out programs over the last two weeks that broke the normal relationship between “hiking rates” and “tightening monetary policy”.
All the losses the Fed rate hikes cause for domestic banks?
They’re printing money to cover it.[14]
All the losses they cause for foreign banks?
Printing money to cover that too.[15]
And the losses they cause for depositors?
Naturally, more printed money![16]
So now the banks don’t publicly die from bank runs. Instead, even as this rate hike keeps pushing bank stocks further into the ground[17], and banks further into insolvency[18], the banks know they can just get more printed money (eg at the discount window[19] for BTFP) to cover their losses. That’s what BTFP, the swap lines, and the effective “FedDIC” policy mean: infinite money.
And this infinite money is no longer abstract. It’s printed dollars that individuals touch directly when they wire their money out of banks they fear may collapse, which is happening everywhere from community banks[20] to Credit Suisse[21]. The money printer is now connected directly to your checking account. And in the digital era, the bank runs are of a historical scale.[22]
Remember also: the BTFP, swap lines, and FedDIC measures are *so enormous* that the Fed is doing them over weekends[23] with all the other central banks[24], and publishing multiple joint statements[25,26] assuring people that the “system is resilient”, even as Moody’s has downgraded the US banking system as a whole[27].
One of the things I hate about this system is that it’s evolved to be opaque, like a snake that’s evolved camouflage. If the Fed came outright and *said* they were digitally devaluing the dollar by printing trillions, that they were monetizing the debt as Dalio predicted[31] and even getting bondholders to abet the devaluation, everyone would flee for the Bitcoin exit. So instead they lie, to themselves and to others, just as Jean-Claude Juncker recommended[32]. As with CDOs[33] in 2008, the point is to fool themselves and to fool you.
But you have to see through the camouflage. They’re printing trillions[34,35] even as they’re hiking rates. Indeed, they’re printing trillions to compensate for the *consequences* of hiking rates. There will of course be other consequences to printing trillions. You can wait to find out, or you can get into Bitcoin now.
5 figures and 35 citations follow. 👇