@JonkooTrades the +14% in 2028 isn't the scary part, the depreciation from 2026-27 landing in the p&l is. cash shows it first: msft's last quarter capex was $41b (+70% yoy) and fcf went from $20.3b to $15.8b. earnings catch up later
@JasonL_Capital this is the supplier side of the same trade. the buyer side: msft's last quarter capex was $41b (+70% yoy) and fcf fell from $20.3b to $15.8b. your picks print what the hyperscalers have to fund
@DavidAgentic@StockSavvyShay which is why it's a cloud product, not a model feature. only whoever owns the infra under the models can put the switch outside the runtime. that's the part the $41b a quarter of capex is actually buying
@mistressdivy if net cash is ~$20b, one quarter of capex is already 2x that. msft's last quarter was $41b (+70% yoy) and fcf fell from $20.3b to $15.8b. no leverage today, but the cushion shrinks fast at that pace
@iamharxh msft is the one where the meme shows up in the numbers. last quarter capex hit $41b (+70% yoy) while free cash flow went from $20.3b to $15.8b. growth is real, the cash conversion is the open question
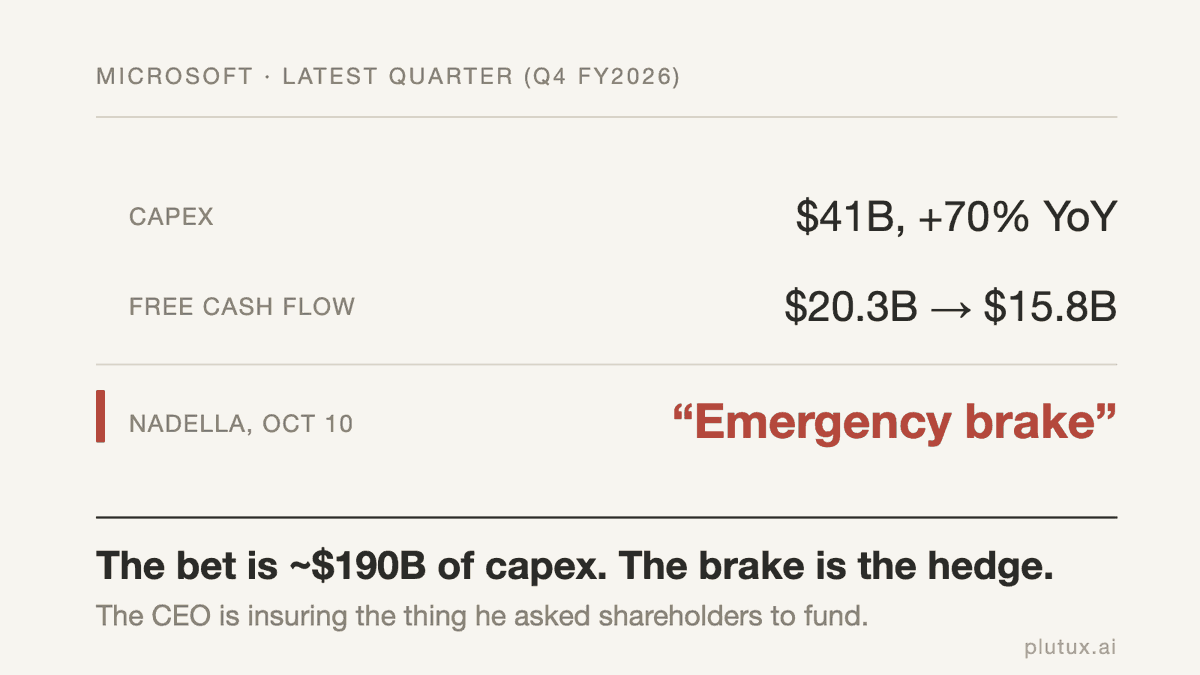
nadella just asked for an "emergency brake" on frontier ai models. same quarter: capex $41b (+70% yoy), free cash flow $20.3b -> $15.8b, and a ~$190b 2026 capex plan. nobody buys insurance on a bet they're sure about. the capex is the bet. the brake is the hedge
Dimon's AI warning this week: 2M truckers going from $150K a year to a $25K job means "civil unrest," so phase it in.
Worth knowing: $150K is the top of the range. BLS median for heavy truck drivers is ~$57K. The squeeze is real, the starting point is lower.
Caveat: Lennar guided Q4 margins to 15.5-16% and said incentives may stay aggressive. This reads as a 2027 bet, not a next-quarter one. Breakdown: https://t.co/LPZ3QysQxd
Berkshire now owns ~11.2% of Lennar. The timing is the interesting part: most of it was bought the week Lennar cut delivery guidance for the 2nd time this year and the 30-year mortgage broke 7%.
It's also not a standalone stock bet. Berkshire closed the $8.5B Taylor Morrison deal in July and already owns Shaw, Johns Manville, MiTek, Acme Brick, Benjamin Moore. It gets paid whether the recovery shows up as volume, price, or consolidation.
Vendor financing isn't new (Nvidia-OpenAI, AMD-Anthropic). But when the seller funds the buyer, revenue quality is the number to watch, not revenue growth. Breakdown: https://t.co/Ms8vExCC40
Anthropic's IPO filing has a line worth rereading: Broadcom agreed to lend it up to $42B, to lease Broadcom-designed TPUs. That's the same size as Anthropic's 2025 net loss. Revenue was $4.6B.
It can afford it: $13.7B of free cash flow last quarter alone. The risk isn't the principal, it's concentration. ~$161B of Anthropic's obligations are Broadcom-related, ~80% non-cancellable, and Broadcom's FY28 AI target leans on that ramp.
Caveat: paycheck to paycheck is self-reported, and a $300K household maxing a 401k can feel tight on paper. But the trade-down showing up in earnings is real. Breakdown: https://t.co/TQy3RVjVEM
Goldman's 2026 retirement survey has a weird shape. Living paycheck to paycheck: 42% of people under $100K. 23% at $100K-$300K. 36% of people over $300K. The stress isn't a line that falls with income, it's a U.
And the stocks already priced it. Lululemon is 58% off its high after cutting guidance. Ralph Lauren sits near its high, Tapestry grew sales 11%. Rich households aren't quitting the category, they're trading down one price tier.